


- Leonardo DRS recently secured several defense contracts, including integrated electric propulsion systems for the Republic of Korea Navy’s KDDX destroyers, along with agreements for missile launch electronics and tactical transceivers.
- The memorandum of understanding between HawkEye 360 and Leonardo to combine RF sensing with Leonardo’s ISR and geospatial services indicates tighter integration of sensing, data and European-focused intelligence solutions.
- This analysis will examine how Leonardo's broader investment narrative connects with Leonardo DRS's new defense contracts across naval and air domains.
Leonardo Investment Narrative Recap
To own Leonardo you need to believe its mix of helicopters, defense electronics, cyber and space services can turn a strong order backdrop into sustained earnings while it works through weak spots like Aerostructures and heavy investment needs. The HawkEye 360 MoU fits that story by deepening ISR and space data capabilities, although it does not change the near term picture on its own.
The main near term swing factor is execution on the capacity boost and efficiency program so that forecast earnings growth and cash conversion actually show up. The biggest risk remains structural drag from loss making Aerostructures and any strain from integrations and higher borrowing, which could pressure group margins if operational delivery slips.
The HawkEye 360 agreement is the clearest operational tie in here because it plugs RF sensing into Leonardo’s Telespazio and e Geos services and anchors more of the ISR value chain in Europe. That aligns with the group’s push into digital defense, cyber and data heavy services, where analysts already expect higher margin contribution.
For you as a shareholder, the practical question is whether this kind of space and ISR cooperation can scale fast enough to matter against much larger helicopter, electronics and aircraft units while Aerostructures still drags. The MoU also concentrates more activity in Europe, so future shifts in EU defense or data sovereignty priorities remain a background risk to watch.
Leonardo's narrative projects €27.4b revenue and €2.0b earnings by 2029. This corresponds to 11.5% annual revenue growth and an earnings increase of about €0.7b from €1.3b today.
Uncover how Leonardo's fair value indicates a 36% potential upside to its current price before the market closes the gap.
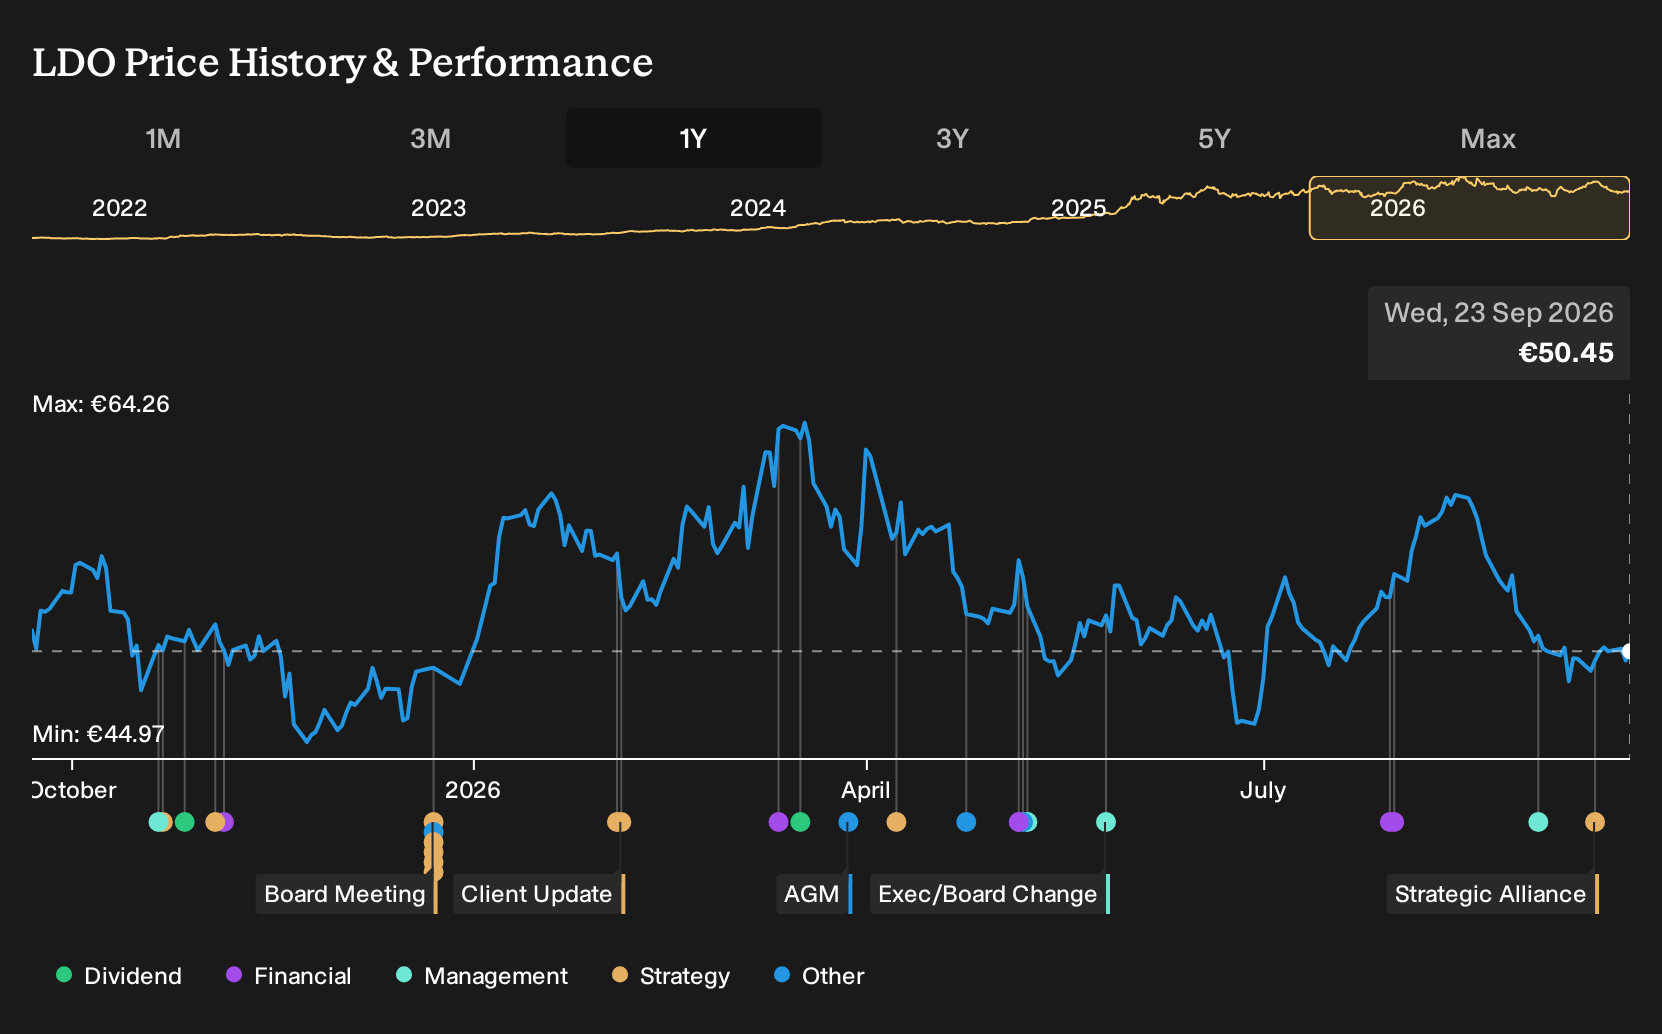
Exploring Other Perspectives
One alternate view puts a potential Aerostructures turnaround at the center of the Leonardo story rather than a drag. The most optimistic analysts were already penciling in €28.4b revenue and €2.2b earnings by 2029 before this HawkEye 360 deal, so forecasts and narratives may evolve as the ISR news beds in.
Explore 4 other Leonardo fair value estimates, including one that suggests as much as 59% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Leonardo research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo's overall financial health at a glance.
Looking for more investment ideas beyond Leonardo?
Once you have formed a view on Leonardo, it can help to widen the net and compare it with other opportunities that share similar quality, income or risk traits. The Simply Wall St Screener lets you filter the market quickly so you can focus on a small group of candidates that actually match your preferences.
- For investors who want income today rather than just potential price moves tomorrow, you could start with companies that combine higher yields with resilient profiles by checking out 161 dividend fortresses.
- If capital preservation matters most to you, you could focus on businesses with steadier balance sheets and cleaner fundamentals by reviewing the list of solid balance sheet and fundamentals (198 results).
- When you want to move before the crowd, you might concentrate on under followed quality plays with strong financials using the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com