


Inflation surprised on the soft side in August, with CPI at 4.4% and core at 4.1%, and that cool print has quietly shifted the conversation around South African interest-rate-sensitive shares. When price pressure looks contained, companies tied to borrowing costs and bond yields can move quickly, and sitting on the sidelines can feel expensive. This article unpacks three stocks from the screener that appear well placed and explains how this inflation backdrop may affect their risk and return profile.
The three stocks below are a sample set only, and the full screen surfaced 27 more South African interest-rate-sensitive financial and property companies with equally compelling narratives that are not covered here. To see the broader field and start narrowing in on your own highest conviction ideas, head straight into the South African Interest-Rate-Sensitive Financials and Property screener.
Redefine Properties (JSE:RDF)
Redefine Properties is a large South African REIT that gives you direct exposure to interest rate sensitive commercial real estate, with a R101.2b asset platform spanning local retail, offices and industrial properties as well as Polish retail, logistics and self storage. Revenue is heavily skewed to South African retail at about R4.1b, offices at roughly R3.0b, industrial at R1.5b and international operations adding around R2.5b. The stock carries a market value of about R42.2b.
For an investor focused on how South African interest rates feed through to property values and funding costs, Redefine Properties is a pure play. A large local portfolio, a meaningful offshore buffer and strong net margins tie its income profile tightly to bond yields and funding spreads. This puts significant emphasis on how changes in less visible pressures on its debt costs may affect overall performance.
Those funding pressures make the next step clear: access the Redefine Properties financial health report to see how Redefine Properties stacks up if rates keep surprising.

Growthpoint Properties (JSE:GRT)
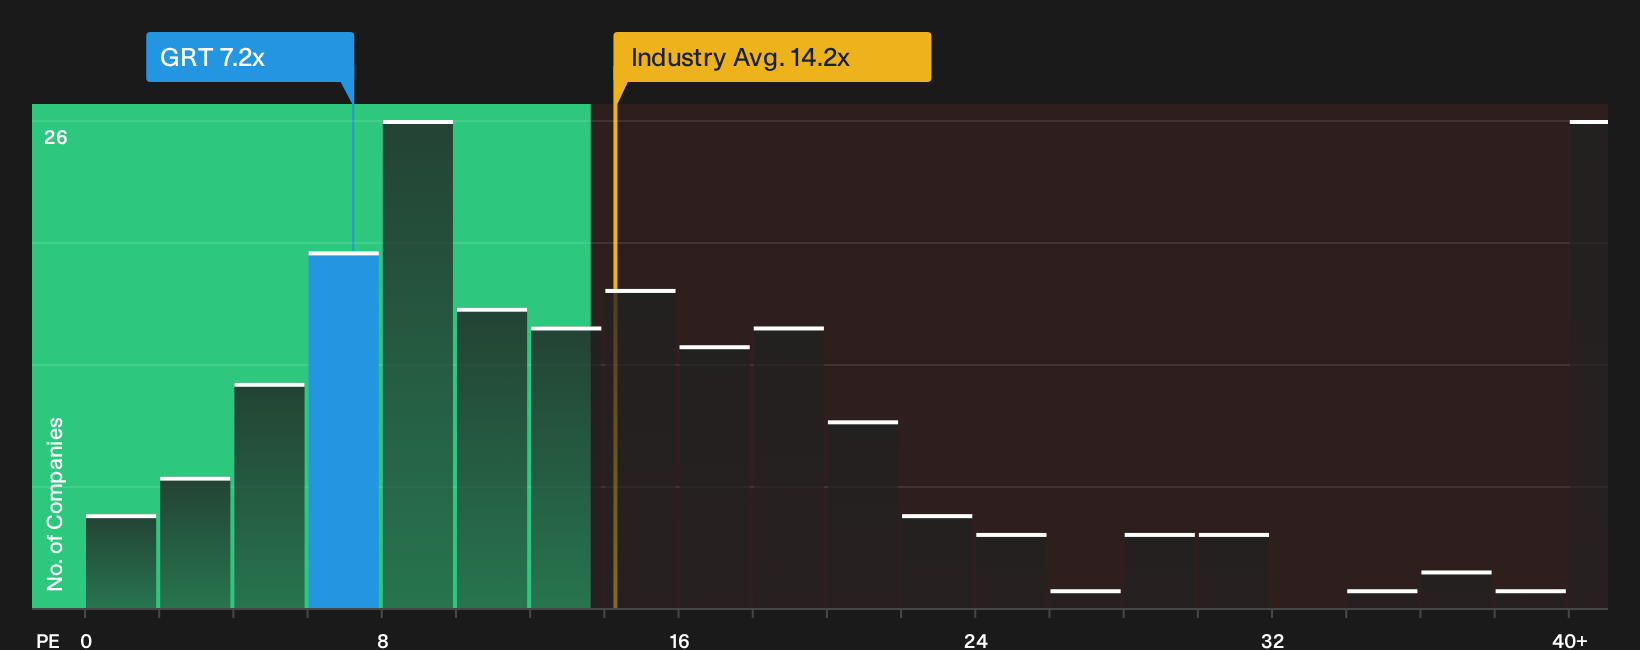
Growthpoint Properties is a large JSE-listed REIT that gives you broad exposure to South African interest-rate-sensitive property. It owns hundreds of local assets alongside offshore holdings and a fund management arm, with a market value of about R54.3b.
For readers building a view on South African rates and bond yields, Growthpoint Properties is a flagship REIT whose earnings, valuations and 8.39% dividend yield are closely tied to funding costs. Softer August inflation eases immediate rate pressure, although one unseen shift in discount rates or cap rates could still matter a lot for income and asset values.
That kind of move in cap rates and discount rates can reshape the whole story, so review the 2 key rewards and 3 important warning signs (1 is major!) before pricing Growthpoint Properties using a simple yield screen.
Hyprop Investments (JSE:HYP)
Hyprop Investments is a specialist retail REIT in the South African Interest-Rate-Sensitive Financials and Property screener, owning high quality malls like Canal Walk, Clearwater and Rosebank Mall. South Africa generated about R3.3b of business revenue, Eastern Europe R1.7b, and the group is valued at roughly R25.1b.
Hyprop Investments gives you concentrated exposure to South African interest rates through prime malls and a leveraged balance sheet, while trading on a P/E of 7x and paying dividends. It sits squarely in the “rate sensitive” camp, which means a single shift in funding costs can quickly reshape cash flows investors rely on.
When a single funding change can reshape Hyprop Investments so quickly, scan the 2 key rewards and 3 important warning signs (1 is major!) to see what the current income story might be missing.

Seeking Fresh Alternatives Beyond These REITs
Fresh opportunities move fast. Breakout themes gain momentum, quiet winners get spotted, and laggards keep dropping. Scan curated stock ideas before the crowd and consider your options.
- Identify income workhorses that aim to keep paying when others stall by reviewing the 161 dividend fortresses while yields still look compelling.
- Track early momentum in next generation automation leaders by scanning the 94 robotics and automation stocks before these stories stop flying under the radar.
- Explore opportunities ahead of potential infrastructure buildout cycles and review the 39 power grid technology and infrastructure stocks while these ideas remain quietly priced.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com