


Canfor has delivered a strong share price recovery this year, which sits uncomfortably next to a much weaker record over the past several years. The key issue now is whether that rebound is properly supported by its sales base.
- The stock is down 44.4% over 5 years, which puts long term shareholders on alert about how much of the recent optimism is really backed by the revenue line.
- The business model remains heavily tied to lumber and related products, so any change in pricing power, input costs or demand trends can meaningfully shift how much sales support the current market value.
- There is a second opinion on Canfor worth weighing. See what analysts think Canfor's shares could be worth.
For investors, the debate is whether Canfor's current share price around C$15.91 is properly explained by the level and quality of its sales today.
If you are weighing whether Canfor's sales really back up a C$15.91 share price, it can help to compare that same question across 6 high quality undervalued stocks
Is Canfor Still Cheap on Sales?
P/S is a clean way to look at Canfor because the business is tied so closely to lumber volumes and pricing, which flow straight into reported revenue.
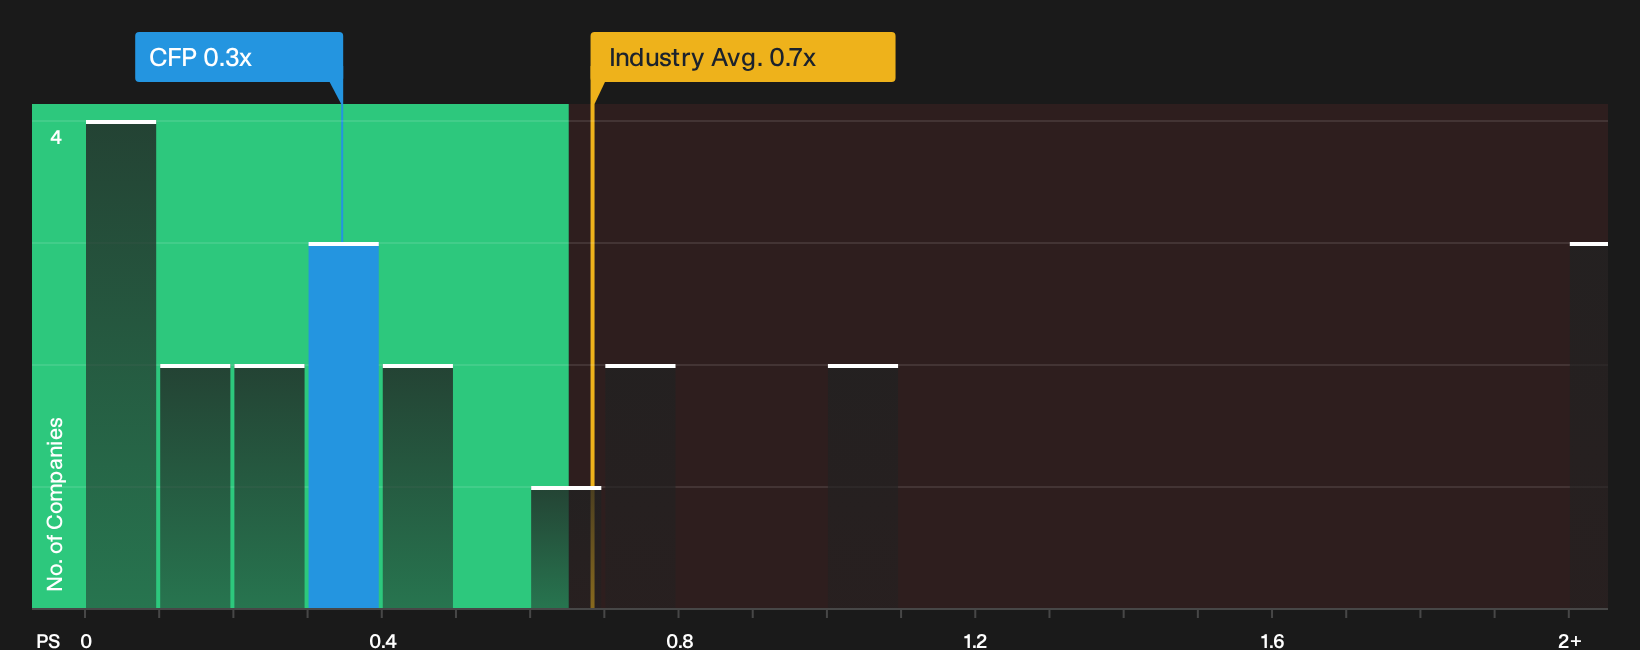
On this measure, Canfor trades on a P/S of about 0.3x, compared with a forestry industry average of roughly 0.7x and a peer group closer to 1.7x. The tailored fair multiple, which blends in factors such as the company’s margins, risk profile and size, also points to the current 0.3x sitting on the cheap side of what might be expected for this level of sales. For an investor weighing Canfor at around C$15.91, that low sales multiple suggests the market is putting a cautious price on each dollar of revenue. The key question is how durable and high quality those sales streams look over time. Explore the numbers behind Canfor's P/S valuation.
The Canfor Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that valuation puzzle around Canfor's share price and turn it into clear scenarios that spell out what kind of growth, margins and earnings profile would need to line up for the stock to be worth meaningfully more or less than today. Rather than relying on a single ratio or model, each narrative lays out the assumptions behind its fair value view so you can compare those expectations with Canfor's actual results on the Community page as they arrive.
One of the top community narratives on Canfor: 10% undervalued
"The acquisition of PinkWood increases exposure to value added engineered wood products, which can diversify the revenue mix away from more commodity exposed products..."
Discover why this Narrative puts Canfor at 10% undervalued.
Before you act on Canfor’s valuation, there is one more piece to check
The share price tells you what the market thinks today, while professional projections sketch out where the business might be in a few years and how that lines up with the current P/S story. Explore where analysts expect Canfor to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com