


MetLife (MET) just reported Q2 2026 results that put its Group Benefits segment in focus, with adjusted earnings in that unit up 25% year over year due to stronger underwriting and steady employee benefits demand.
MetLife shares trade at US$97.20 after a 90 day share price return of 14.85% and a year to date share price gain of 21.02%. The 1 year total shareholder return of 23.97% and 5 year total shareholder return of 80.54% suggest the recent Q2 Group Benefits strength is feeding into a longer running rerating of the stock rather than a short lived reaction.
Scan other insurers with resilient earnings profiles and healthy balance sheets by running the list of solid balance sheet and fundamentals (23 results) alongside MetLife after this Q2 Group Benefits update.
MetLife now appears to be a sturdier franchise after this Group Benefits surge, but with the stock up more than 20% year to date, are you still paying a fair price for that strength?
Most Popular Narrative: 7.5% Undervalued
MetLife is priced at $97.20 while the most followed valuation narrative anchors fair value at $105.06. This frames today’s Q2 Group Benefits strength inside a broader execution story that leans on technology, international expansion and capital light earnings.
Continued execution of the New Frontier program, which has already been associated with 10% EPS growth in 2025, a 17% adjusted ROE in the first half of 2026 and direct expense ratios at or better than target, suggests further scope to sustain earnings and free cash flow that underpin MetLife’s current valuation.
See why 27 investors see MetLife as 7% undervalued.
Result: Fair Value of $105.06 (UNDERVALUED)
Still, if fee based earnings at MetLife Investment Management stay near the low end of guidance or if Retirement and Income Solutions spreads remain pressured, this underpins the main narrative risk.
Find out about the key risks to this MetLife narrative.
Another View: MetLife Through The Earnings Multiple
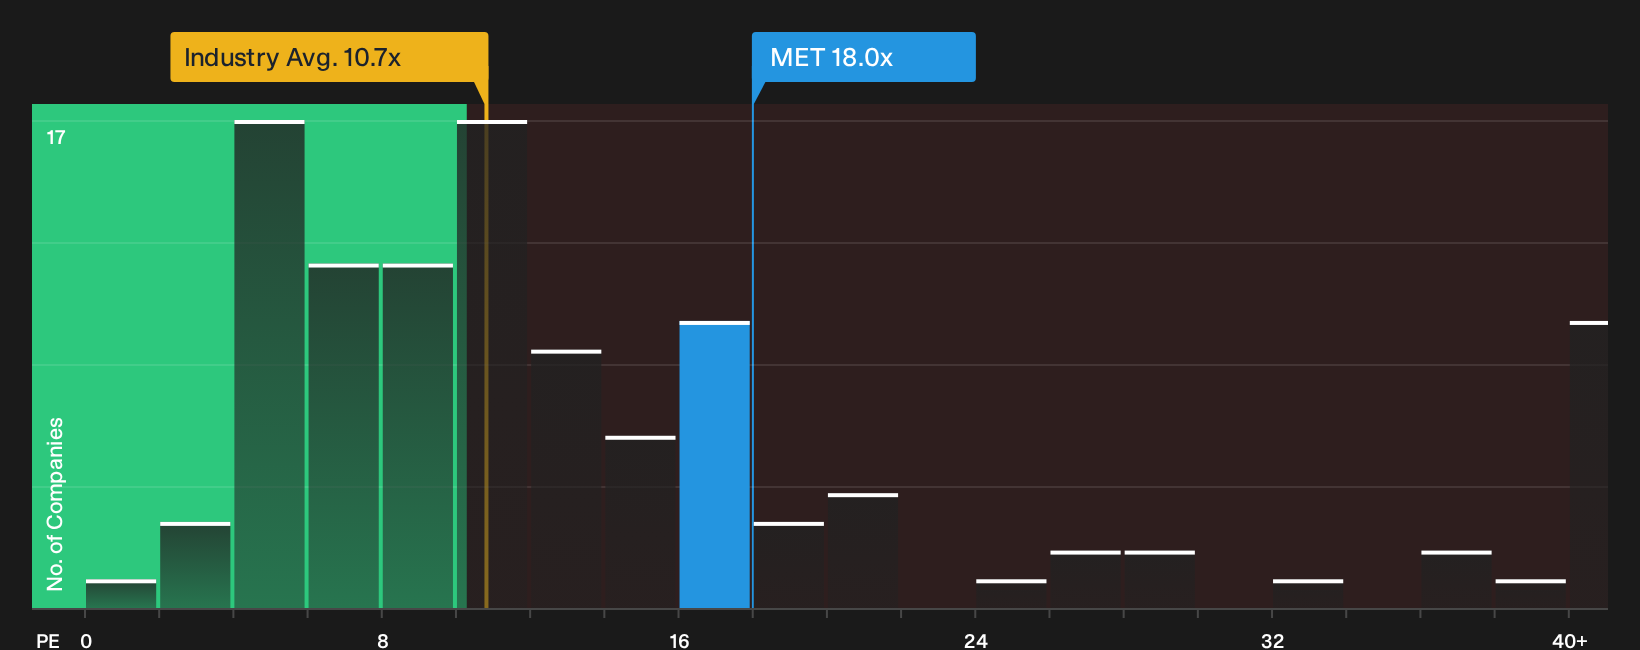
MetLife might screen as undervalued on fair value models, yet its P/E ratio of 18x sits well above the US Insurance industry at 10.7x, the peer average at 14.8x, and even the 14.4x fair ratio that the market could move toward. If sentiment cools, does that premium turn into valuation risk for holders?
For a closer look at how this earnings-based premium stacks up against the broader sector and the fair ratio, check the valuation breakdown next. Then weigh how much of that gap you are comfortable paying for the MetLife story. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
MetLife now carries both clear upside drivers and some flagged pressure points, so use this moment to check the data and refine your own stance. To weigh those trade offs directly, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond MetLife?
If MetLife has sharpened your focus on quality, do not stop here. Broader opportunity often appears where fundamentals, value and resilience quietly line up.
- Target stronger potential upside by scanning for companies that pair solid fundamentals with attractive valuations using the 30 high quality undervalued stocks.
- Strengthen your income base by reviewing businesses that offer robust yields and dependable payouts through the 7 dividend fortresses.
- Dial down portfolio stress by filtering for companies with sturdier financial footing through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com