


- Simmons First National is drawing attention after higher rate expectations resurfaced, with traders now seeing a stronger chance of another Federal Reserve hike that could reshape earnings drivers for its lending and deposit franchise across southern and midwestern markets.
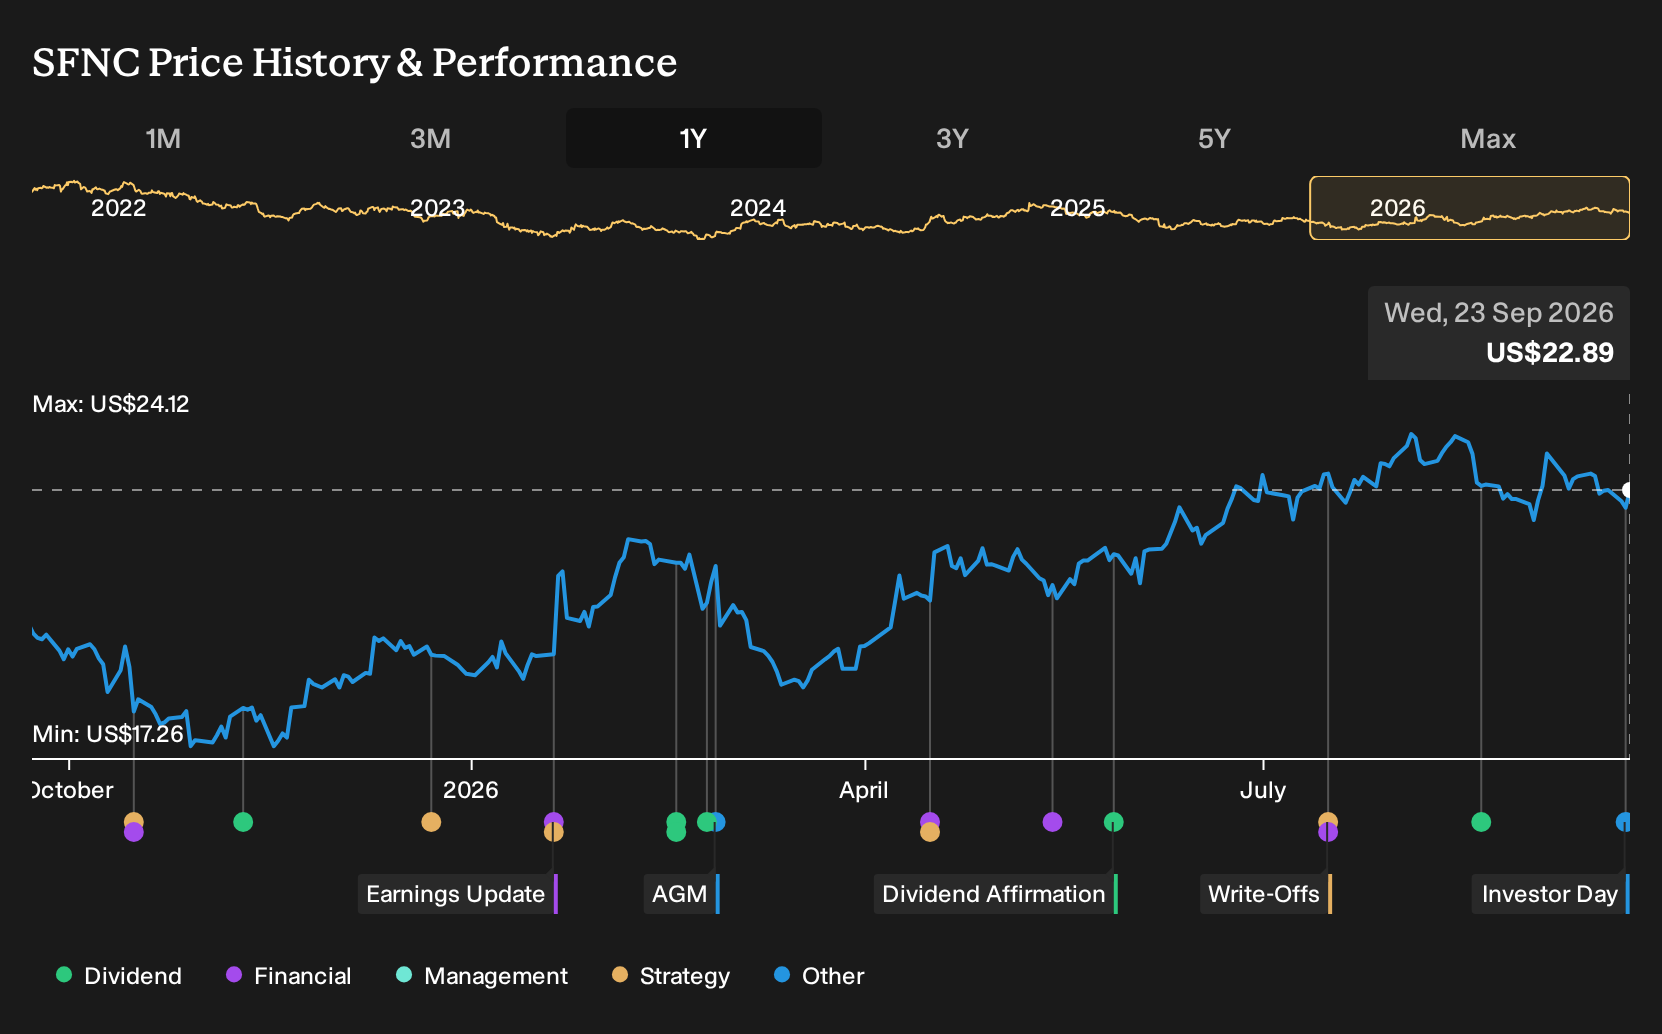
- Investors are also focusing on Simmons First National's upcoming December 10, 2026 Investor Day and its record of dividend increases. Many are viewing the combination of rising short term yields and management’s public messaging as an important moment to test the bank’s rate sensitive business model.
- We will now look at how Simmons First National's rate exposure could reshape the investment narrative as expectations for hikes return.
Simmons First National Investment Narrative Recap
To own Simmons First National, you need to be comfortable with a rate sensitive regional bank that is still working through recent losses and a mixed funding picture. The key near term swing factor is how higher short term yields filter through its variable rate loan book versus what it must pay to keep deposits. Rising rate expectations are important here but do not fundamentally change that core equation.
The biggest operational risk remains pressure on funding costs and credit quality, especially in commercial real estate and more volatile segments such as construction and agriculture. Heavy spending on technology and talent can also weigh on margins if loan growth or fee income does not keep pace in the next stretch.
The upcoming Investor Day on December 10, 2026, is the announcement that matters most for the current rate story around Simmons First National. Management plans to outline strategic priorities. This gives you a clearer line of sight on how the bank wants to position its balance sheet, expense base, and loan mix if the Fed keeps policy tight.
That event also arrives with a 3.8% dividend yield that is not well covered by current earnings, and with the business still unprofitable on recent numbers. For an income focused holder, the webcast and materials should be a chance to assess whether management’s plan, including ongoing technology investment and loan portfolio remixing, can support both the payout and a more resilient earnings profile over time.
Simmons First National’s current analyst storyline points to US$1.6b in revenue and US$666.7m in earnings by 2029, built on a very large 144% yearly top line growth assumption and an earnings swing of about US$1,016.2m from today’s loss of US$349.5m to that 2029 consensus figure.
Uncover how Simmons First National's fair value indicates a 13% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
The Simply Wall St Community contributes three fair value views for Simmons First National, stretching from US$17.02 to about US$36.72, which is a wide band for the same bank. Those opinions were formed before the renewed rate hike chatter and before the 2026 Investor Day announcement, so treat them as starting points and compare several viewpoints yourself.
Explore 2 other Simmons First National fair value estimates, including one that suggests there could be as much as 26% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Simmons First National research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Simmons First National. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Simmons First National's overall financial health at a glance.
Looking for more Simmons First National style investment ideas?
If the Simmons First National story has you thinking about how rate exposure, income potential, and balance sheet strength fit together, it can help to widen the lens and scan other listed businesses with similar traits but different risk profiles.
The Simply Wall St Screener lets you do exactly that by filtering for companies that match the mix of quality, value, and resilience you want to focus on next.
- For investors who want potential mispricing combined with quality fundamentals, start with a curated group of 30 high quality undervalued stocks that may line up better with your return and risk expectations.
- If reliable income is your priority, you can filter for payout strength and consistency by reviewing a focused 7 dividend fortresses that might complement or contrast Simmons First National’s yield profile.
- To keep risk in check while you search for ideas, you could concentrate on resilience by scanning a 31 resilient stocks with low risk scores that screens for steadier balance sheets and business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com