


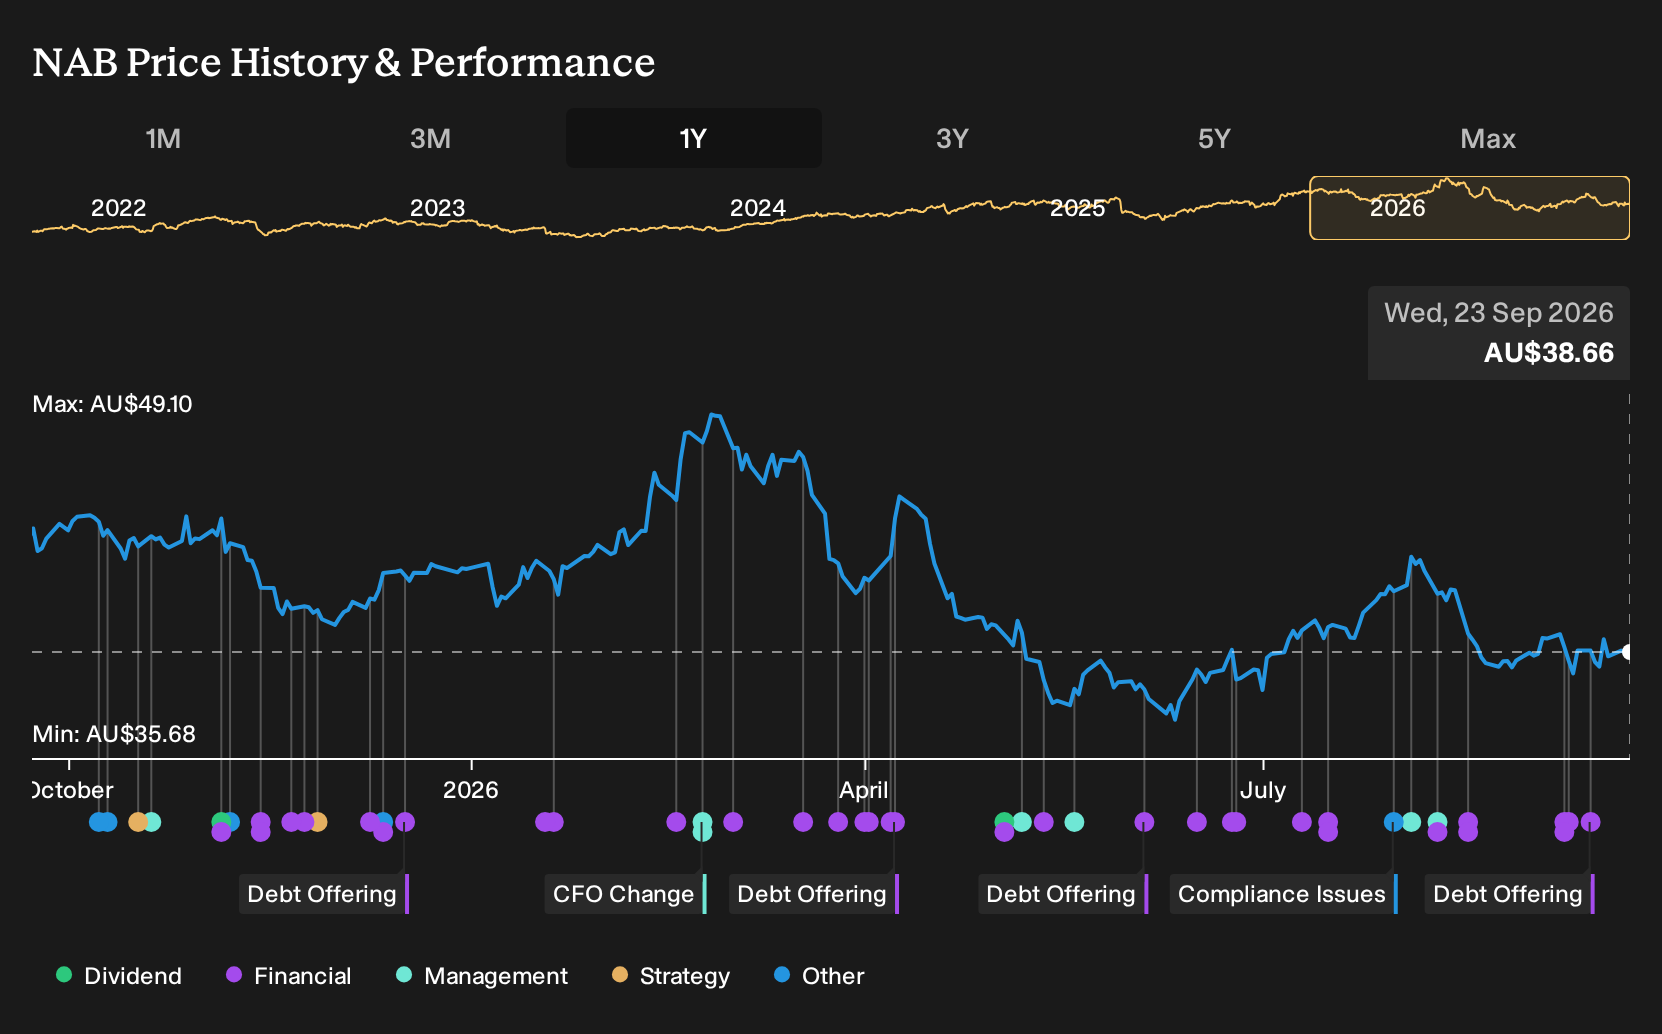
- National Australia Bank completed a ¥15b fixed to floating subordinated bond offering due 2036 and separately restored most services after a major digital outage that disrupted online banking, its mobile app, and customer support earlier in September 2026.
- The outage highlighted how central NAB’s digital channels are to day to day banking activity and underscored the operational risk that comes when electronic payments, apps, and business platforms such as NAB Connect go offline even for a short period.
- We will now see how National Australia Bank’s investment narrative around digital banking is tested by this recent large scale outage.
Scan how National Australia Bank’s outage risk compares with peers by reviewing a curated 7 resilient stocks with low risk scores focused on resilient balance sheets and robust operating profiles.
National Australia Bank Investment Narrative Recap
To own National Australia Bank, you need to be comfortable with a large, regulated lender that leans heavily on digital channels and business banking for future revenue. In the short term, the upside case still hinges on steady loan demand, controlled costs and stable credit quality. The recent outage looks more like an operational headache than a clear hit to that near term thesis, unless repeat issues emerge.
The bigger risk right now is execution on technology and compliance spending, which already pressures NAB’s cost base, at the same time as returns on equity are described as low and net profit margins have softened versus last year. The outage directly touches that risk bucket. It puts more attention on whether management can keep investing in digital and payments while holding the cost to income trajectory in check.
The ¥15b fixed to floating subordinated bond issue sits closest to this story. It shows NAB is still accessing long dated wholesale funding in multiple currencies, which matters for supporting loan books and ongoing technology and branch investment. Subordinated paper also forms part of regulatory capital planning, so execution in this market is closely watched by fixed income investors.
For you as an equity holder, that issuance is relevant to both catalysts and risk. Funding depth affects how confidently NAB can keep upgrading digital platforms and rolling out initiatives like the Cairns Community Hub model, where fraud and hardship support are brought together. At the same time, extra subordinated debt layers into future interest and capital management decisions, which you would want to weigh against already moderate revenue growth expectations and the bank’s current P/E premium to many peers.
National Australia Bank’s narrative projects A$24.2 billion revenue and A$8.1 billion earnings by 2029. This is based on an assumption of 5.0% yearly revenue growth and an earnings increase of A$2.0 billion from A$6.1 billion today.
Uncover why National Australia Bank's fair value is essentially in line with its current price.
Exploring Other Perspectives
Some of the lowest analysts see outage risk very differently. They already assumed slower tech progress at National Australia Bank and were working off softer numbers, such as A$23.7b revenue and A$7.8b earnings by 2029. You can use this more cautious lens to examine how those views might change in light of the digital disruption and bond deal.
Explore 4 other National Australia Bank fair value estimates, including one that suggests it could be worth just A$38.38.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your National Australia Bank research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for National Australia Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Australia Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond National Australia Bank?
If the National Australia Bank story has you thinking about portfolio balance, use the Simply Wall St Screener to line up alternatives with different risk and income profiles before you commit fresh capital.
- For investors who want growth potential without ignoring quality, scan a focused list of 16 high quality undiscovered gems that combine strong fundamentals with quieter market attention.
- If capital resilience is your priority, review a curated list of solid balance sheet and fundamentals (12 results) that surfaces companies with stronger financial footing than the broader market.
- Income focused readers who like to be paid while they wait can assess a targeted set of 3 dividend fortresses offering yields above 5% that may complement a position in a major bank.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com