


Albemarle earnings surge puts lithium exposure in focus
Albemarle (ALB) has grabbed investor attention after adjusted EPS for the second quarter reached US$3.75, far above analyst forecasts, with management pointing to strong lithium market conditions and heightened interest in critical minerals exposure.
The earnings surprise has landed in the middle of a choppy year for Albemarle, with the share price at US$113.47 after falling 19.8% over 30 days and 21.2% year to date, yet a 40.7% total shareholder return over 12 months suggests recent weakness follows a strong prior run as investors reassess lithium growth prospects and risk.
Scan beyond Albemarle and spot other critical minerals producers that screens highlight as potential outliers with the 36 best rare earth metal stocks.
After a sharp 12 month rebound and a steep recent pullback, Albemarle now splits opinion between those who see fresh upside ahead and those who think the big move already happened. Which side do current valuations lean toward?
Most Popular Narrative: 34% Undervalued
Albemarle's most followed narrative pegs fair value at $172.56 compared with the recent $113.47 close. The debate now shifts to whether the lithium story and cash flow path justify that gap.
The company is executing aggressive cost reduction and productivity initiatives (achieving a $400M annual run-rate in savings, 6 months ahead of plan), ramping low-cost asset expansions, and optimizing its conversion network, which is likely to structurally reduce operating costs and increase net margins in a lower price environment.
See why 188 investors see Albemarle as 34% undervalued.
Result: Fair Value of $172.56 (UNDERVALUED)
Still, the narrative around Albemarle can unravel quickly if lithium oversupply keeps prices weak or if geopolitical and regulatory shifts disrupt key producing regions.
Find out about the key risks to this Albemarle narrative.
Another View: Albemarle on Sales-Based Metrics
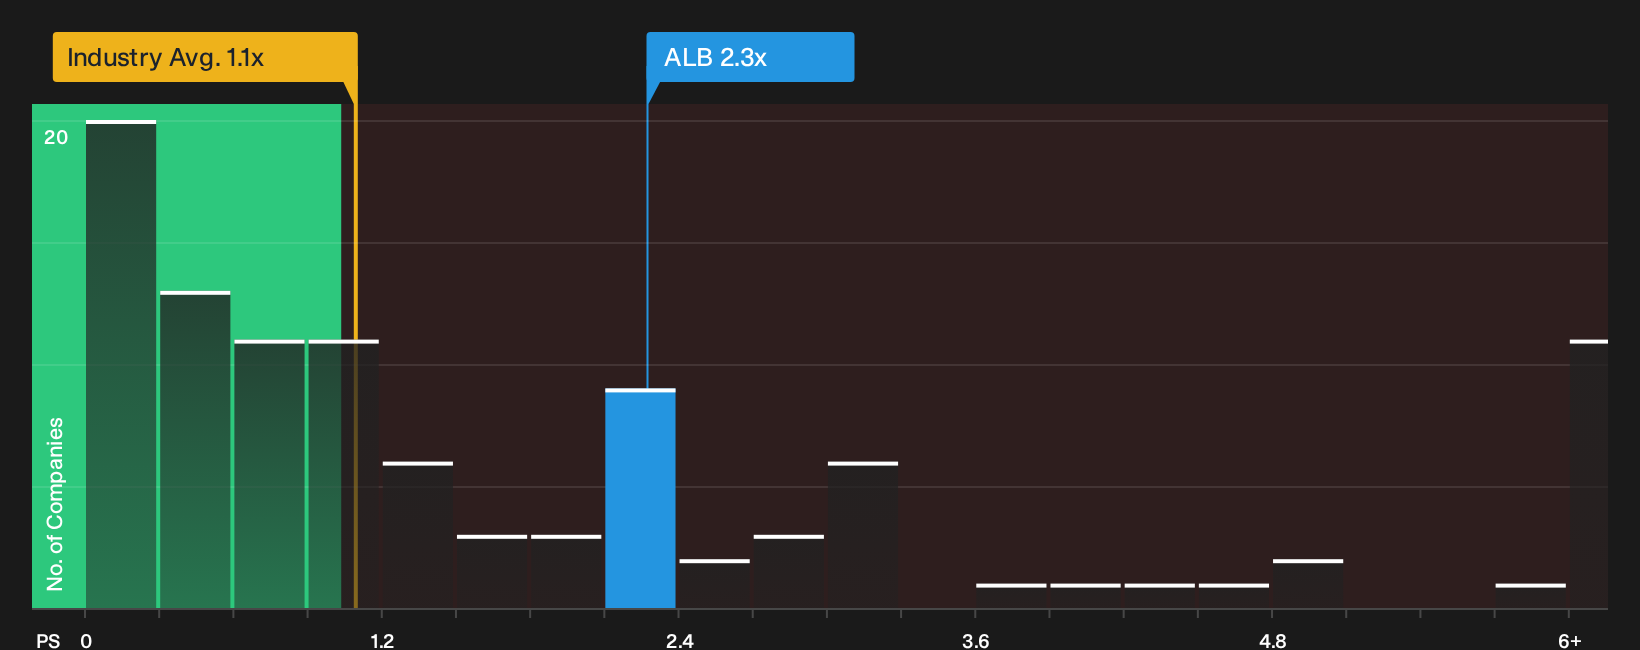
The SWS DCF model points to Albemarle trading below an estimated future cash flow value of $260.28, yet the market is pricing the stock at a P/S of 2.3x versus 1.1x for the US Chemicals sector and a 1.8x fair ratio. This lifts valuation risk and raises questions about how much of the lithium story is already embedded.
Investors who want to see how those cash flow assumptions compare with that richer sales multiple can dig into the full model from here, then decide which lens feels more realistic for their own thesis. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Investor sentiment around Albemarle appears mixed, with market participants weighing both potential advantages and possible risks. Review the numbers and decide where you stand by checking the 3 key rewards and 2 important warning signs.
Looking for more Albemarle-sized ideas?
Do not stop with Albemarle. Use the Simply Wall St Screener to hunt for fresh opportunities that match your goals before the next move leaves you behind.
- Target resilient compounding potential and filter for companies with durable balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Spot potential value opportunities early by scanning for 30 high quality undervalued stocks that financials suggest the market may be pricing conservatively.
- Strengthen your income playbook and seek out 7 dividend fortresses that pair higher yields with underlying business resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com