


- REGENXBIO and the University of Pennsylvania reached a settlement with Sarepta Therapeutics and partners over AAVrh74 gene therapy patents, with Sarepta agreeing to pay US$39.0 million and all related SRP-9001 and ELEVIDYS litigation to be dismissed with prejudice.
- The agreement not to pursue future patent claims on AAVrh74-based capsids for ELEVIDYS and similar Sarepta gene therapies reduces legal uncertainty around a core platform technology.
- Attention now turns to how Sarepta Therapeutics' investment narrative could shift as major AAVrh74 gene therapy patent risk is taken off the table.
Scan how other gene therapy and healthcare developers stack up on risk and potential by reviewing the 38 healthcare AI stocks alongside Sarepta Therapeutics' latest patent resolution.
Sarepta Therapeutics Investment Narrative Recap
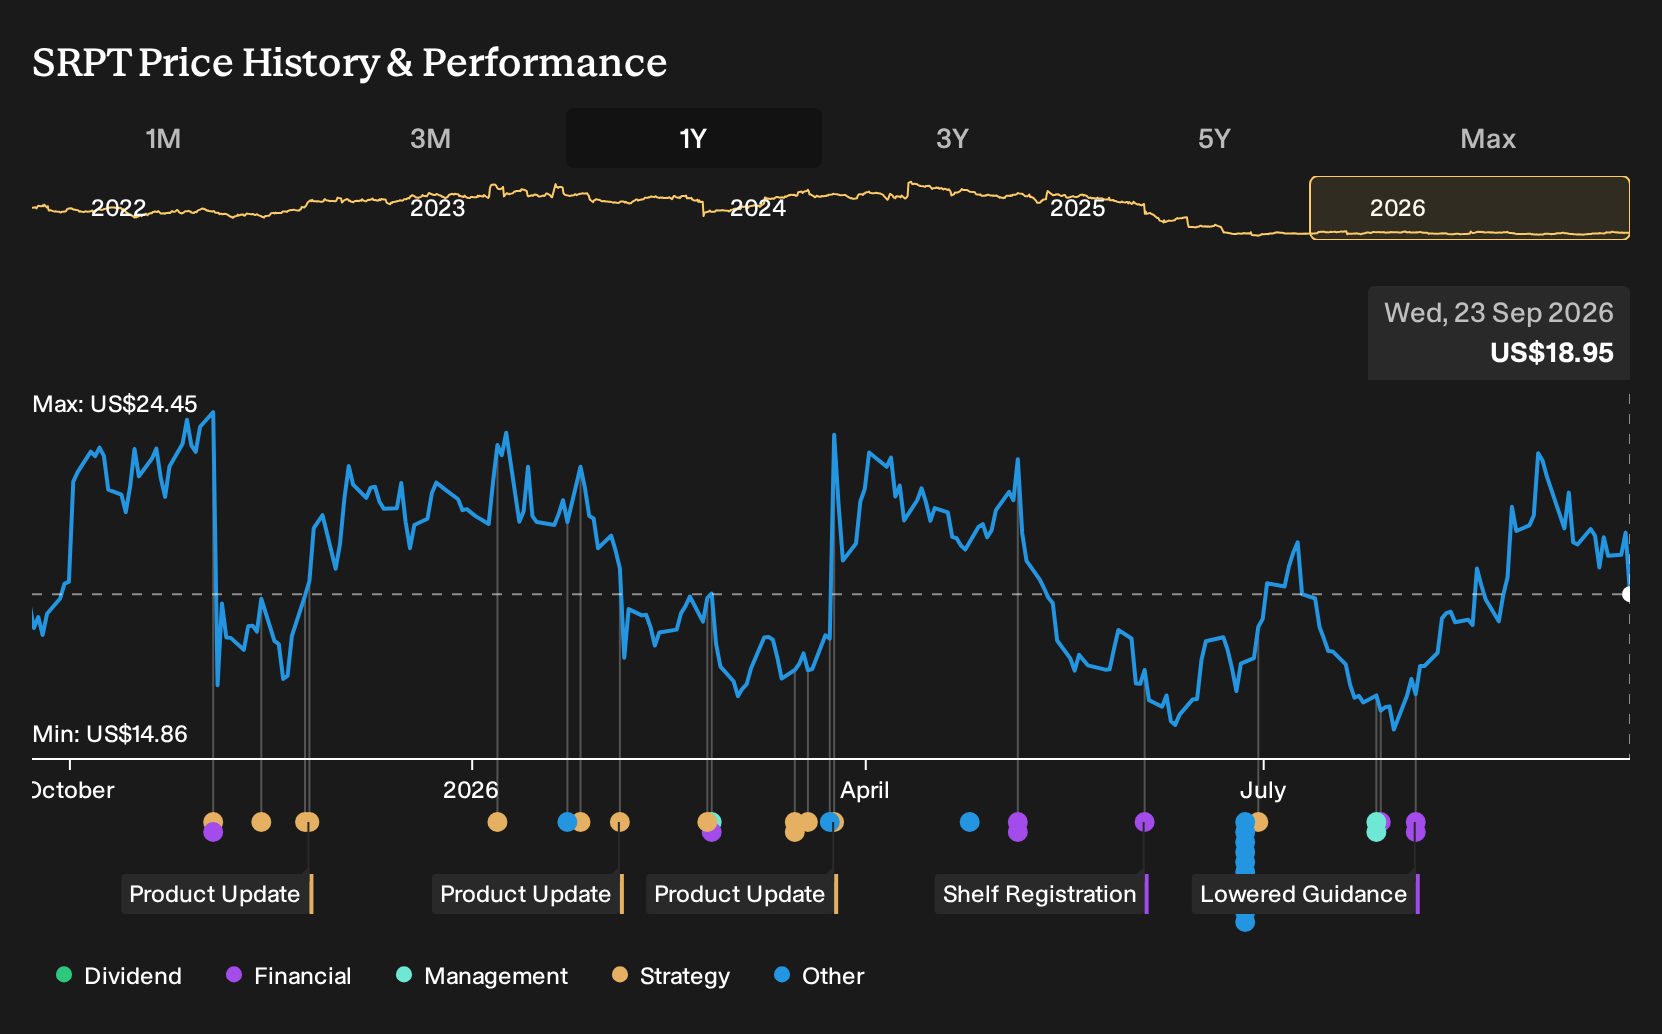
Sarepta Therapeutics asks you to believe that gene therapy for rare muscle diseases can become a durable business, not just a one product story. The REGENXBIO and UPenn settlement removes a specific AAVrh74 patent overhang for ELEVIDYS at the cost of a US$39.0 million payment. That looks manageable next to almost US$2.0b in annual revenue.
The near term focus still sits on ELEVIDYS uptake, site capacity, and how safety monitoring shapes physician confidence. The biggest operational risk remains treatment delays, complex single case agreements, and the impact of past safety events on demand. The settlement mainly trims legal noise instead of rewriting the commercial playbook.
The settlement most closely ties into Sarepta Therapeutics guidance around ELEVIDYS data updates and potential label expansions. Clearing this AAVrh74 dispute reduces a legal variable around a core capsid while the company works through administrative bottlenecks and site imbalances that have slowed the conversion of interest into actual infusions.
For catalysts, investors are still watching further safety and efficacy readouts for ELEVIDYS and any regulatory decisions on broader patient groups. Those events sit alongside progress in LGMD gene therapy and siRNA programs, which offer portfolio breadth. Within that broader context, the legal truce mainly acts as a cleaner backdrop for assessing execution on these clinical and commercial milestones.
Sarepta Therapeutics' analyst narrative points to US$1.4b in revenue and US$87.3 million in earnings by 2029, based on forecasts that assume revenue will decline 13.3% a year and earnings will move from a loss of US$713.4 million today to a profit of US$87.3 million. This represents an earnings swing of about US$800 million.
Uncover how Sarepta Therapeutics' fair value indicates a 14% potential upside to its current price before the market closes.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Sarepta Therapeutics’ broader pipeline as the key catalyst, not just ELEVIDYS. Before this legal truce, the bullish camp was modeling about US$1.6b of revenue and US$232.7 million of earnings by 2029. That is far above consensus, and this settlement could prompt analysts to revisit those assumptions.
Explore 3 other Sarepta Therapeutics fair value estimates, including an estimate that suggests as much as 3086% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sarepta Therapeutics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sarepta Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sarepta Therapeutics' overall financial health at a glance.
Looking for more Sarepta Therapeutics style ideas?
Once the Sarepta Therapeutics story feels familiar, it can help to widen the lens and compare it with other potential opportunities that fit different risk and return profiles using the Simply Wall St Screener.
- If you are hunting for quality at a reasonable price, start with a curated set of companies that screen well on valuation and fundamentals by reviewing the 30 high quality undervalued stocks.
- For a focus on resilience, consider businesses with stronger balance sheets and healthier financial footing using the list of solid balance sheet and fundamentals (23 results).
- Those looking for earlier stage potential can scan a targeted group of smaller, higher risk ideas with stronger financial profiles via the 9 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com