


- Norwegian Cruise Line Holdings has detailed the entertainment program for Norwegian Aura, including an exclusive Whitney Houston celebration created with her estate, plus new illusion, live music and nightlife shows tailored to the ship.
- This entertainment-first approach signals a push to differentiate Norwegian Aura’s onboard offering, aiming to support pricing power, occupancy and onboard spending through high-profile, experience-led content.
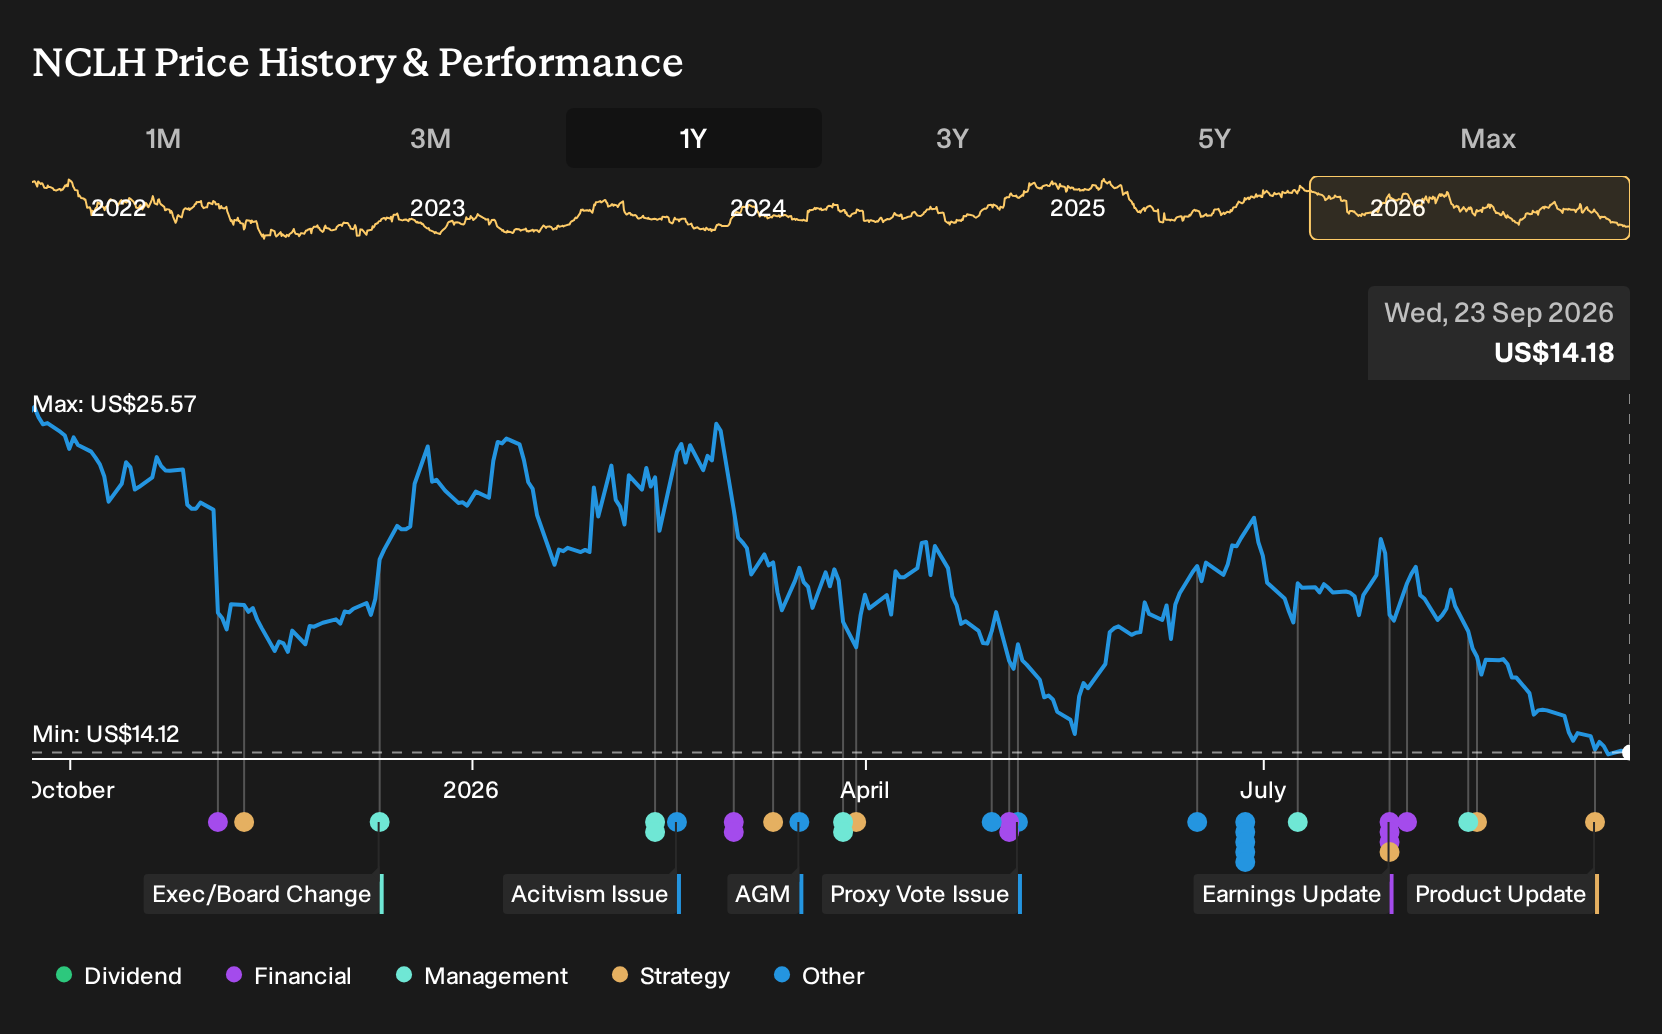
- The focus now shifts to how Norwegian Cruise Line Holdings' investment narrative could be shaped by Norwegian Aura's high-profile Whitney Houston production.
Scan beyond Norwegian Cruise Line Holdings and compare its experience-led push with a curated 16 high quality undiscovered gems that could be setting up their own breakout moments in travel and leisure.
Norwegian Cruise Line Holdings Investment Narrative Recap
To own Norwegian Cruise Line Holdings, you need to believe that experience driven capacity additions can translate into steadier pricing, solid occupancy and healthy onboard spend, while the balance sheet gradually becomes less of a constraint. The latest Norwegian Aura entertainment reveal fits this thesis, but it is more of a brand and revenue mix story than a near term earnings driver.
The key short term swing factor still sits with cash generation versus interest costs and upcoming maturities, not a single ship’s theater lineup. High leverage and euro debt exposure remain the biggest pressure points. If financing costs stay heavy or demand softens, that capital structure risk does not ease quickly.
The Norwegian Aura entertainment program, headlined by the Whitney Houston celebration and several ship exclusive shows, sits squarely in the company’s broader push into differentiated experiences, similar to what it is doing at Great Stirrup Cay. Both aim to deepen guest engagement and support onboard spending across age groups rather than just relying on ticket prices.
For catalysts, that matters because experience driven offerings can support revenue quality on new, more efficient vessels. This ties directly into the earnings growth analysts are modeling. The flip side is execution risk. If high profile productions and destination upgrades do not translate into stronger onboard economics, Norwegian Cruise Line Holdings still has the same leverage and FX exposure to work through, with less support from its premium positioning story.
What The Norwegian Cruise Line Holdings Forecasts Assume
Norwegian Cruise Line Holdings is being valued today on a very specific earnings and revenue story that stretches out to 2029. Analysts are modeling 4.5% yearly revenue growth over the next three years, which implies a steady rather than explosive top line climb as new experiences such as Norwegian Aura's entertainment program and private destination upgrades roll through the fleet.
On profitability, the consensus view builds in only a small margin lift, from 7.5% earnings today to 7.7% in about three years. That is a narrow shift, but on a multibillion dollar revenue base even a modest change in profitability can matter for cash generation when the balance sheet is carrying meaningful debt.
The earnings bridge is more visible. Forecasts point to profit rising from US$760.8 million today to US$895.5 million by 2029, which is an increase of roughly US$135 million. That step up is what analysts are tying to experience-led capacity, cost discipline and incremental onboard spend rather than just ticket price moves.
Valuation assumptions layer on top of that income outlook. To line up with the current consensus price targets, the stock would need to trade on a P/E multiple of 15.5x those 2029 earnings compared with about 9.4x today, while the broader US Hospitality group is on 22.3x. That gap between the sector multiple and where Norwegian Cruise Line Holdings might trade is one way readers can think about how much execution risk and balance sheet weight the market is still pricing in.
Norwegian Cruise Line Holdings' narrative projects US$11.6b revenue and US$895.5 million earnings by 2029. This implies 4.5% yearly revenue growth and an earnings increase of roughly US$135 million from US$760.8 million today.
Uncover how Norwegian Cruise Line Holdings' fair value indicates a 46% potential upside to its current price before the discount to expectations starts to close.
Exploring Other Perspectives
One alternate view on Norwegian Cruise Line Holdings leans hard into environmental risk. Under that lens, rising carbon costs and tighter port rules keep earnings capped near US$793.0 million on about US$11.5b revenue by 2029, compared with consensus US$895.5 million. Those lower forecasts came before the Norwegian Aura entertainment reveal, so you may see estimates shift as analysts revisit their assumptions.
Explore 4 other Norwegian Cruise Line Holdings fair value estimates, including one that suggests as much as 70% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Norwegian Cruise Line Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Norwegian Cruise Line Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Norwegian Cruise Line Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Norwegian Cruise Line Holdings?
If the Norwegian Cruise Line Holdings story has you thinking about what else might be mispriced or underappreciated, the Simply Wall St Screener can help you cast a wider net without losing focus on quality.
- If you want potential bargains with quality fundamentals, start with a curated set of 30 high quality undervalued stocks that already combine stronger balance sheets with attractive valuations.
- If resilience matters more to you than excitement, filter for defensiveness first and work from there using the 31 resilient stocks with low risk scores that aim to keep business risk contained.
- If financial strength is your non negotiable anchor, begin your research with a list of solid balance sheet and fundamentals (23 results) so you are looking at companies that already have sturdier foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com