


Merck KGaA has delivered a solid 28.7% return over the past year, which puts fresh attention on whether the current share price lines up with what the business earns. With the stock around €133.95 at the last close, the real question for you is how that move stacks up against the company’s earnings power.
- The 28.7% gain over the past 12 months puts recent buyers in profit. This raises the stakes on whether earnings can support sentiment from here.
- The agreed acquisition of Bio-Techne, expected to close between late 2026 and early 2027, may reshape Merck KGaA’s life science earnings profile, including future margins and cash flow mix once the combined operation is in place.
- There is a second opinion on Merck KGaA worth weighing. See what analysts think Merck KGaA's shares could be worth.
The issue now is whether Merck KGaA’s current price is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing Merck KGaA against other opportunities where earnings are central to the story, a focused stock screen built around 177 high quality undervalued stocks can be a useful next step for research.
Does Merck KGaA Look Undervalued on Earnings?
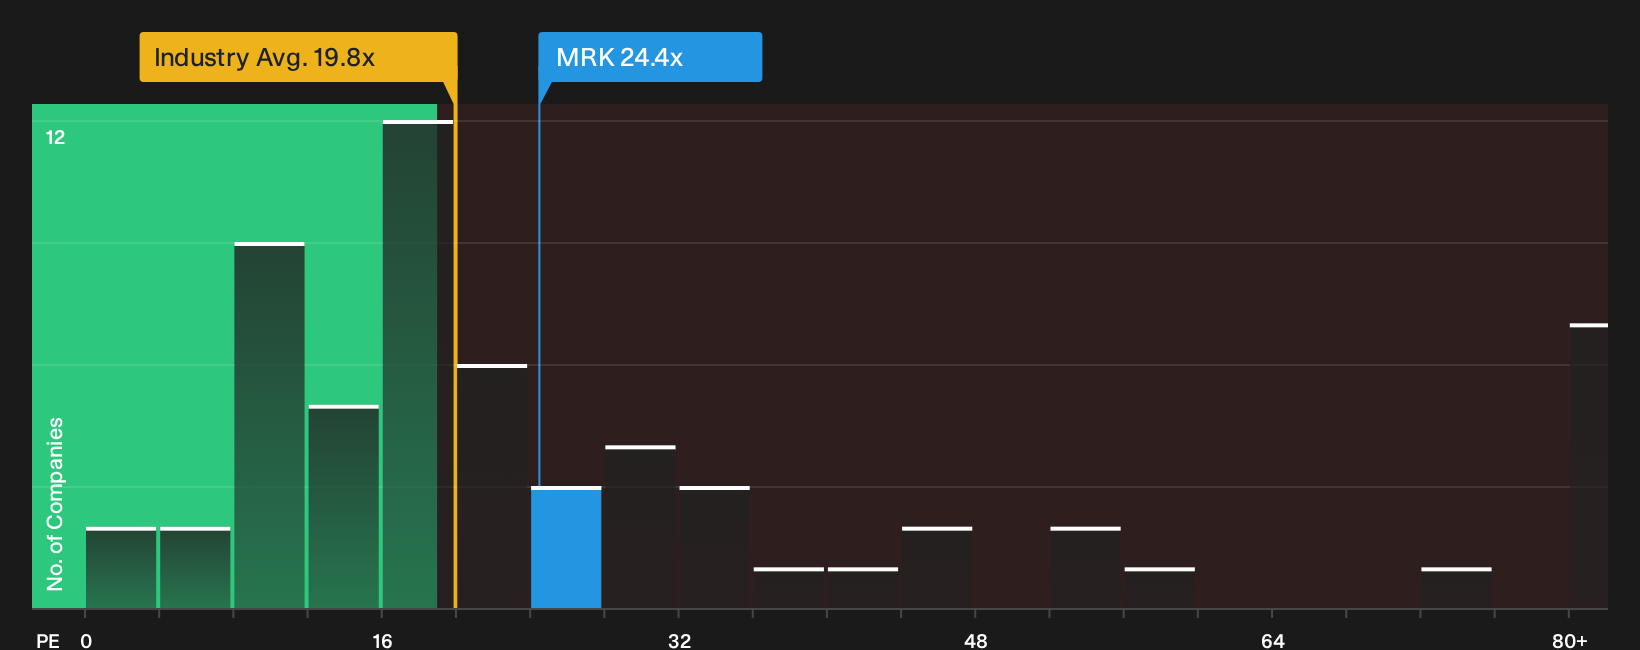
The P/E ratio is a useful measure for Merck KGaA because earnings remain a key yardstick for large, diversified pharmaceutical groups. At roughly 24.6x earnings, the stock trades below the Pharmaceuticals industry average of about 22.3x and also below the peer group on roughly 32.9x, which points to a discount relative to many directly comparable businesses.
The Fair Ratio, which reflects what investors might typically pay given Merck KGaA’s sector, size and risk profile, sits above the current P/E, so the shares screen as undervalued on this framework. Because the agreed Bio-Techne deal focuses attention on the life science earnings stream, the lower P/E suggests the market is still cautious about how that acquisition and the broader portfolio will translate into future profit power. Explore the numbers behind Merck KGaA's P/E valuation.
The Merck KGaA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Merck KGaA pick up where the P/E and Fair Ratio leave off by setting out what kind of future for Merck KGaA's growth, margins and earnings would need to play out for the share price to look materially higher or lower than today. Rather than a single valuation output, these stories describe the conditions that figure relies on, so you can see what needs to happen and judge over time whether reality lines up.
One of the top community narratives on Merck KGaA: 13% undervalued
"Digitalization efforts, both in portfolio offerings and process improvements, position the company to capture incremental market share and drive productivity…"
Discover why this Narrative puts Merck KGaA at 13% undervalued.
The Merck KGaA share price is only one piece of the decision
Valuation tells you what the market pays today, but the research case for Merck KGaA also hinges on how professionals expect its earnings profile to look a few years from now. Explore where analysts expect Merck KGaA to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com