


Global bond markets are under pressure and UK gilt yields are hovering near multi decade highs, which makes dependable earnings growth feel more valuable than ever. When borrowing costs bite, investors often look harder at British businesses that analysts expect to grow their profits while still keeping balance sheets in reasonable shape. This article highlights three stocks from this high growth list that fit that profile.
The three stocks highlighted below are only a sample from this high growth theme, with the full screen surfacing 28 more companies that analysts expect to deliver similar earnings momentum while keeping their finances in check. To see the full set of candidates and quickly identify which ones best fit your own criteria, head straight into the Healthy high growth potential screener.
ActiveOps (AIM:AOM)
Overview: ActiveOps runs cloud-based ControliQ, CaseworkiQ and WorkiQ software that helps large service organisations improve decision making, productivity and workforce performance.
Operations: ActiveOps generates about £38 million from SaaS subscriptions and £7 million from training and implementation services across the UK, USA, Canada, Australia and South Africa.
Market Cap: £147.2 million
ActiveOps fits the Healthy high growth potential theme because its SaaS tools directly target productivity and efficiency gains that analysts link to future earnings improvements.
"ActiveOps is well positioned to benefit from the growing demand for AI-driven operational solutions. This demand is expected by some analysts to support revenue growth as organizations seek better decision intelligence tools."
The real swing factor for investors is how one less visible pressure on future margins and cash generation ultimately plays out.
That pressure point is exactly what the full narrative for ActiveOps unpacks, separating margin risk from the growth story analysts see building.

RentGuarantor Holdings (AIM:RGG)
Overview: RentGuarantor Holdings runs an online rent guarantee platform in the UK that backs long term private tenancies across varied tenant groups.
Operations: RentGuarantor Holdings generates about £4.8 million from its Internet Information Providers segment, all from customers in the United Kingdom.
Market Cap: £145.8 million
RentGuarantor Holdings fits the Healthy high growth potential theme because analysts expect earnings and revenue to rise quickly as its rent guarantee platform scales with new agreements. However, the outcome for shareholders still depends on how one unresolved pressure around funding costs and leverage ultimately affects that growth path.
Those funding questions sit at the heart of the RentGuarantor Holdings financial health report, where the balance between leverage and earnings momentum becomes much clearer.
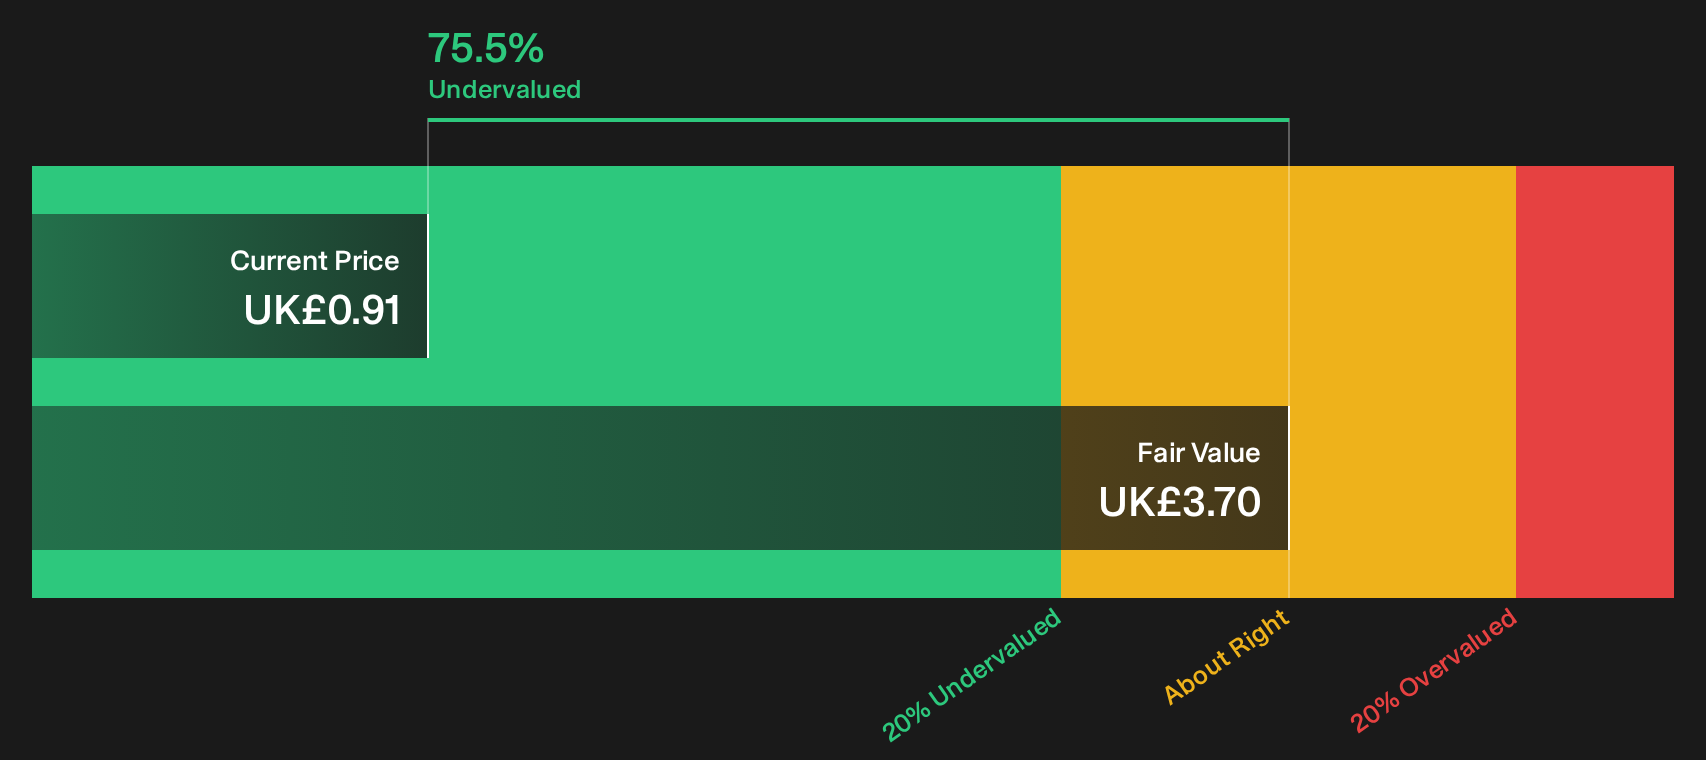
Metals Exploration (AIM:MTL)
Overview: Metals Exploration develops and operates gold and base metal mining projects, with its fully owned Runruno gold project as the flagship asset.
Operations: Metals Exploration generates about $208 million from gold and other precious metals, all sourced from operations in the Philippines.
Market Cap: £511 million
Metals Exploration aligns closely with the Healthy high growth potential theme because analysts expect earnings to rise faster than the wider UK market, driven largely by the Runruno gold project. Forecast revenue expansion and strong projected returns on equity make the stock relevant for growth focused investors, depending on how one unseen pressure on future profitability eventually plays out.
That profitability tension is exactly where the detailed analysis report for Metals Exploration starts to show how Metals Exploration’s growth story and future returns could be decoupling.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Markets reprice quickly, and the most interesting stories rarely stay under the radar for long. Scan these focused lists while it matters and consider opportunities early.
- Target reliable payers by reviewing 1 dividend fortresses built to spotlight companies combining meaningful yields with balance sheets that look prepared for tougher conditions.
- Chase early momentum across digital assets by scanning 20 cryptocurrency and blockchain stocks featuring businesses tied to blockchain infrastructure before wider attention changes demand.
- Hunt operational resilience with the 4 resilient stocks with low risk scores curated to surface companies where balance sheets and risk scores point to durability when conditions turn challenging.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com