


Woodward’s manufacturing reset puts Santa Clarita in the spotlight
Woodward (WWD) has put a major piece of its aerospace footprint in motion, outlining plans to shift production from Santa Clarita, California, to a new Spartanburg, South Carolina, facility.
The reorganization centers on moving military fixed wing and rotorcraft flight control actuation work to the upcoming Spartanburg campus, while selling certain legacy product lines and the Santa Clarita site itself.
Woodward’s share price has pulled back over the past three months, with a 90-day share price return of 24.42% in the red, even as news flow has focused on the manufacturing reset, a fresh quarterly dividend declaration and a high profile investor conference appearance. At the same time, longer term total shareholder returns remain strong, with a 34.22% gain over one year and a 3-year total shareholder return of about 2.6x. This suggests that recent weakness is more of a cool down in momentum than a reversal of the broader story.
Scan beyond Woodward’s footprint reset and explore other capital goods players that are reshaping their operations with our curated list of solid balance sheet and fundamentals (23 results) for a more complete watchlist.
Woodward is coming off a sharp pullback after a long run and a fresh manufacturing overhaul. Is most of the easy upside now behind the stock, or does today’s price still leave meaningful headroom?
Most Popular Narrative: 27% Undervalued
On the most followed view of Woodward, a fair value of $444.55 sits well above the last close at $326.23, which puts recent share weakness in a different light for anyone focused on long run cash flows.
The global push for decarbonization and rising energy efficiency standards is associated with demand for high-tech propulsion, actuation, and energy management systems in both aviation and industrial markets, supporting Woodward's revenue growth and expanding its addressable market over the coming years.
Increasing digitalization and automation in industrial and aerospace manufacturing is associated with demand for Woodward's advanced motion control and actuator solutions, which, supported by its ongoing investments in automation and proprietary technologies, is viewed as a potential driver of net margins and long-term earnings power.
See why 11 investors see Woodward as 27% undervalued.
Result: Fair Value of $444.55 (UNDERVALUED)
Still, concentrated capital spending on new facilities, and any stumble in electrification programs, could quickly challenge the bullish Woodward narrative investors are leaning on.
Find out about the key risks to this Woodward narrative.
Another View on Woodward’s current price tag
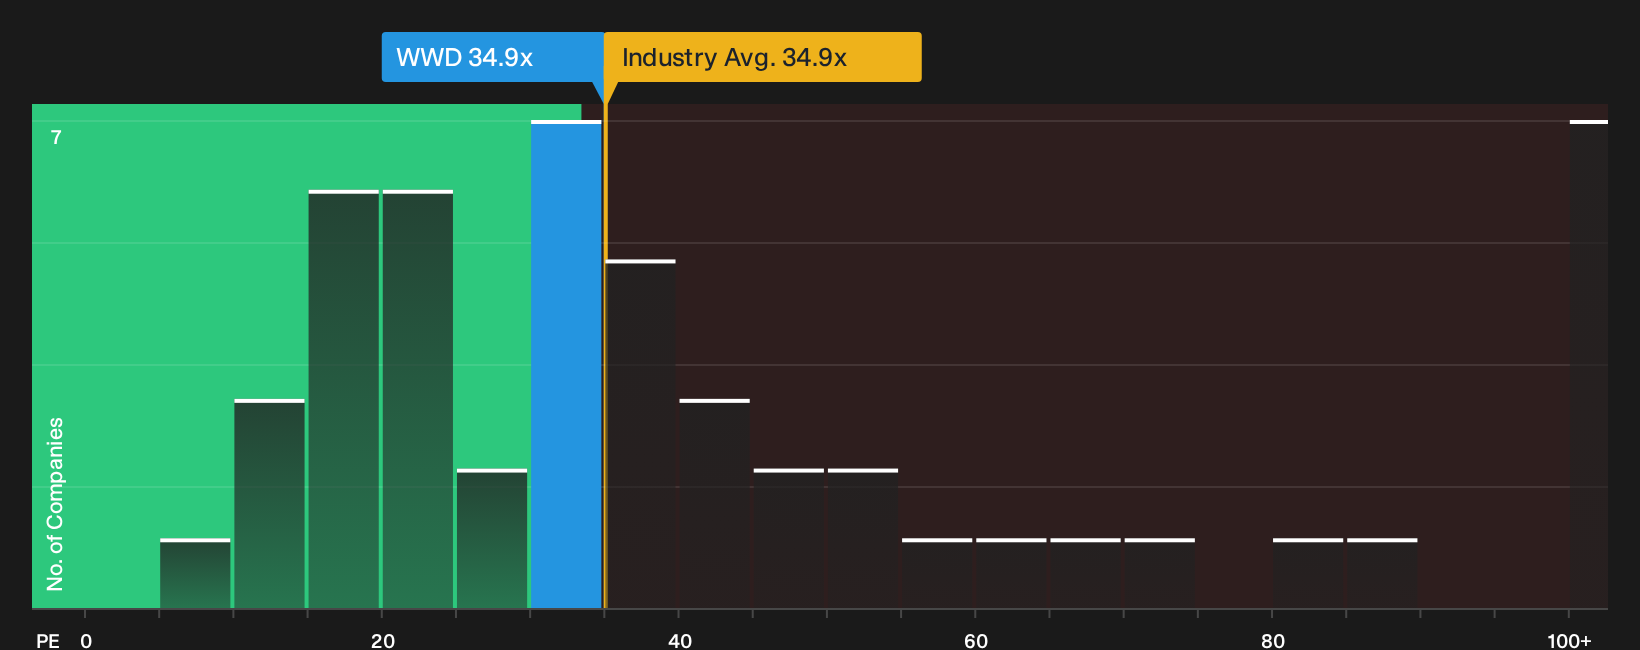
That 27% upside case leans on long run cash flows. A simpler lens looks at Woodward’s P/E of 34.9x, which is above its own fair ratio of 27.2x and in line with the US Aerospace & Defense average at 34.9x. If sentiment cools, could that premium narrow faster than the story changes?
For a closer look at how this P/E gap could matter in practice, including where the fair ratio might pull the valuation over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Woodward story points to optimism, so move quickly, test the numbers yourself and then weigh up the 4 key rewards.
Looking for more Woodward-style investment ideas?
If Woodward has sharpened your focus on quality, now is the moment to broaden your radar and line up a few more candidates that could deserve closer attention.
- Spot potential mispricings by scanning a curated 30 high quality undervalued stocks that focuses on companies with fundamentals that may not be fully reflected in current market prices.
- Prioritize staying power and financial resilience by working through a 31 resilient stocks with low risk scores designed to highlight businesses with more robust risk profiles.
- Get ahead of the crowd by reviewing a 16 high quality undiscovered gems that flags lesser known stocks backed by stronger underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com