


- Diodes Incorporated recently introduced automotive-compliant field-plated Super Barrier Rectifier products, including 2A, 3A, and 8A devices, targeting DC-DC converters, reverse-polarity protection, battery charging, LED lighting, and transmission control systems with ultra-low forward voltage and low reverse leakage.
- The SBRFP family uses a MOS-based process to deliver low conduction losses, high avalanche energy ratings up to 145mJ, and wide temperature tolerance. This directly reflects Diodes’ push into demanding automotive power electronics where efficiency and robustness are key buying criteria.
- We will now look at how Diodes’ higher avalanche-capable automotive rectifiers might influence the existing investment narrative around margin potential.
Diodes Investment Narrative Recap
To own Diodes, you need to believe the product mix keeps tilting toward higher value automotive, industrial, and compute designs, while the legacy consumer exposure and pricing pressure gradually matter less. The new SBRFP rectifiers speak directly to that idea, because they extend Diodes’ reach in demanding in-vehicle power designs that place a premium on efficiency and thermal behavior.
The major near term swing factor is still how quickly higher margin segments scale relative to any slowdown or pricing compression in consumer driven discretes, especially with earnings having declined over the past 5 years and inventory levels already flagged as a concern. This SBRFP launch supports the long term story but does not remove risks around high Asia exposure, execution on in house manufacturing, or potential inventory write downs if end demand softens.
The rectifier announcement is itself the key recent development. Automotive compliant, field plated SBRFP devices with very low forward voltage, low leakage, and much higher avalanche capability give Diodes more to present to power engineers designing DC DC converters, protection circuits, and LED lighting inside vehicles that must withstand demanding transients and heat.
This type of offering aligns with the broader catalysts already in focus for Diodes, including rising semiconductor content in electrified cars and a push toward more efficient power management. The SBRFP family targets exactly those use cases, so execution around design wins, qualification in customer platforms, and volume ramp will matter for how much this contributes to mix improvement relative to the existing risks in consumer exposure and capacity investments.
Diodes' narrative projects US$2.0b revenue and US$172.6 million earnings by 2029. Analysts assume 11.4% yearly revenue growth and an earnings increase of about US$106.5 million from US$66.1 million today.
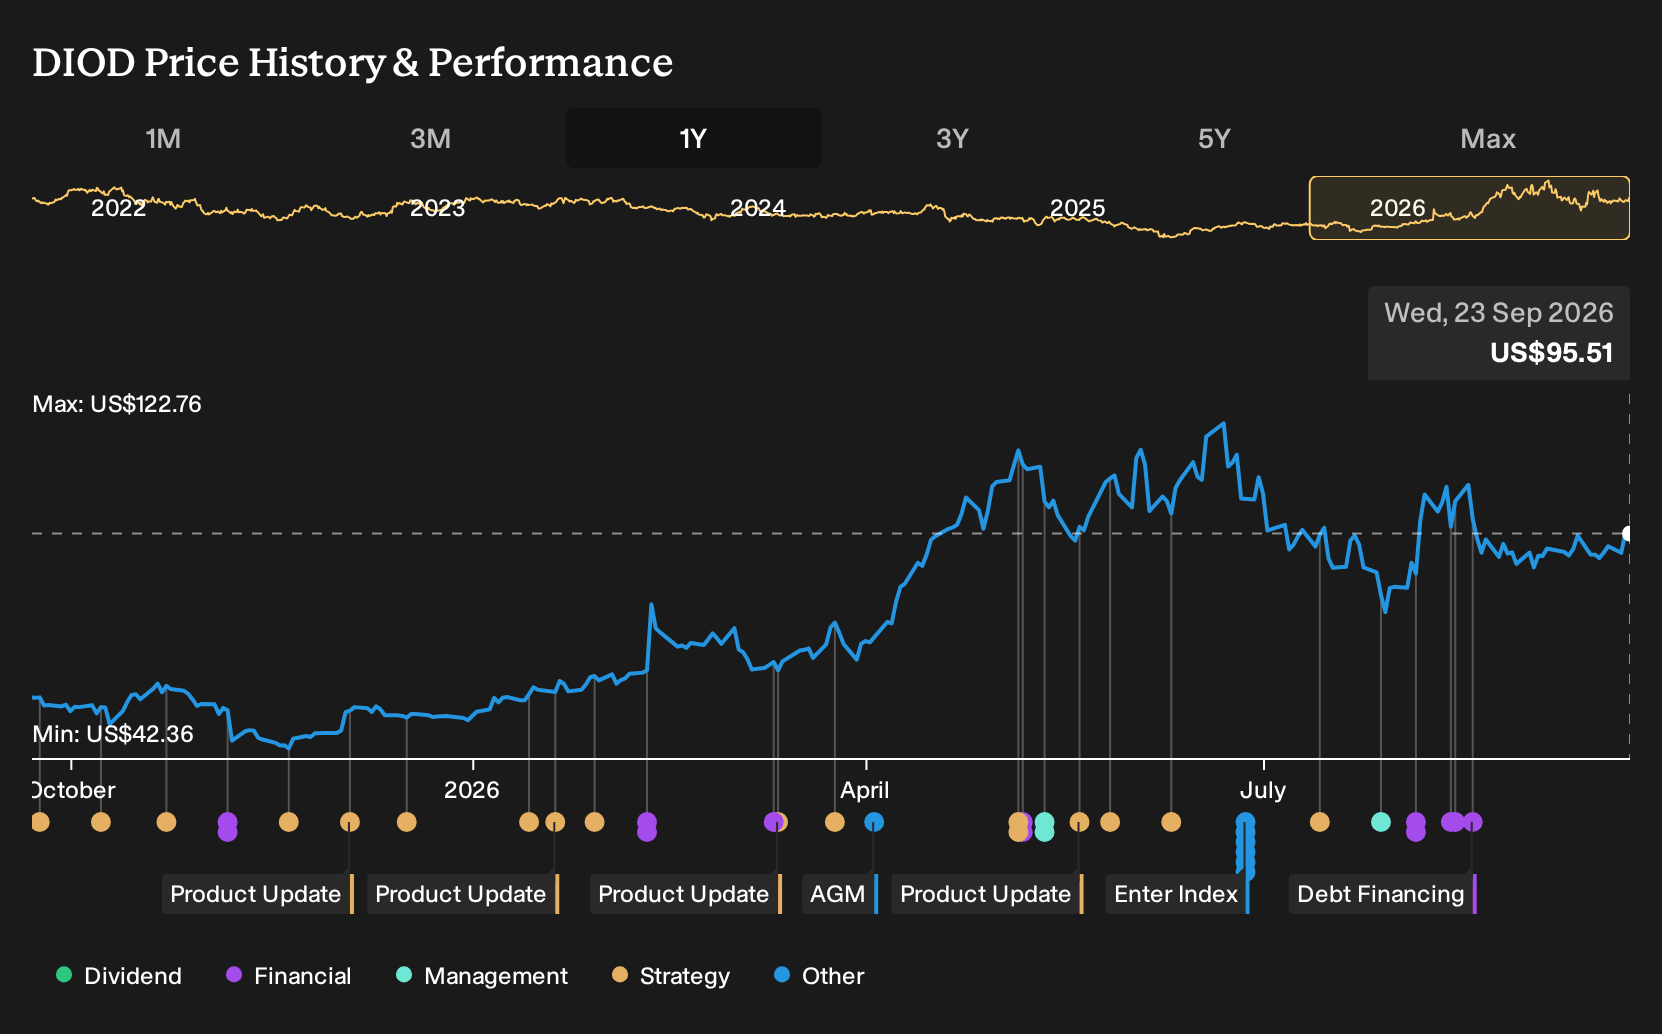
Uncover why Diodes' fair value indicates a 21% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One contrasting angle from the lowest Diodes analysts focuses on customer concentration risk. These analysts already penciled in about US$2.2b of revenue and US$188.9 million of earnings by 2029, yet still saw a 33.9% downside. That indicates opinions vary widely, and this SBRFP news could eventually reshape those expectations.
Explore 3 other Diodes fair value estimates, including one that suggests as much as 59% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Diodes research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Diodes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Diodes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Diodes?
If the Diodes story has you comparing trade offs between growth potential, balance sheet strength, and risk, it can help to line it up against a wider field of opportunities using the Simply Wall St Screener.
- For investors who want potential upside without ignoring business quality, scan a curated set of 16 high quality undiscovered gems that might not yet be widely followed.
- If capital protection and steadier profiles matter more to you right now, sort through a 31 resilient stocks with low risk scores that focuses on companies with more resilient characteristics.
- When you care most about solid finances backing any growth story, filter a list of solid balance sheet and fundamentals (23 results) to see which businesses pair cash generation with stronger balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com