


- ON Semiconductor recently launched its Embedded Power Platform and deepened partnerships with Subaru and Valens to support next generation automotive, AI infrastructure and integrated power and imaging solutions.
- The shift toward wafer level power integration and early access programs with key automakers signals a push to integrate ON Semiconductor technology directly into future vehicle architectures and data center designs.
- We will now look at how ON Semiconductor's Embedded Power Platform launch could reshape the existing investment narrative around power leadership.
Scan for other potential beneficiaries of the same AI infrastructure and electrification trend by reviewing our hand picked list of 85 AI infrastructure stocks alongside ON Semiconductor.
ON Semiconductor Investment Narrative Recap
To own ON Semiconductor, you need to believe its push into high value power and sensing for EVs, industrial and AI data centers can offset pressure in more cyclical end markets and the wind down of legacy products. The Embedded Power Platform fits that thesis, but the near term story still hinges on demand recovery and better fab utilization.
The key short term swing factor remains how quickly automotive and AI power orders can fill underused capacity and support margins after recent portfolio exits. The biggest risk stays the same: weakness in EV adoption outside China or tighter competition in SiC, imaging and power devices could keep utilization and profitability under strain.
The Subaru engagement around ON Semiconductor's Embedded Power Platform looks most relevant for the current catalyst debate. It directly ties next generation power integration to a concrete OEM evaluating future electrified architectures. That gives investors a clearer operational link between EPP and potential content per vehicle rather than a purely technology driven announcement.
For the thesis, this kind of early access program matters because it tests whether wafer level integration can reduce complexity and system cost enough to drive wider adoption. Execution risk is real. ON still needs to turn engineering samples and simulations into qualified platforms and repeatable design wins while competing against other power suppliers chasing the same electrification and AI infrastructure budgets.
ON Semiconductor Forecasts Tied To Embedded Power Platform
ON Semiconductor's narrative projects US$9.0b revenue and US$2.5b earnings by 2029. This assumes 13.0% yearly revenue growth and an earnings increase of about US$1.9b from US$630.2m today.
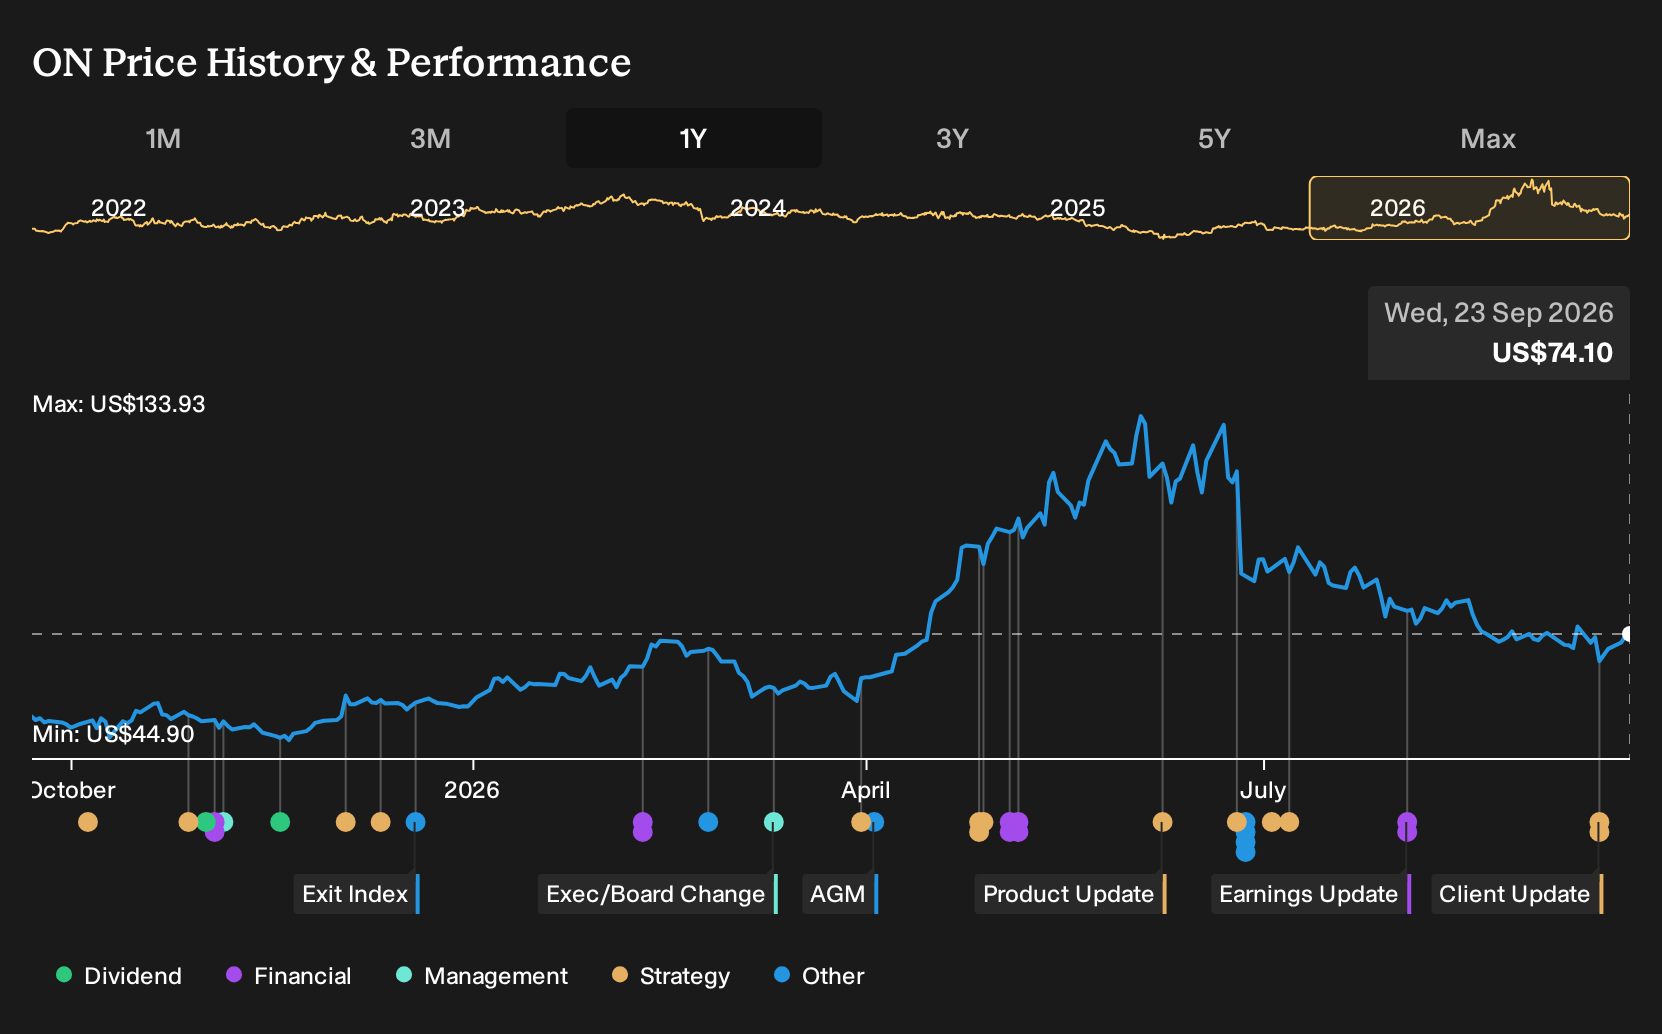
Uncover why ON Semiconductor's fair value indicates a 45% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts treat rapid manufacturing recovery as the real catalyst for ON Semiconductor, not just EPP. Before this news, the bullish camp was penciling in about US$9.9b of revenue and US$2.9b of earnings by 2029. That is a far more upbeat story than consensus and it may shift again after this launch.
Explore 3 other ON Semiconductor fair value estimates, including one that suggests as much as 90% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and perspective.
- A great starting point for your ON Semiconductor research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ON Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ON Semiconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond ON Semiconductor?
If the ON Semiconductor story has sharpened your thinking about power, AI and electrification, it can be useful to line it up against other stocks with very different drivers. A good screener helps you compare quality, risk and income potential quickly instead of working through tickers one by one.
- For investors who care most about quality at a sensible entry point, compare ON Semiconductor with a 30 high quality undervalued stocks that currently combine solid fundamentals with pricing that may not fully reflect them.
- If capital preservation sits high on your priority list, balance ON Semiconductor's exposure with a 31 resilient stocks with low risk scores that have more resilient financial and risk profiles.
- When you want sturdier balance sheets alongside ON Semiconductor's more cyclical exposure, round out your watchlist using a list of solid balance sheet and fundamentals (23 results) that can help support portfolio stability through different conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com