


Louisiana-Pacific (LPX) has come under pressure after reports flagged a Zacks Rank of #5, Strong Sell, along with forecasts for a sharp earnings per share decline in the upcoming quarter.
Recent trading has reflected that caution. Louisiana-Pacific's share price fell 2.56% in the latest session and is down 8.35% over the past 30 days and 19.54% over the last 90 days, while the 1-year total shareholder return has declined 19.27%. At the same time, the 3-year total shareholder return of 23.00% and 5-year total shareholder return of 15.64% point to a longer history that investors are weighing against the current earnings concerns.
Compare Louisiana-Pacific's recent weakness against a curated group of construction and materials peers by scanning our list of solid balance sheet and fundamentals (23 results) that may be better positioned to handle earnings pressure.
After a near 20% 1-year slide and fresh earnings worries, Louisiana-Pacific now sits at a very different entry point than it did a few quarters ago. Is this the moment to step in, or does patience still pay?
Most Popular Narrative: 28% Undervalued
Analysts following Louisiana-Pacific see a gap between the recent $66.28 share price and their implied fair value of $91.50, built on a detailed view of siding demand, new products, and margin potential over time.
Accelerated adoption of LP's SmartSide and ExpertFinish trim and siding products, driven by increasing demand for sustainable, labor-saving, and durable materials across new construction, repair/remodel, and manufactured housing, should support above-market volume growth and price realization, lifting long-term revenue and gross margin.
See why 12 investors see Louisiana-Pacific as 28% undervalued.
Result: Fair Value of $91.50 (UNDERVALUED)
Still, Louisiana-Pacific faces real pressure if weak housing activity and softer repair and remodel demand linger, or if low OSB pricing continues to strain profitability.
Find out about the key risks to this Louisiana-Pacific narrative.
Another View On Louisiana-Pacific Valuation
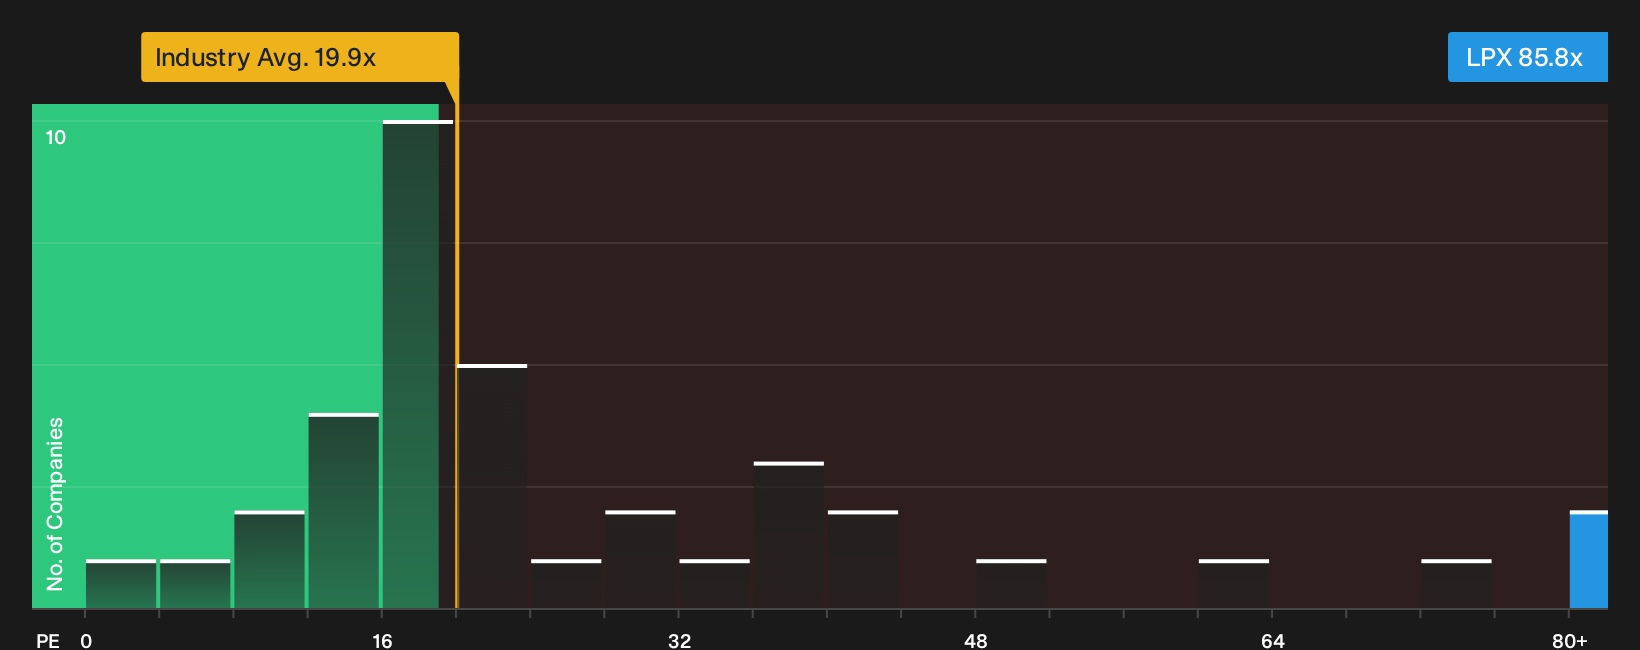
Analysts see Louisiana-Pacific as undervalued against their $91.50 fair value, but the current P/E ratio of 85.8x tells a different story. That multiple is much richer than the US Building industry at 19.9x, the peer group at 23.3x, and even the fair ratio of 79.6x. This suggests the market could move toward a lower earnings multiple and introduce valuation risk if expectations slip.
For a clearer sense of how the current price lines up against earnings power, and how much room there might be for that P/E to adjust, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed sentiment around Louisiana-Pacific after recent price moves and valuation debate, it may be useful to move quickly to stress test the story yourself and weigh both sides. The quickest way to see how that balance of concern and optimism stacks up is to review the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Louisiana-Pacific?
If Louisiana-Pacific has you rethinking your watchlist, it may be worth widening the lens. Exploring additional ideas can help balance company specific risk and refine your next move.
- Explore potential opportunities by reviewing 16 high quality undiscovered gems that pair strong fundamentals with businesses the market may not be fully focused on yet.
- Prioritise durability by scanning 31 resilient stocks with low risk scores that score well on financial strength and business stability when conditions turn difficult.
- Look for value by checking 30 high quality undervalued stocks where solid quality meets prices that appear attractive on key fundamental metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com