


Leidos Holdings has seen its share price under pressure recently, which puts a fresh spotlight on whether the current valuation is still supported by the company’s earnings power. With the stock resetting lower after a weak run this year, the key issue for you is how well its profit profile lines up with the price on screen.
- Over the past 3 years the stock has gained 38.4%, which makes the question of what you are now paying for each dollar of earnings much more important than a simple look at the recent pullback.
- New multi year work with the U.S. Army’s ARTEMIS ISR program and the U.S. Navy’s global network contract can support expectations for more stable revenue and potentially steadier earnings, which feeds directly into how investors think about a fair earnings multiple.
- The analysts covering Leidos Holdings have run their own numbers. See what analysts think Leidos Holdings's shares could be worth.
The issue now is whether Leidos Holdings' current share price is justified by its earnings when judged against the Fair Ratio benchmark.
If you are weighing Leidos Holdings against other options that also lean on earnings power, a focused stock screen built around 30 high quality undervalued stocks can be a practical next step in your research.
Is Leidos Holdings Still Cheap on Earnings?
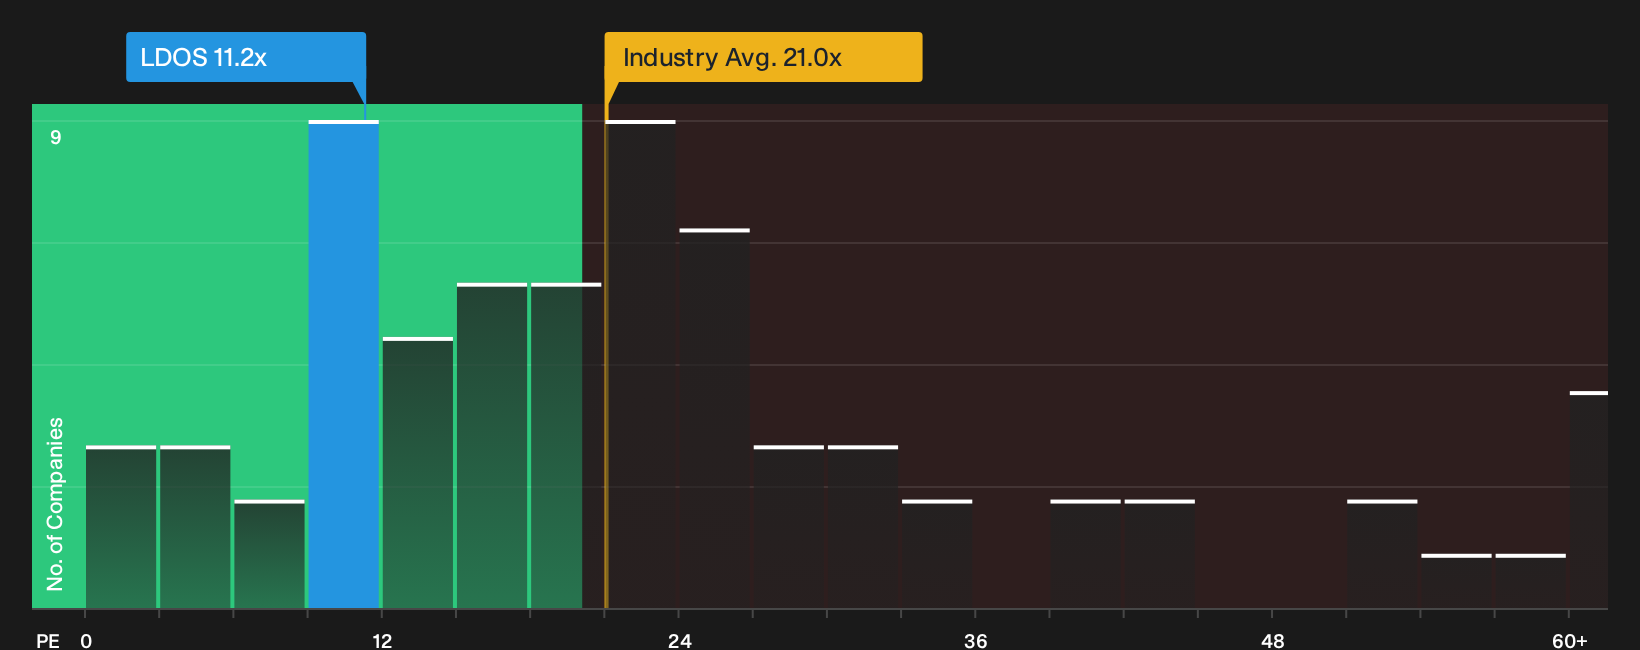
The P/E ratio works well for Leidos Holdings because earnings are a central way investors frame the value of its long term contracts with U.S. defense customers. On this measure the stock trades on roughly 11.2x earnings, which is well below the Professional Services industry average of about 21.0x and the broader peer group at roughly 28.3x.
Recent contract wins with the U.S. Army’s ARTEMIS ISR mission and the Navy’s global network work could help some investors feel more confident about the durability of Leidos Holdings’ profit stream. However, the current multiple still sits clearly below the level a Fair Ratio model implies for this business. For anyone comparing this to other defense oriented service providers, that gap signals the market is pricing Leidos Holdings at a discount to what its earnings profile might justify on this framework. Explore the numbers behind Leidos Holdings's P/E valuation.
The Leidos Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Leidos Holdings valuation puzzle leaves off and spell out which paths for revenue, margins and earnings would need to hold for the stock to look meaningfully higher or lower than today’s price. Each scenario sets out the assumptions behind its own view of fair value in plain terms, so you can track those expectations against Leidos Holdings' actual results on the Community page.
One of the top community narratives on Leidos Holdings: 21% undervalued
"Accelerating customer demand for digital modernization, AI powered solutions, and autonomous systems in defense, healthcare, and intelligence plays to Leidos' strengths..."
Discover why this Narrative puts Leidos Holdings at 21% undervalued.
One more factor on Leidos Holdings that could change how you read the valuation
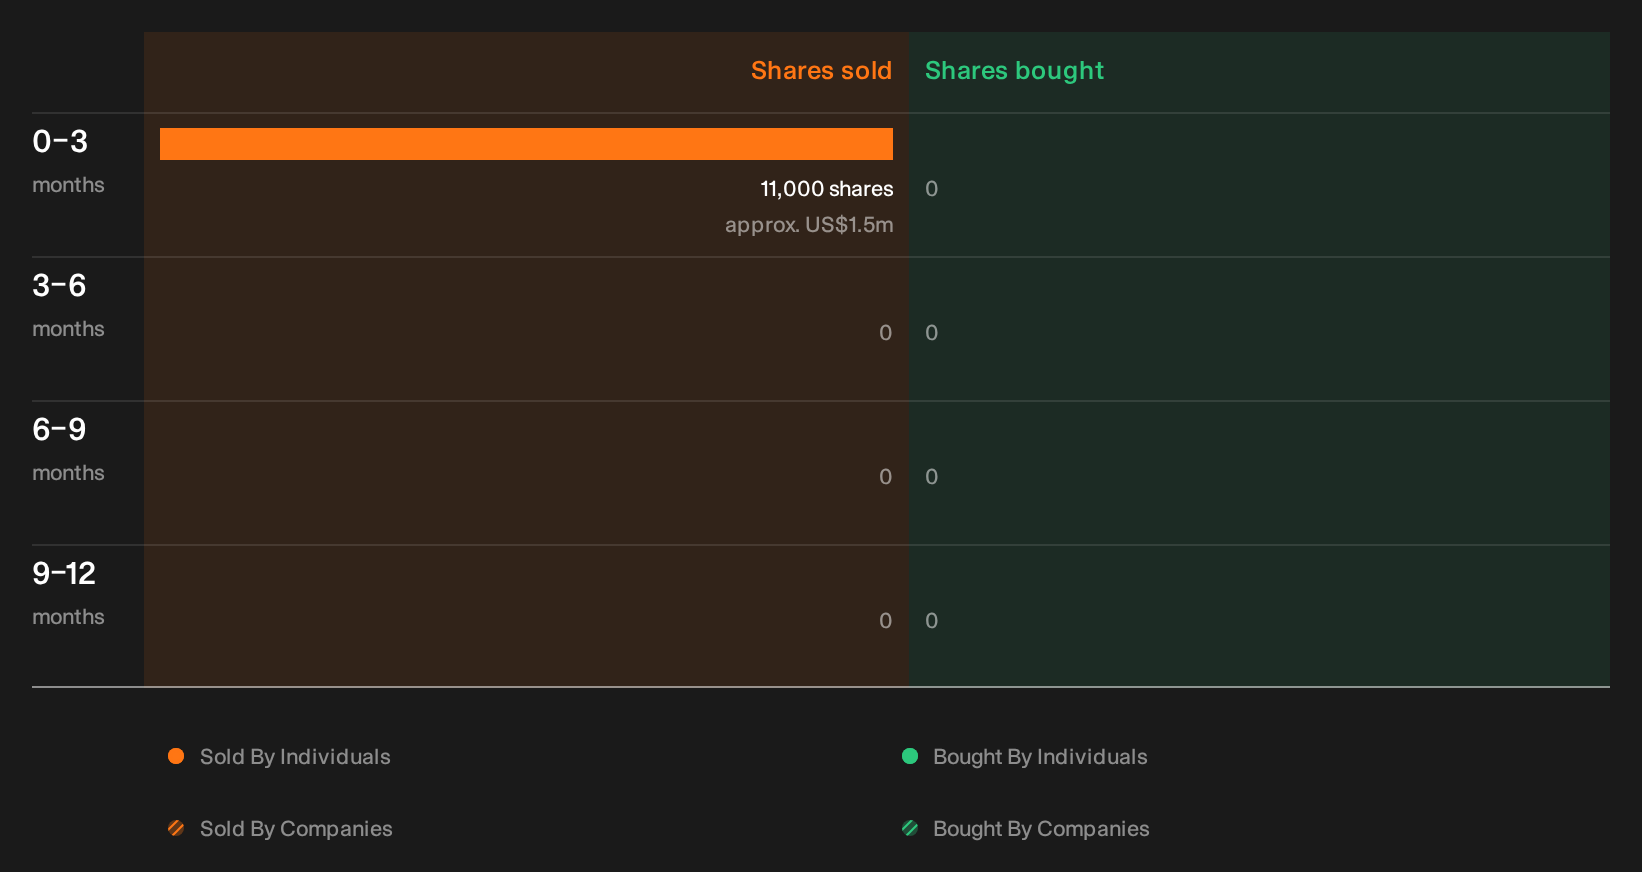
There is one more piece of the Leidos Holdings puzzle that the numbers alone do not explain. This is the recent share dealing by company insiders and what it might signal for you. See the recent insider selling flagged for Leidos Holdings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com