


Assured Guaranty has given long term holders a solid ride over the past few years, yet recent weakness has put fresh attention on whether its current share price still lines up with what the business earns. With the stock now some distance below its earlier highs, the key issue is how much of the past earnings power and future profit potential is already baked into today's valuation.
- Over the past 5 years, Assured Guaranty has delivered a total return of 59.2%, which puts real weight on the question of whether earnings can support the value that has built up.
- The group’s model of insuring credit risk and managing its own balance sheet means profitability depends heavily on underwriting discipline and investment results, which can influence how durable its earnings base looks at today’s price.
- The analysts covering Assured Guaranty have run their own numbers. See what analysts think Assured Guaranty's shares could be worth.
The stock's next move may depend on whether the recent share price now fairly reflects what Assured Guaranty earns on a sustained basis.
To compare Assured Guaranty with other potential ideas using a similar earnings perspective, you could start with a focused screen of 30 high quality undervalued stocks.
Is Assured Guaranty Still Cheap on Earnings?
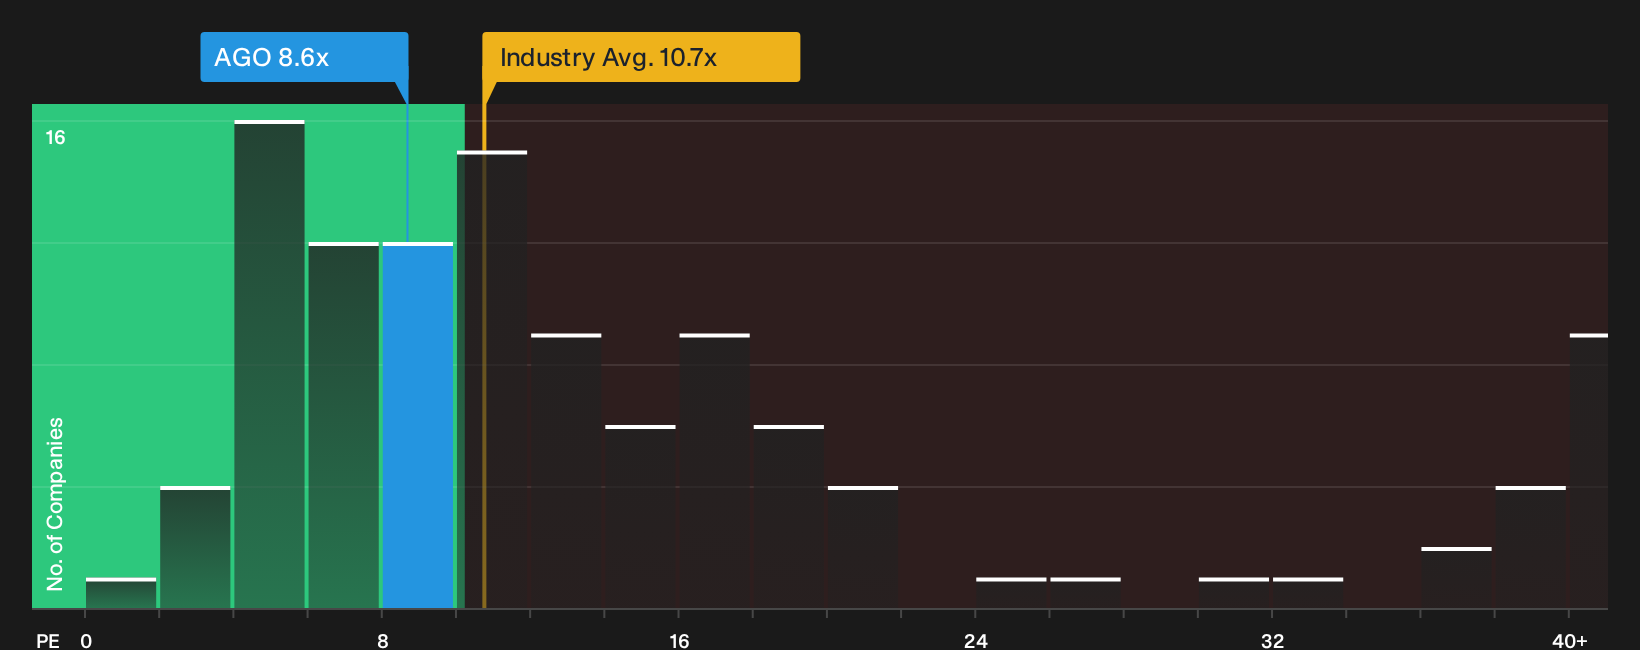
P/E is often the cleanest starting lens for Assured Guaranty because earnings quality and consistency matter so much for a financial stock. On this measure, the shares trade on a P/E of 8.6x, compared with an insurance industry average of about 10.7x and a peer group average near 11.8x. That puts the current valuation below what many similar businesses command in the market.
The model driven fair P/E, which looks at Assured Guaranty’s own profitability profile, balance sheet intensity and risk, sits above where the stock currently trades. So the present 8.6x multiple points to the market applying a lower earnings tag than this framework would expect for the company’s fundamentals. For investors comparing options in the insurance space, the key question is whether that discount reflects real business risks or leaves room for a re rating on stronger or more stable earnings over time. Explore the numbers behind Assured Guaranty's P/E valuation.
The Assured Guaranty Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Assured Guaranty pick up where the P/E comparison leaves off and spell out which combinations of future earnings, margin profile and balance sheet outcomes would need to hold for the stock to be worth significantly more or less than today’s level. Instead of stopping at one valuation output, Narratives describe the set of business assumptions that number rests on so you can watch how Assured Guaranty's actual results line up against that picture over time.
One of the top community narratives on Assured Guaranty: 26% undervalued
"The company is described as a high quality, cash generative franchise, which bullish analysts view as important for supporting capital returns..."
Discover why this Narrative puts Assured Guaranty at 26% undervalued.
Assured Guaranty’s valuation still leaves one crucial angle unexplored
Price tags on earnings only tell part of the story, because the people steering Assured Guaranty and how they are rewarded can heavily shape future decisions and risks. See who runs Assured Guaranty and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com