


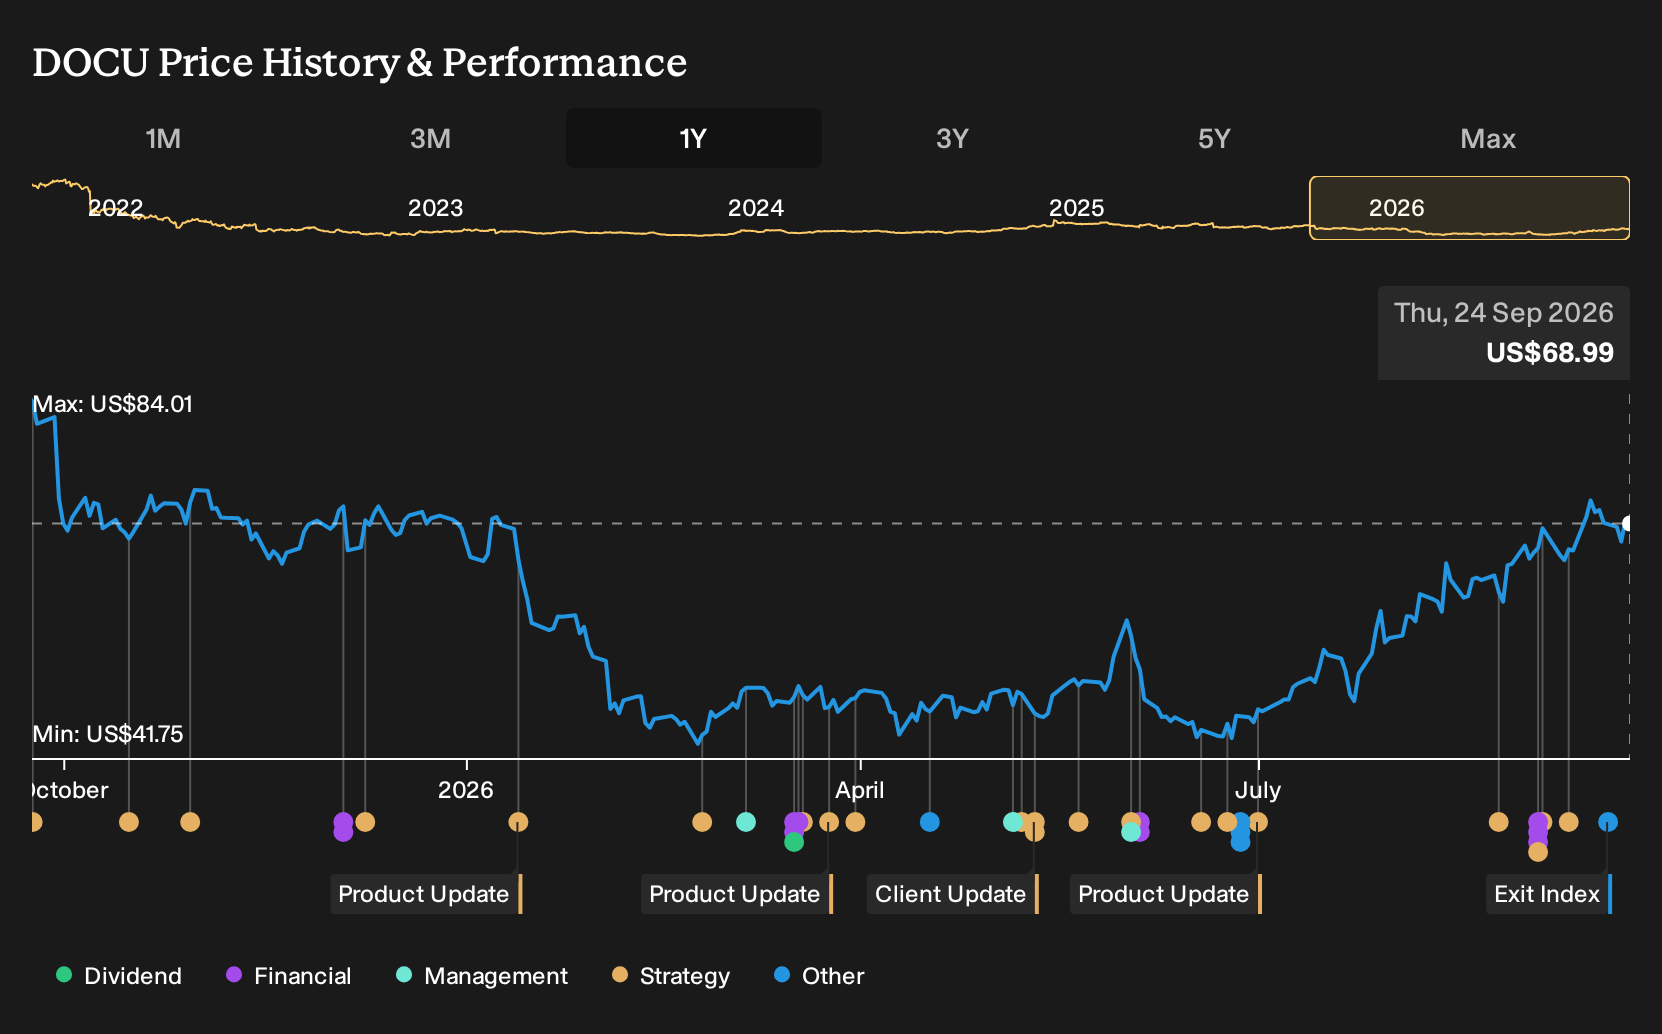
- DocuSign was removed from the FTSE All-World Index in September 2026 and President Robert Chatwani sold 14,676 shares under a pre planned Rule 10b5-1 trading plan, while still holding roughly 0.0398% of the company.
- The index exit can pressure DocuSign through potential fund outflows and lower automatic index demand, even as core agreement software usage, AI tools and international expansion continue to anchor the business story.
- This article assesses how DocuSign's removal from the FTSE All-World Index could reshape the investment narrative around its agreement software platform.
DocuSign Investment Narrative Recap
For a shareholder in DocuSign, the core belief is that digital agreement workflows, AI powered contract tools and the IAM platform can keep attracting new customers while deepening usage with the existing 1.7 million eSign base. The near term swing factor is whether that upsell engine can counter management guidance that already points to 7 to 8% revenue and billings growth.
The FTSE All World exit and Robert Chatwani’s Rule 10b5 1 sale may add some short term technical pressure and feed concern about insider selling, but they do not directly alter product adoption, pricing or competitive intensity. The bigger risk still sits in slower IAM take up, margin headwinds from cloud and rising agreement software competition.
Among recent developments, the most relevant data point is the cluster of insider transactions highlighted over the past quarter. The framework already flags “significant insider selling over the past 3 months,” and Chatwani’s 14,676 share sale under a pre planned program fits into that pattern, even though he still holds roughly 0.0398% of DocuSign.
For you as an investor, that context matters less than whether execution stays on track around IAM, international expansion and margin efficiency. Insider activity can influence sentiment, especially after a 1 year total return that declined 16%, but the medium term story still turns on how effectively DocuSign converts its agreement platform, AI features and FedRAMP ready products into durable subscription demand and stable profitability.
DocuSign's narrative projects US$4.0b revenue and US$482.3 million earnings by 2029. This rests on 7.5% yearly revenue growth and an earnings increase of about US$173.2 million from US$309.1 million today.
Uncover why DocuSign's fair value indicates a 13% potential downside to its current price, a premium that may not be sustainable.
Exploring Other Perspectives
You can read DocuSign's index removal very differently if you focus on competition risk. The most bearish analysts were already modelling slower 6.6% yearly revenue growth to about US$4.1b and US$562.9 million in earnings by 2029, paired with a much lower 17.8x P/E. Those views came before this news, so opinions may evolve as fresh information becomes available.
Explore 7 other DocuSign fair value estimates, including one that suggests as much as 26% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DocuSign research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DocuSign. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DocuSign's overall financial health at a glance.
Looking For More Investment Ideas Beyond DocuSign?
Once you have a view on DocuSign, it can help to compare that thesis with other opportunities that match your risk tolerance, income needs and time horizon. A targeted screener shortlist gives you a cleaner set of candidates to research instead of trying to comb through the entire market one ticker at a time.
- If capital preservation comes first for you, start by reviewing 31 resilient stocks with low risk scores that score well on resilience. This allows you to focus on businesses with relatively steadier profiles.
- Income focused investors can concentrate on dependable cash payouts by filtering for 7 dividend fortresses that may offer higher yields while still considering underlying fundamentals.
- For readers hunting for overlooked potential, cast a wider net with 16 high quality undiscovered gems that pair solid financials with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com