


- Borr Drilling reported that the Odin has begun earning dayrate revenue offshore Texas, while the Idun secured a three-well contract in Vietnam and ENI extended the Bestla charter in Europe to September 2027 with an additional option.
- The cluster of new and extended contracts increases Borr Drilling's forward workload across three regions, tightening rig utilization and providing greater visibility on future operating cash generation.
- We will now see how Borr Drilling's extended Bestla contract could influence the existing investment narrative around fleet utilization and risk.
Scan beyond Borr Drilling and see how other contractors with firm backlogs and healthier finances line up in our hand picked list of solid balance sheet and fundamentals (24 results).
Borr Drilling Investment Narrative Recap
Borr Drilling still asks investors to believe that a young jack up fleet and consistent contract wins can eventually turn a history of losses into sustainable cash generation. The recent Odin, Idun and Bestla updates support that thesis by improving visibility on near term dayrate activity. The key catalyst remains execution on this backlog without cost overruns or material downtime.
The biggest risk stays the same. High leverage and reliance on external borrowing leave limited room for operational missteps or softer rig demand. Payment timing and contract renewals, especially with state linked clients, still matter a lot more than any one new fixture.
The Bestla extension to September 2027 is the most relevant piece here. It shows an existing European client committing to longer use of a Borr Drilling rig at a fixed price, which tightens utilization in that region and slightly improves forward workload visibility beyond 2026.
For catalysts, that kind of multi quarter coverage can help the company focus on operational management of the rig when it assumes control in the fourth quarter of 2026, rather than constantly chasing new work. The tradeoff is exposure to future cost inflation against fixed pricing, which feeds directly into the margin and leverage debate around the stock.
Borr Drilling's narrative projects US$1.4b revenue and US$223.6 million earnings by 2029. This rests on 10.8% yearly revenue growth and an earnings swing of roughly US$467.2 million from a loss of US$243.6 million today.
Uncover why Borr Drilling's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
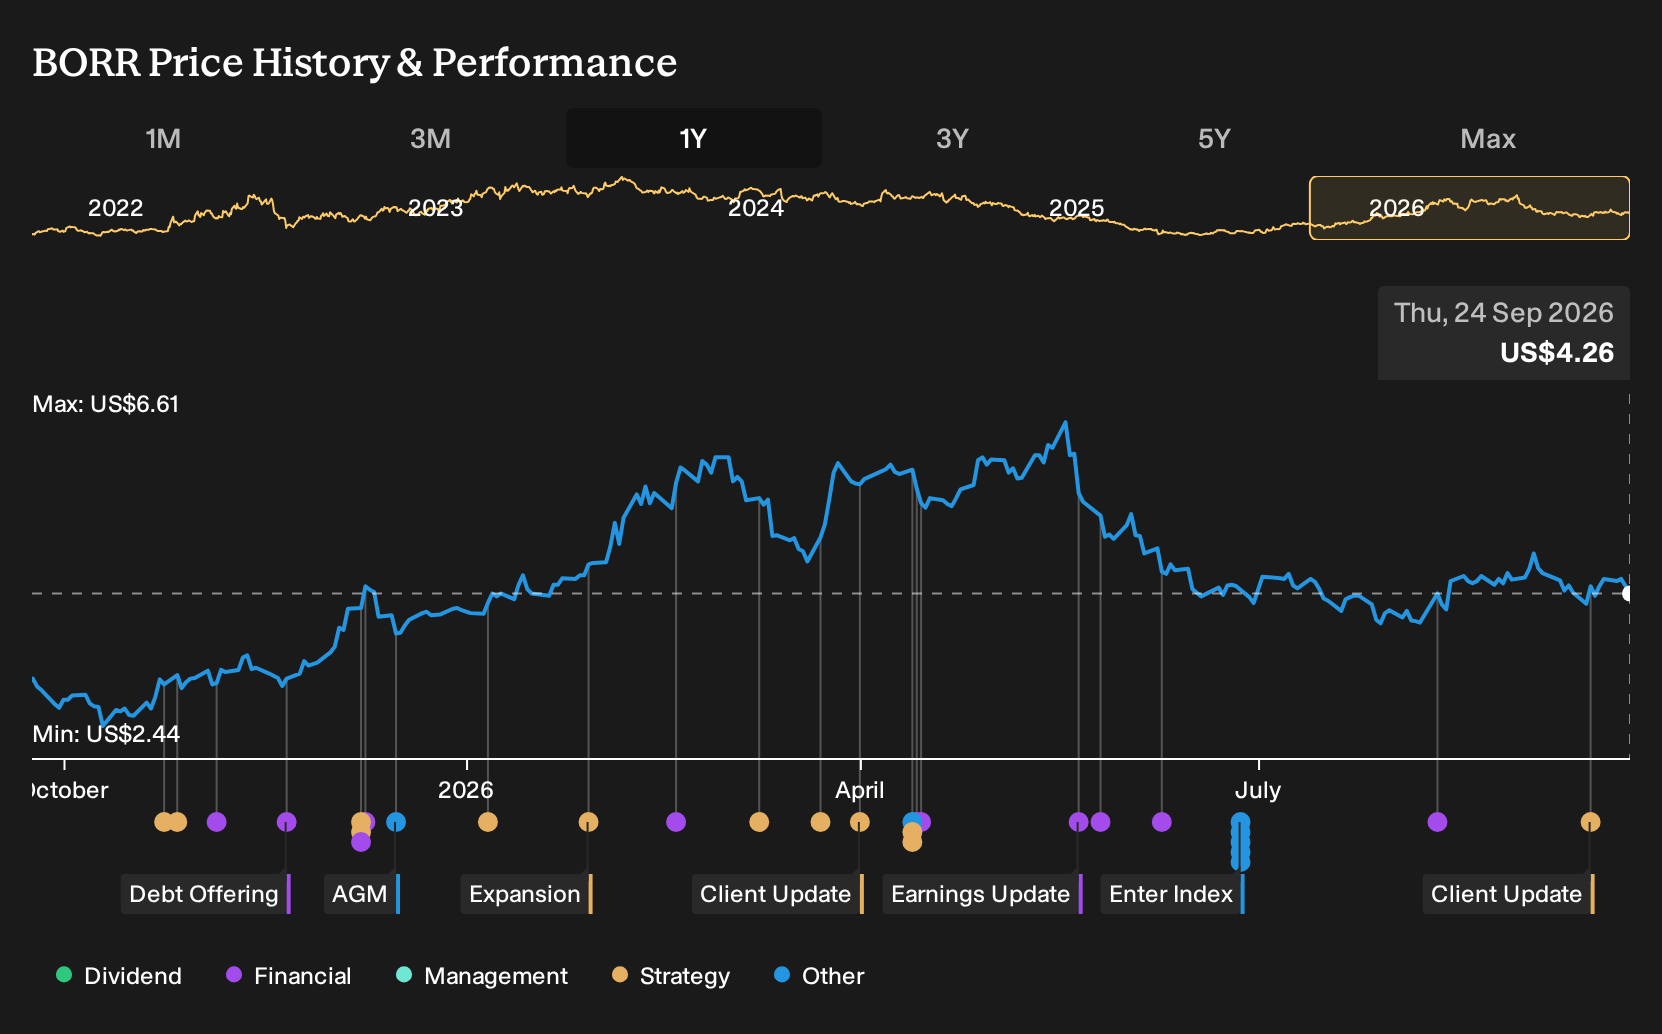
Exploring Other Perspectives
For the most cautious analysts, the key worry is not utilization at Borr Drilling but liquidity. Before this Bestla news, the lowest forecasts still had revenue reaching about US$1.4b by 2029, yet earnings at roughly US$121.0 million. That gap reflects a much harsher view on debt, refinancing risk, and how fragile cash flow could be. You are seeing one set of numbers and two very different stories, so it can be useful to compare both narratives and decide which assumptions feel closer to your own expectations.
Explore 3 other Borr Drilling fair value estimates, including one that suggests it could be worth just $4.76.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Borr Drilling research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Borr Drilling. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Borr Drilling's overall financial health at a glance.
Looking For More Investment Ideas Beyond Borr Drilling?
If the Borr Drilling story has sharpened your thinking on contract coverage, balance sheets and future cash generation, it can be useful to compare it with other listed rigs, shippers or asset heavy businesses that share similar financial themes.
- For investors who want potential mispricing combined with solid fundamentals, scan through 30 high quality undervalued stocks that already clear quality and balance sheet checks.
- If capital protection matters most to you, start with 30 resilient stocks with low risk scores that aim to keep business and financial risk scores on the lower side.
- When you want early stage opportunities but still care about financial strength, focus on the 8 elite penny stocks with strong financials that pair smaller market values with sturdier accounts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com