


SINOPEC Engineering (Group) and the Uzbekistan SAF project
SINOPEC Engineering (Group) (SEHK:2386) is back in focus after hosting a major Front End Engineering Design meeting in Ningbo for a planned sustainable aviation fuel and e SAF complex in Uzbekistan.
The Ningbo session brought together Allied Biofuels, SINOPEC Engineering, Topsoe, Sasol and Plug Power to align responsibilities, technology interfaces and an execution schedule intended to move the project through FEED toward a future investment decision.
SINOPEC Engineering (Group)'s recent role in the Uzbekistan SAF project comes as the share price sits at HK$5.315, with a 30-day share price return of 5.04% and a year-to-date share price decline of 30.25%, while the 5-year total shareholder return of 104.30% points to stronger longer run compounding despite a 15.19% total shareholder return decline over the past year.
Scan other engineering and clean energy plays that could be setting up for the next move with our curated list of list of solid balance sheet and fundamentals (201 results)
The recent bounce in SINOPEC Engineering (Group) after a steep year to date decline could signal that investors are refocusing on the underlying engineering franchise rather than trading mood. How does that tension show up in today’s valuation?
Price-to-Earnings of 12.9x for SINOPEC Engineering (Group): Is it justified?
On a simple snapshot, SINOPEC Engineering (Group) trades on a P/E of 12.9x, which screens as expensive next to both its peers and an internally estimated fair level.
The P/E ratio compares the current share price with earnings per share and gives a shorthand for how much investors are paying for each unit of profit. For an engineering and construction contractor like SINOPEC Engineering (Group), that lens matters because earnings can be cyclical and tied to project timing rather than smooth, recurring revenue.
Here, the market is assigning SINOPEC Engineering (Group) a P/E of 12.9x, compared with a peer average of 6x and a Hong Kong Construction industry average of 12.8x. That points to a premium versus similar stocks and only a marginal uplift versus the broader sector. This is a strong signal that a fairer level could be closer to the 10.5x fair P/E suggested by regression analysis.
Explore the SWS fair ratio for SINOPEC Engineering (Group).
Result: Price-to-Earnings of 12.9x (OVERVALUED)
Still, SINOPEC Engineering (Group) faces clear risks if Uzbekistan SAF timelines slip or if earnings weaken, which could make a 12.9x P/E look exposed.
Find out about the key risks to this SINOPEC Engineering (Group) narrative.
Another view on SINOPEC Engineering (Group)'s valuation
P/E says SINOPEC Engineering (Group) looks expensive, yet the SWS DCF model points the other way. At HK$5.32, the shares sit about 17.6% below an estimated future cash flow value of HK$6.45. If earnings forecasts hold, which lens will traders trust more?
Look into how the SWS DCF model arrives at its fair value.
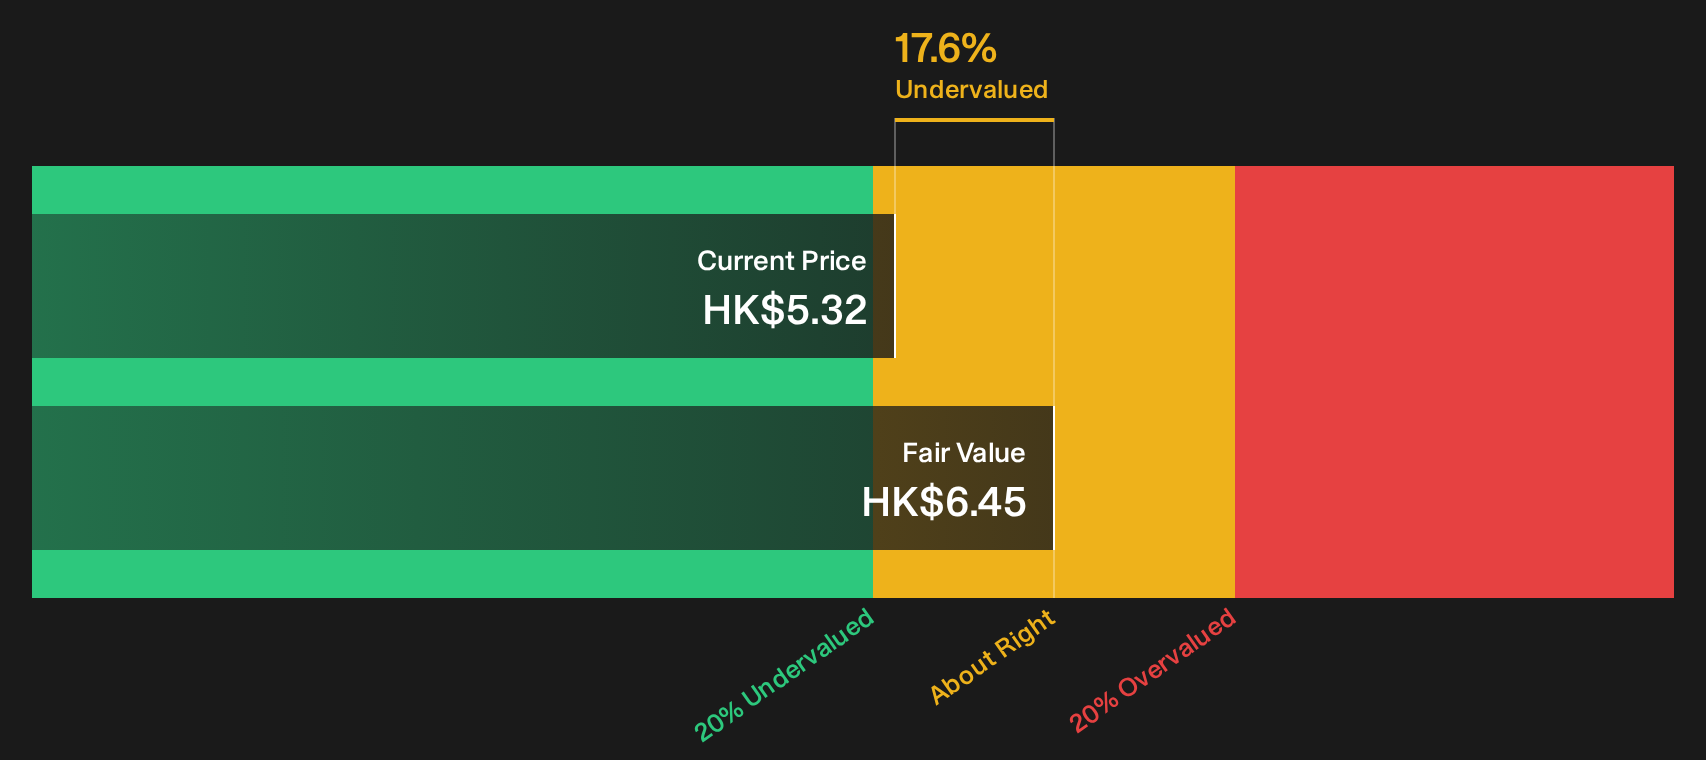
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SINOPEC Engineering (Group) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around SINOPEC Engineering (Group) can feel messy, so move quickly, test the numbers yourself, weigh the concerns and the upside, then pressure check those views against the 3 key rewards and 2 important warning signs
Looking for more SINOPEC Engineering (Group) style investment ideas?
If SINOPEC Engineering (Group) has sharpened your focus on pricing and quality, do not stop here. The right watchlist today can shape tomorrow’s decisions.
- Target stronger value by scanning companies that combine quality fundamentals with attractive pricing through the 179 high quality undervalued stocks.
- Prioritize resilience by checking out businesses with healthier finances using the 229 resilient stocks with low risk scores.
- Hunt for under-followed opportunities by reviewing a curated set of under-the-radar stocks via the 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com