


Europe is bracing for another painful winter of high energy and diesel headlines, and that puts household budgets back under the microscope. When power and fuel stay expensive, shoppers hunt harder for value and shift spending habits in surprising ways. Those swings can help some consumer staples stocks and leave others struggling. This article unpacks the story and highlights three European value-focused retailers that are exposed to these pressures.
The retailers covered below are only a sample of this theme, and the broader screen surfaced 10 more listed European value-focused consumer staples and discount players with equally compelling stories that are not covered in this article. To go straight to the full European Value-Focused Consumer Staples and Discount Retailers results and identify, compare, and analyze your highest conviction candidates, head into the European Value-Focused Consumer Staples and Discount Retailers screener.
Koninklijke Ahold Delhaize (ENXTAM:AD)
Overview: Koninklijke Ahold Delhaize is a long established European supermarket and online grocery group focused on value oriented everyday essential shopping.
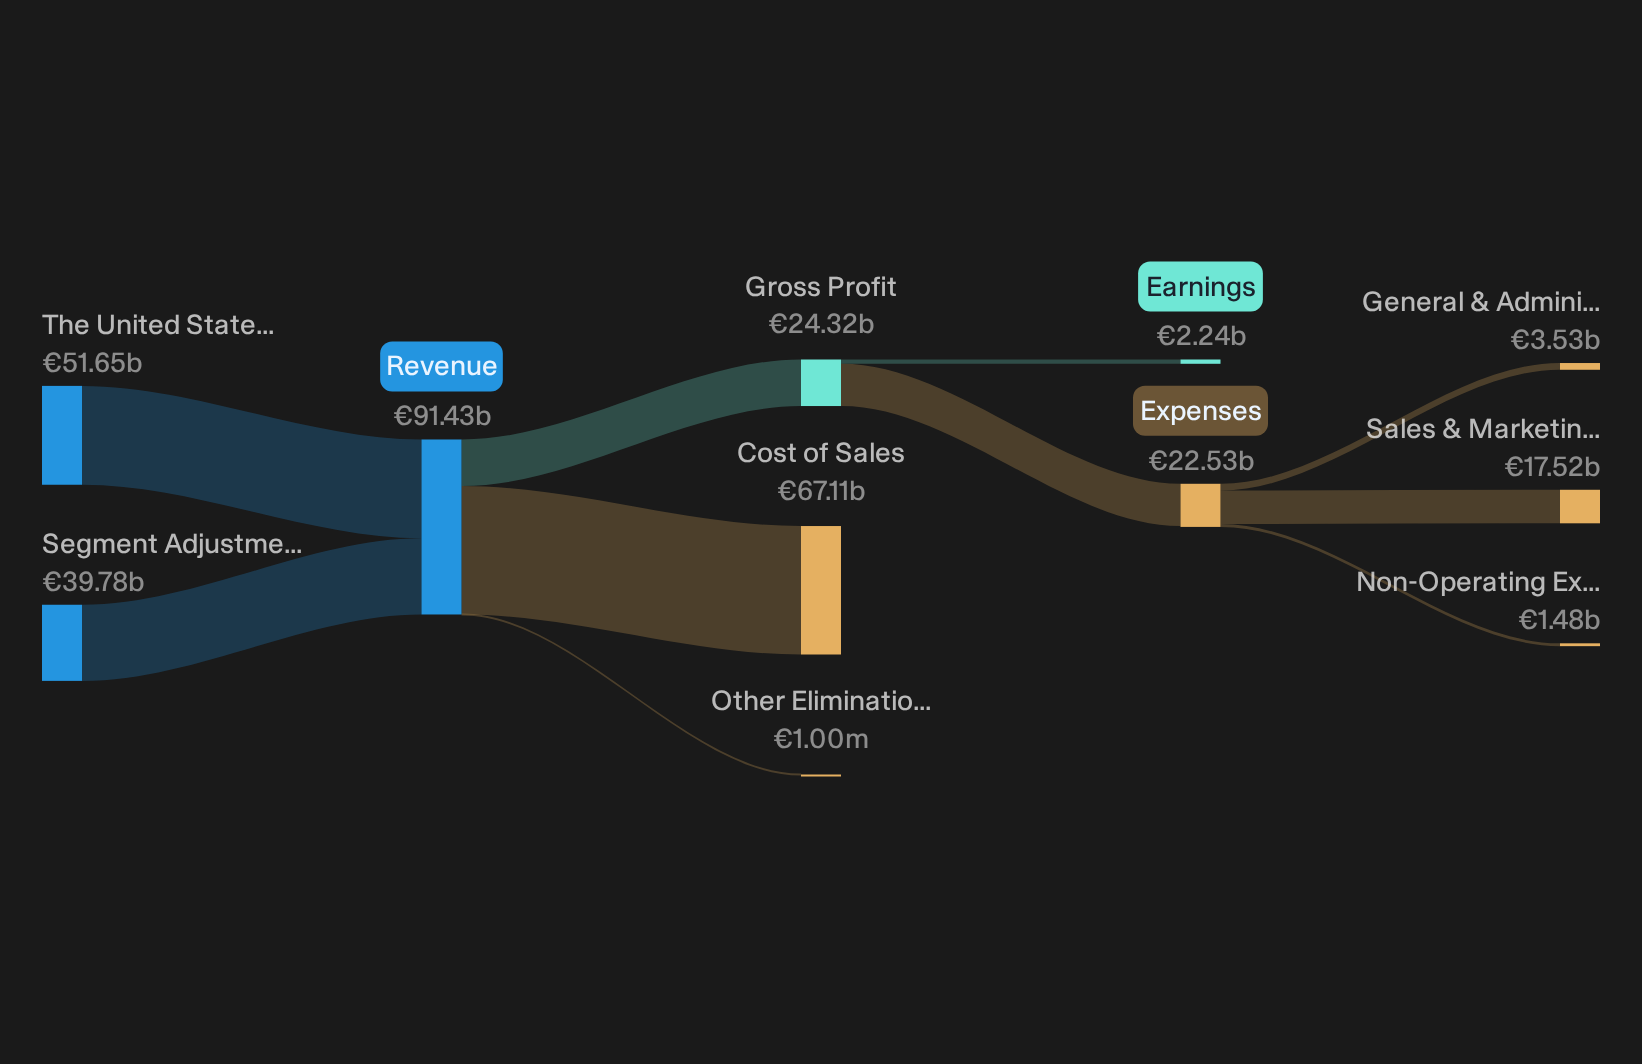
Operations: The United States segment generates €51.6b of revenue, with a further €39.8b reported as segment adjustment on a group basis.
Market Cap: €27.6b
Koninklijke Ahold Delhaize fits this value focused grocery theme because its mix of discount friendly supermarkets and mature online platforms is designed for shoppers who are watching every euro on essential goods.
"The ongoing expansion and innovation in omnichannel and e-commerce, including proprietary digital platforms (PRISM, Spectrum), surging online grocery/marketplace adoption, and rising profitability, position Ahold Delhaize to capture revenue growth and improve customer retention as consumer digital adoption accelerates.
What really matters now is how one unseen pressure on cost control and pricing power shapes future margins in this value model.
Those cost pressures can quietly reshape the whole thesis, so read the full narrative for Koninklijke Ahold Delhaize to see how omnichannel strength, capital discipline, and pricing power could interact next.
Jerónimo Martins SGPS (ENXTLS:JMT)
Overview: Jerónimo Martins SGPS runs value-focused grocery chains like Biedronka and Pingo Doce across Portugal, Poland and Colombia, serving everyday essential shopping.
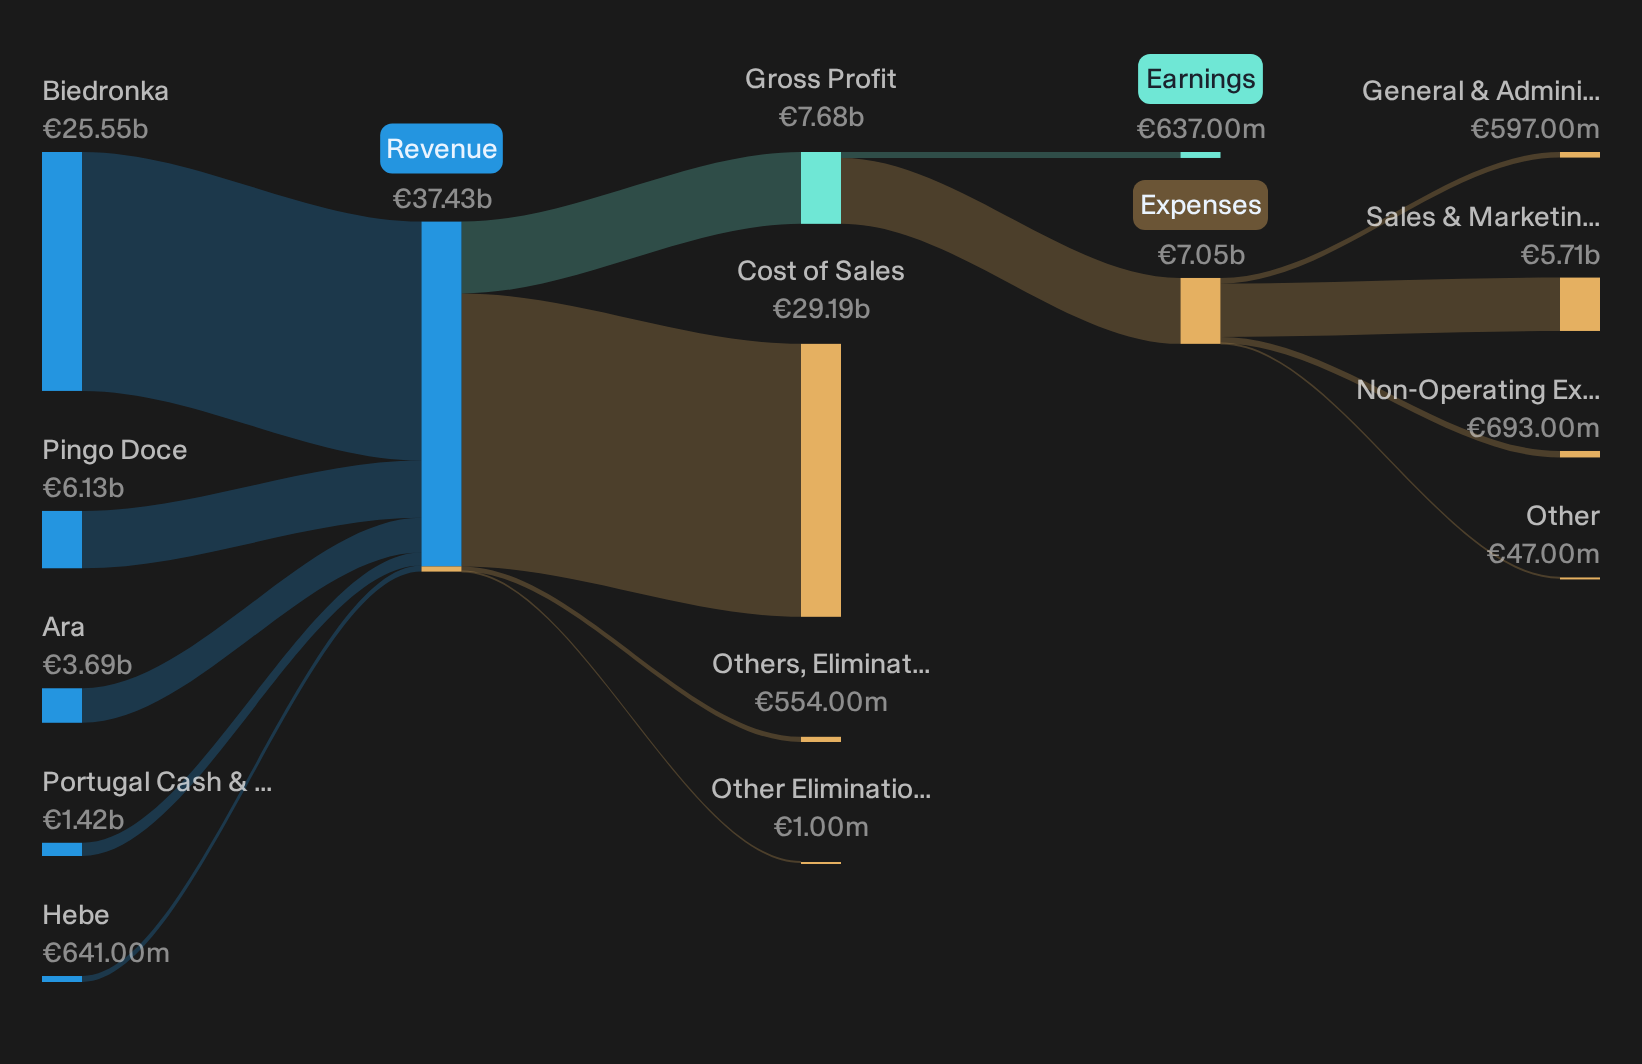
Operations: Jerónimo Martins SGPS generates most of its revenue from Biedronka at €25.6b, with Pingo Doce contributing €6.1b and Ara €3.7b.
Market Cap: €11.2b
Jerónimo Martins SGPS fits squarely into this value retail theme because its discount formats and proximity stores are built around low prices and tight household budgets in markets where energy and living costs are under pressure.
"Sustained store network expansion in Poland, Colombia, and new markets such as Slovakia increases scale and revenue growth potential, leveraging urbanization and rising middle-class consumer demand in Central and Eastern Europe (impact: group revenues, operating leverage)."
What really moves the needle for investors is how one unresolved pressure on costs and pricing shapes the balance between volume growth and margins.
That margin question is where it gets interesting, so read the full narrative for Jerónimo Martins SGPS to see how Jerónimo Martins SGPS could turn cost pressure into accelerating value.
Carrefour (ENXTPA:CA)
Overview: Carrefour is a pan-European and international food retailer running hypermarkets, supermarkets, convenience and discount stores, plus e-commerce, focused on value-conscious everyday shopping.
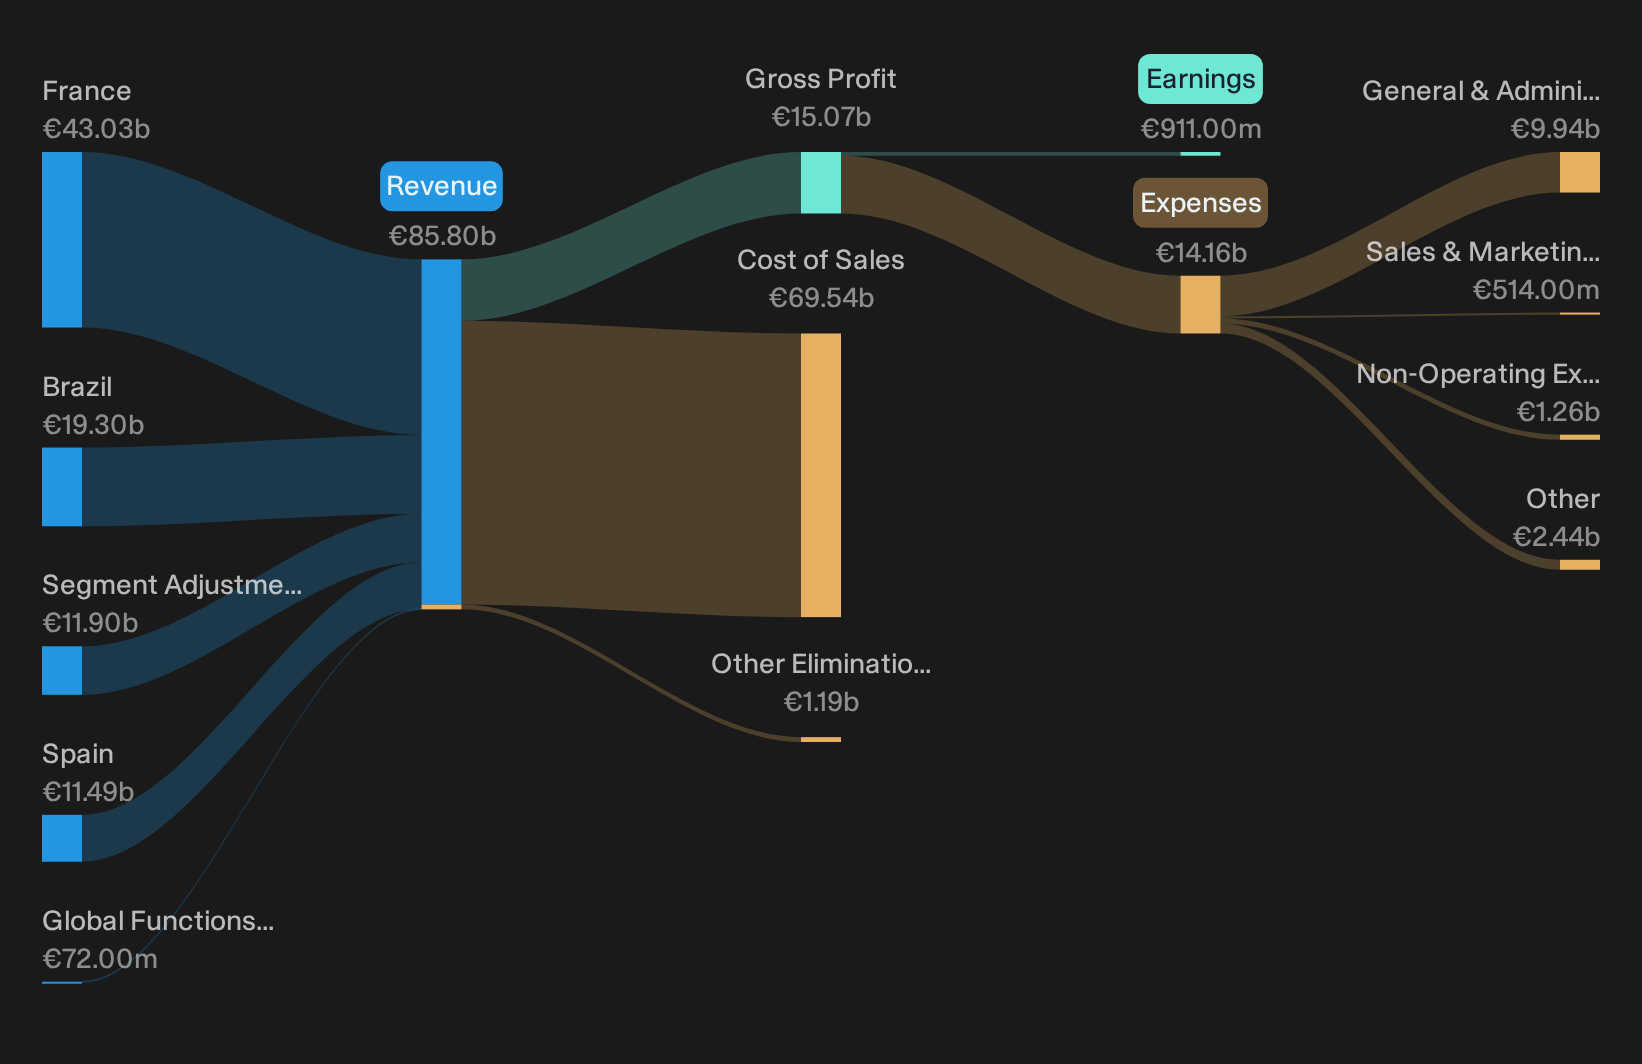
Operations: Carrefour generates about €43.0b of segment revenue in France, €19.3b in Brazil, €11.5b in Spain, with additional segment adjustments of €11.9b.
Market Cap: €11.4b
Carrefour matters for this value-focused screen because its mix of hypermarkets, discount formats and private-label ranges can become a pressure valve for households when energy and fuel bills squeeze disposable income.
"The accelerating shift toward e-commerce and digital marketplaces continues to undermine Carrefour's traditional brick and mortar retail formats, with persistent negative volume growth in core European markets and only limited offset from online gains, threatening to erode both revenue and long-term market share."
What happens to Carrefour's pricing power and thin margins if a single cost, demand or funding assumption shifts against this value model?
That pressure point is exactly where the Carrefour story could be mispriced, so read the full narrative for Carrefour to see how cost risks and recovery potential might be decoupling.
Curious About What You Might Be Missing?
Markets move fast, and fresh ideas do not stay under the radar for long. Spot potential breakout momentum and dropping misprices before the crowd does, and act now.
- Target resilient cash generators by scanning a curated list of solid balance sheet and fundamentals (201 results) that lets you focus on businesses where financial strength supports staying power when conditions get tougher.
- Ride structural shifts by reviewing a hand picked 84 AI infrastructure stocks basket featuring companies plugged into the hardware and plumbing behind accelerating artificial intelligence demand.
- Lean into real asset exposure through a focused 36 elite gold producer stocks list that highlights producers geared to bullion moves while equity prices have not fully caught up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com