


Kroger has delivered solid long term gains for shareholders, even as its share price has come under some pressure more recently. With the stock now around US$58.92, the question for you is whether that price still lines up with what the supermarket group is earning today.
- The share price has returned about 62.4% over 5 years, which puts real weight on whether Kroger's earnings profile can carry that kind of long haul performance.
- Recent news around slower comparable store sales growth and store investments, alongside its push into AI tools for customers and staff, may influence how investors think about the durability and timing of future profit streams.
- Your read on Kroger is one view; the desks covering it have another. See what analysts think Kroger's shares could be worth.
For investors, the debate is whether Kroger's current share price is properly supported by the earnings the business is generating today.
If you are weighing Kroger against other possibilities and want a starting list built around quality and value, a focused screener of 30 high quality undervalued stocks can help frame the next stage of your research.
Does Kroger Look Fairly Valued on Earnings?
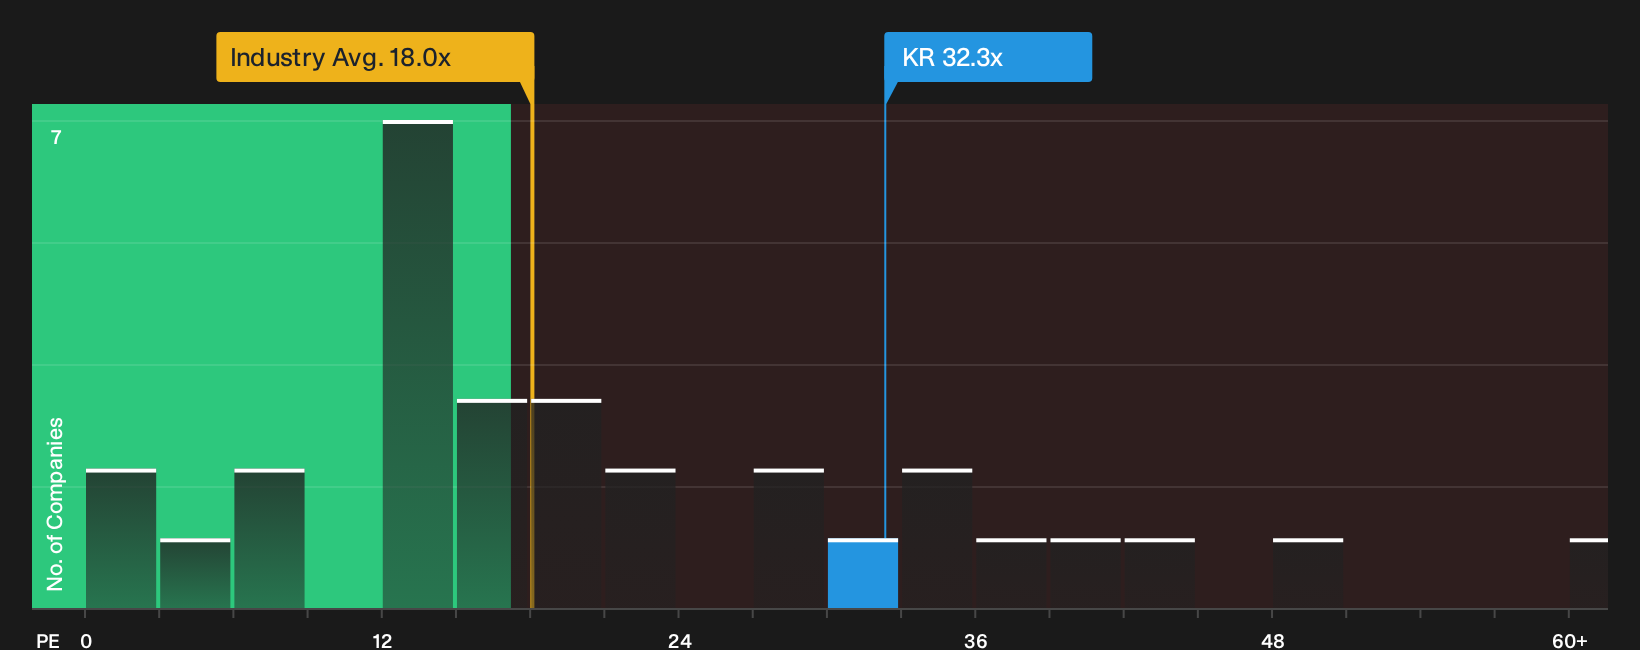
The P/E ratio is a useful way to see what investors are paying for each dollar of Kroger earnings. On this yardstick, Kroger trades on about 32.3x, which is below the consumer retailing peer group on roughly 37.6x but well above the wider industry average near 18.0x. That mix indicates the stock is priced more richly than the broader supermarket space while still at some discount to closer peers focused on similar business models.
The fair value framework, which adjusts for Kroger specific factors like growth profile, profitability and risk, points to a level very close to the current P/E, so the market price is not significantly out of line with those fundamentals. Because management recently raised its profit outlook despite softer identical store sales, the earnings base that underpins this multiple will likely be a key figure for investors to watch. Explore the numbers behind Kroger's P/E valuation.
The Kroger Narrative: What Would Justify Today's Price?
Narratives take the P/E puzzle around Kroger and turn it into clear scenarios that explain what kind of growth, margins and earnings path would need to unfold for the stock to look meaningfully higher or lower than today’s level. Each view links its number to a specific perspective on Kroger’s future growth, profitability and risk, giving you a reference point you can return to on Simply Wall St’s Community page as new information comes through.
Community views on Kroger are split between those who see more upside in the current setup and those who think expectations are already baked in.
Bull case: 14% undervalued
"Aggressive cost optimization efforts, including further supply chain automation and adoption of AI and data analytics for shrink reduction, are expected to enhance operational efficiency…"
Discover why this Narrative puts Kroger at 14% undervalued.
Bear case: roughly fairly valued
"Although Kroger is seeing strong growth in e-commerce and has reached profitability in this channel, including media, continued higher transportation and fuel costs could limit how much of this progress flows through to net margins and earnings…"
Explore why this Narrative puts Kroger at roughly fairly valued.
The Kroger story is not just about what you pay today
Price and earnings only tell part of the Kroger picture, because the research checks have also flagged specific risk signals that can shift how you weigh everything else. Take a closer look at 4 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com