


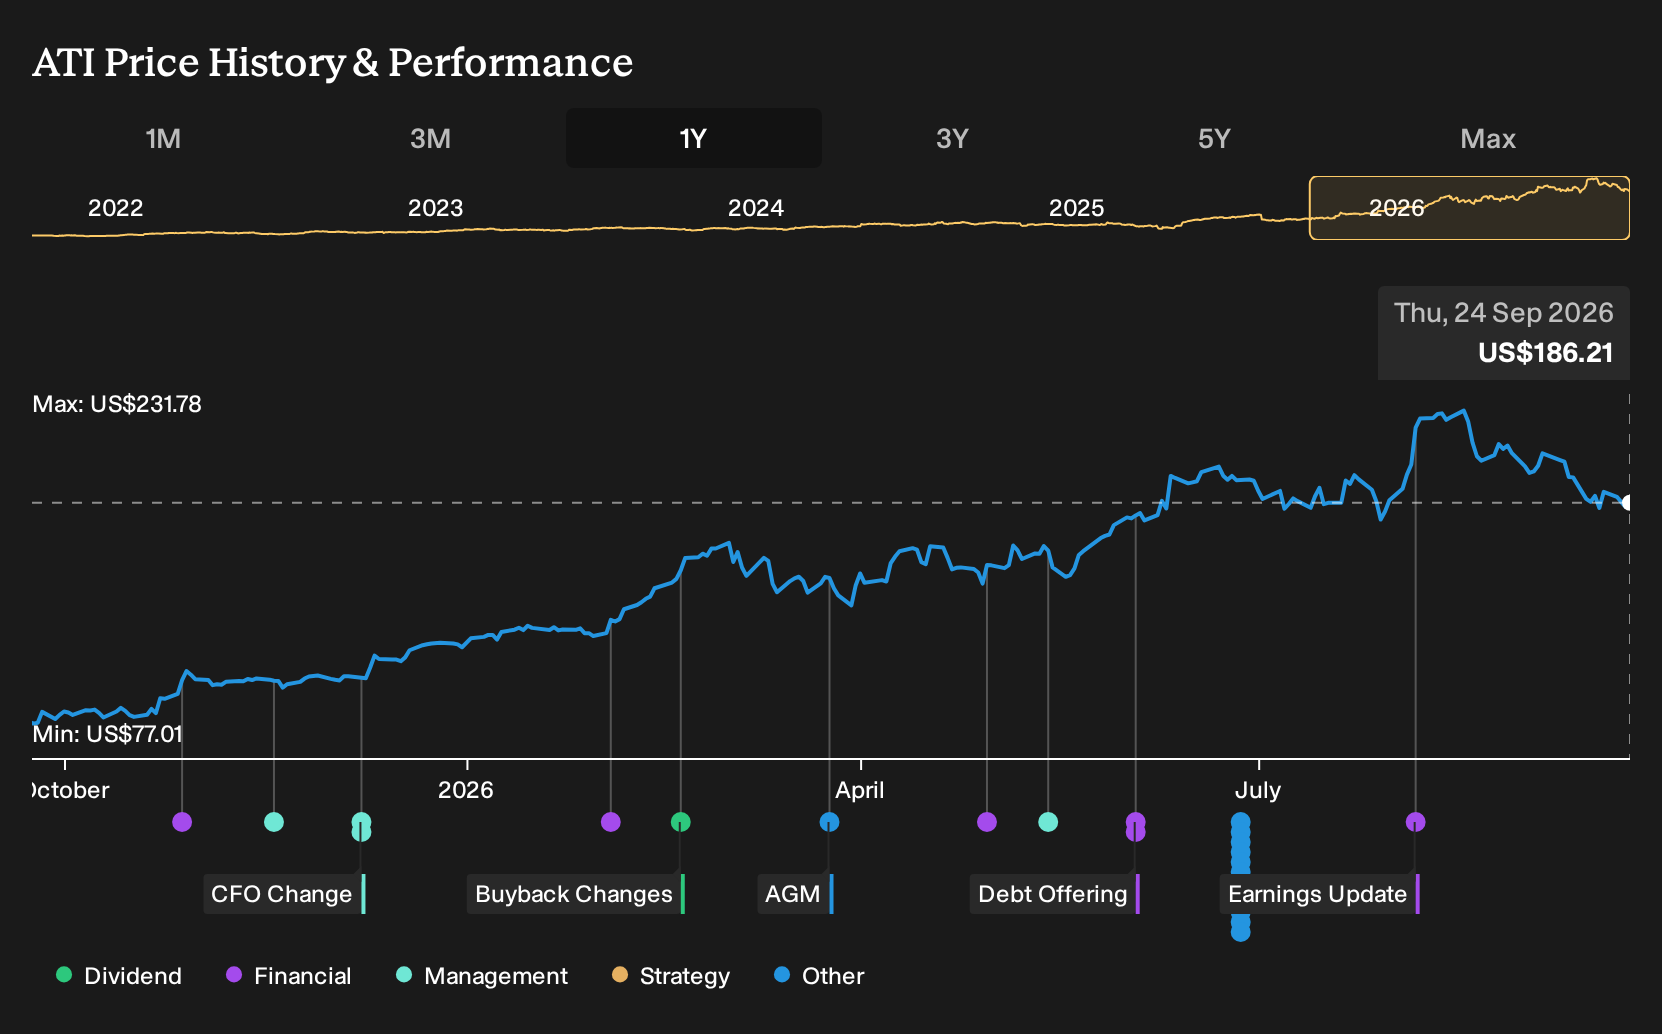
- ATI raised its 2026 adjusted EBITDA guidance on the back of a record backlog, a higher-margin product mix, and strong demand from next-generation engines and defense programs.
- Management's focus on aerospace and defense, now close to 70% of revenue, is reshaping ATI into a more specialized, higher-margin materials supplier.
- Now the focus shifts to how ATI's upgraded 2026 EBITDA outlook could reshape the existing investment narrative around margins and growth.
Scan how ATI’s aerospace and defense tilt compares with other potential breakout opportunities across specialized materials and industrials using our curated list of 16 high quality undiscovered gems.
ATI Investment Narrative Recap
For ATI, the shareholder pitch starts with belief in a high value materials platform tied tightly to aerospace and defense demand. The raised 2026 adjusted EBITDA guidance leans on a record backlog and richer mix, so the near term catalyst is clean execution on those programs. The biggest risk right now is that industrial and medical markets stay sluggish, which would keep non aerospace earnings under pressure.
The updated outlook does not eliminate concerns around heavy capex and a high debt load. It just raises the bar for delivery. If large aerospace customers change build schedules or shift share, ATI’s concentration could quickly test that higher EBITDA run rate and expose how resilient the model really is.
The most relevant announcement here is ATI’s EBITDA guidance upgrade tied to next generation engines, naval nuclear work, and other defense programs. That outlook turns aerospace and defense into the clear heartbeat of the thesis. Investors are effectively betting that these programs flow through the backlog at healthy pricing without major schedule disruptions.
This same update also sharpens the risk profile. Higher expected earnings rely on debottlenecking projects, new melt capacity, and process improvements landing on time and on budget while the firm still carries meaningful leverage. If execution on those investments stumbles or demand for industrial and medical alloys stays weak, the story around margin strength could look more fragile.
ATI Consensus Targets Set a High Bar
ATI's narrative projects US$5.9b revenue and US$874.1m earnings by 2029. That profile reflects consensus expectations of 8.9% yearly revenue growth and roughly an increase in earnings from US$425.5m today to the 2029 consensus level.
Uncover why ATI's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts technology risk front and center. The most cautious ATI analysts worried that composites and ceramics could chip away at metal demand, even while they were still penciling in about US$6.2b of revenue and US$993.1m of earnings by 2029. Those forecasts came before this guidance hike, so opinions may change.
Explore 4 other ATI fair value estimates, including one that suggests as much as 11% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your ATI research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ATI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATI's overall financial health at a glance.
Looking For More Ideas Beyond ATI?
If ATI's reshaped aerospace and defense profile has sharpened your thinking about where to put fresh capital to work, it can help to line it up against other potential opportunities with different risk and income profiles.
- If you want potential bargains with solid fundamentals, scan through our curated set of 30 high quality undervalued stocks that pair quality with compressed expectations.
- For readers who care most about balance sheet strength and durability, filter for companies in the list of solid balance sheet and fundamentals (24 results) so you can focus on sturdier financial foundations.
- If income is a priority, use the list of 7 dividend fortresses to find candidates that combine higher yields with a focus on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com