


Rising Treasury yields have pushed borrowing costs to levels last seen in the mid 2000s, which is putting pressure on highly leveraged businesses and flattering those that generate solid cash inflows. When money is more expensive, investors tend to care a lot more about what a company actually earns in cash than about stories or hype. This article highlights three stocks where current prices sit below what their cash flows suggest they may be worth.
The three examples below are only a small sample of what screens well on cash generation, as the full filter surfaced 43 more companies with similarly compelling stories that are not covered here. If you want to identify and analyze the wider set of ideas that screened as undervalued on discounted cash flows, head straight into the Undervalued Stocks Based On Cash Flows screener.
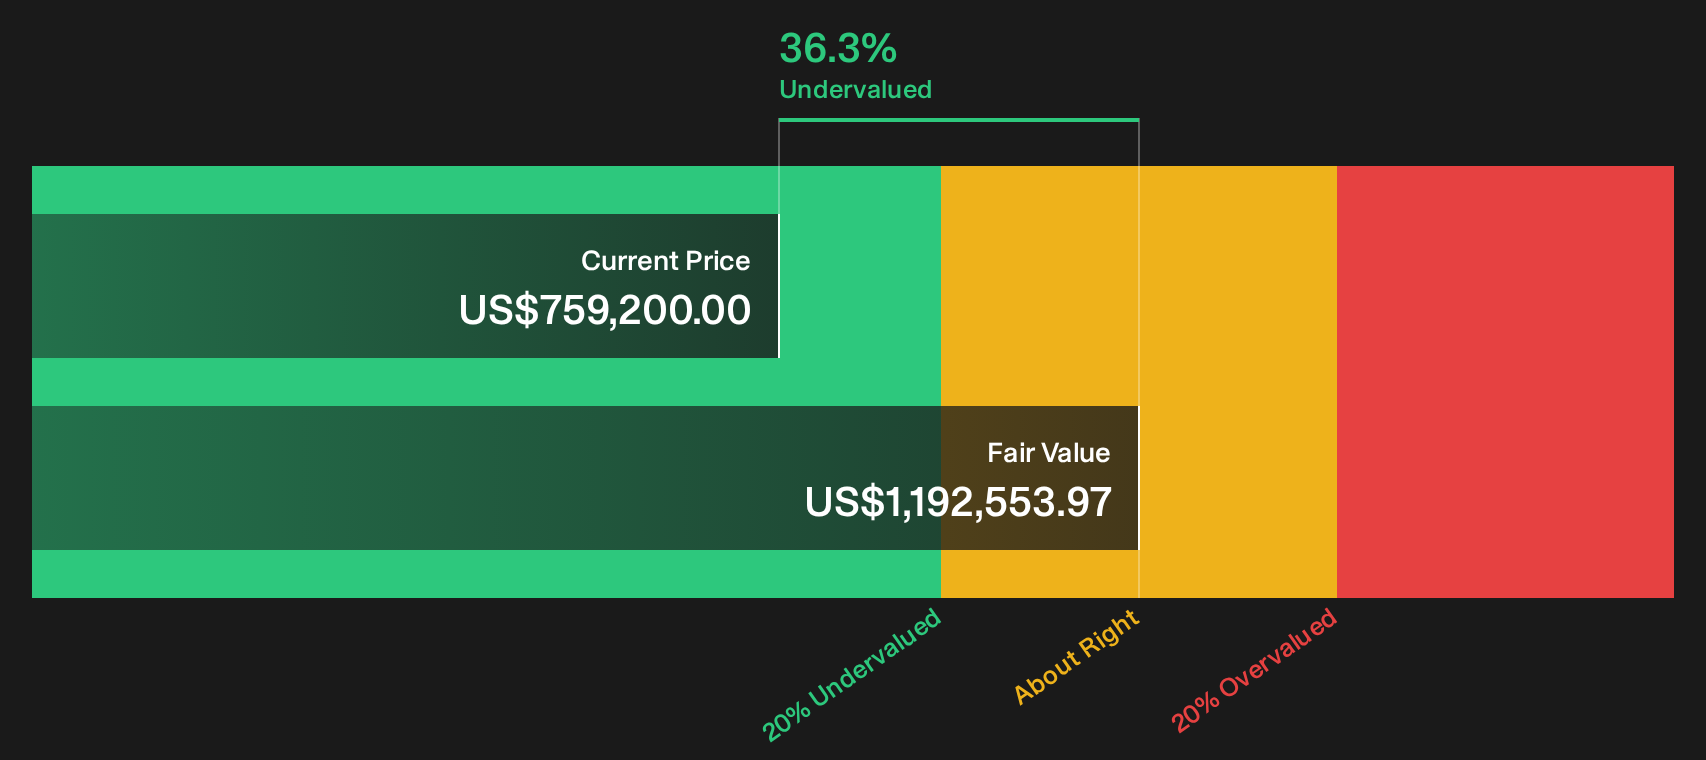
Berkshire Hathaway (BRK.A)
Overview: Berkshire Hathaway is a diversified US conglomerate whose insurance, rail, energy and manufacturing businesses generate large, recurring cash flows.
Operations: Berkshire earns most of its revenue from Manufacturing at US$82.99b, with additional large contributions from GEICO at US$45.14b, Pilot Travel Centers at US$47.84b and other insurance and rail subsidiaries.
Market Cap: US$1.09t
Berkshire Hathaway fits this cash flow focused screen because its insurance float and broad operating subsidiaries generate sizeable, repeatable cash that management can reinvest when prices look attractive.
"The company's path forward is grounded in ruthless efficiency and strategic capital deployment. Management has indicated an internal focus on technologies such as AI aimed at improving operational efficiency."
What happens when that steady cash engine meets one unresolved pressure around how quickly those funds are put to work will really matter.
When that capital deployment bottleneck starts to shift, full narrative for Berkshire Hathaway shows how Berkshire Hathaway’s cash engine could accelerate or stall depending on management’s next moves.
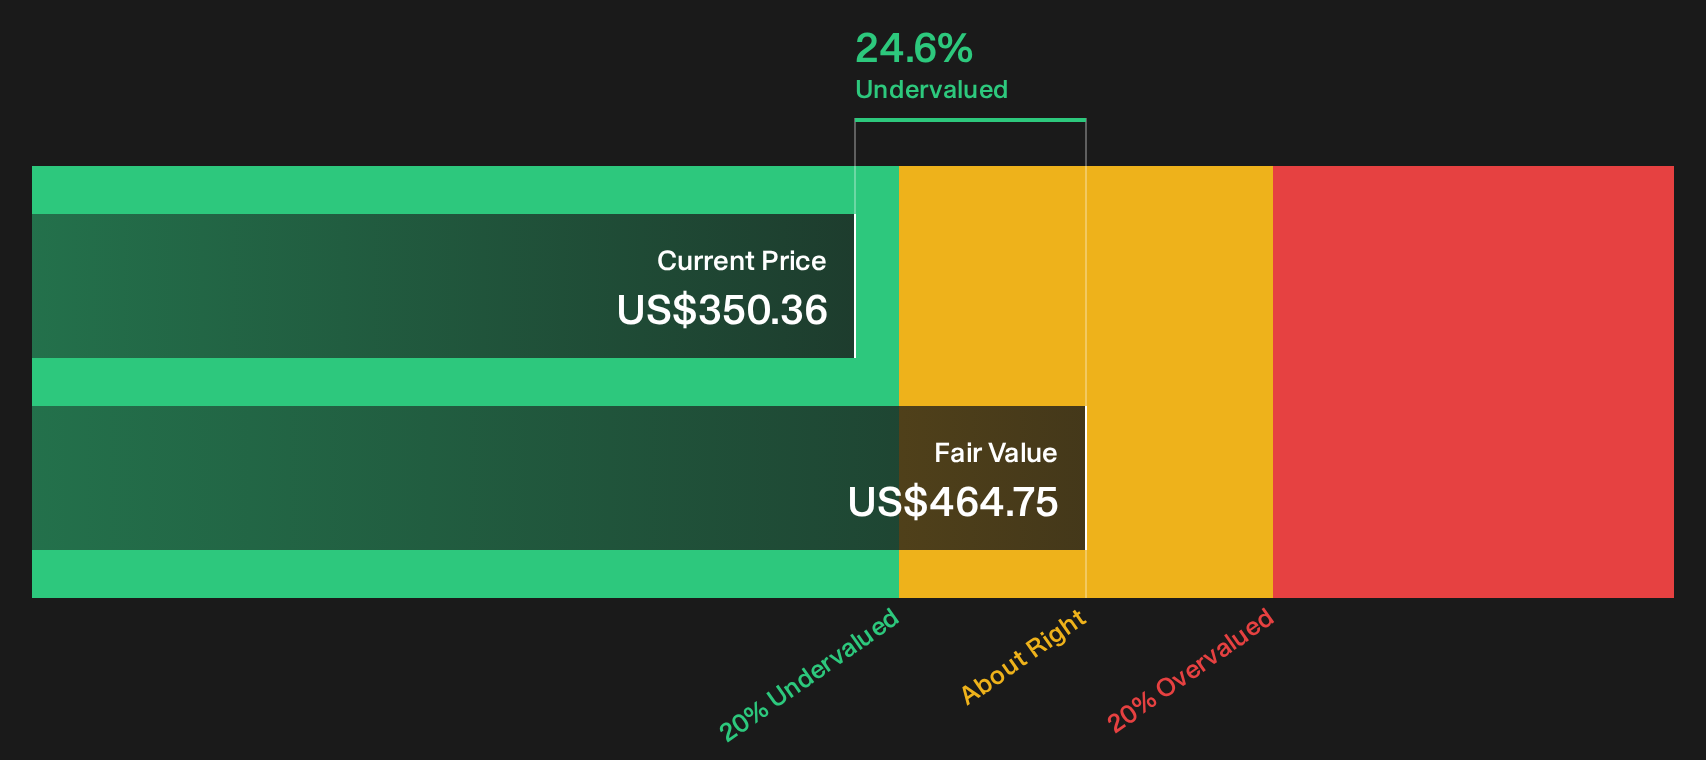
Broadcom (AVGO)
Overview: Broadcom integrates semiconductor hardware with infrastructure software like VMware and enterprise security tools, generating substantial recurring cash flows from digital infrastructure.
Operations: Broadcom reports US$29.67b from Infrastructure Software and US$59.44b from Semiconductor Solutions and IP licensing, reflecting a balanced hardware software mix.
Market Cap: US$1.69t
Broadcom matters for this cash-flow-focused screen because its VMware and enterprise software subscriptions help turn AI and networking demand into contract-based revenue rather than one-off hardware cycles.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
What happens if one key assumption about the durability of those long-term software contracts and AI infrastructure budgets starts to shift?
If that contract risk has you weighing how resilient Broadcom’s cash machine really is, the full narrative for Broadcom explains where its momentum could accelerate or stall next.
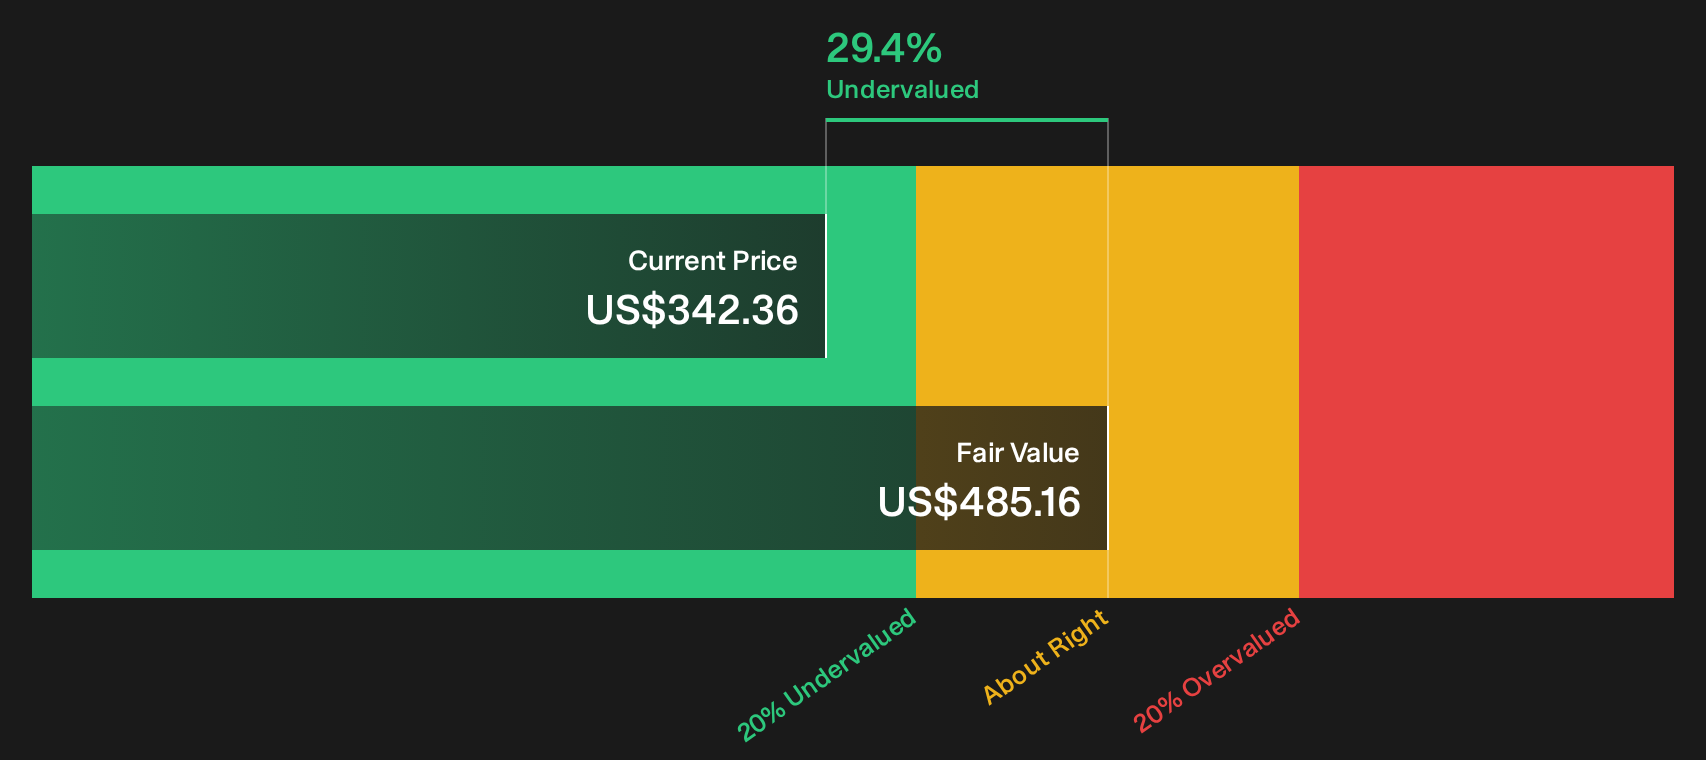
Alphabet (GOOGL)
Overview: Alphabet is a global technology company whose Google Services and Google Cloud platforms provide digital ads, consumer apps and enterprise AI tools.
Operations: Alphabet generates US$367.1b from Google Services, US$77.6b from Google Cloud and US$1.5b from Other Bets, anchored in the United States.
Market Cap: US$4,168.3b
Alphabet matters for a cash flow focused screen because Google Cloud’s AI infrastructure and Vertex AI subscriptions turn AI demand into recurring, high-margin inflows that support long-term free cash generation rather than one-off hardware spikes.
"Google Cloud has gone from “meh” to money-maker. • Now #3 globally behind AWS and Azure, with over 11% market share."
What happens when one huge AI-driven backlog either flows cleanly into cash or bumps into rising capital and energy costs will be critical.
If that cash conversion question is front of mind, the full narrative for Alphabet shows how Alphabet’s AI pipeline, capex demands and ad engine could be decoupling in surprising ways.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time a breakout is flying, the easy entry can be gone. Scan new momentum while it matters, under the radar for now, and look for ways to get in early.
- Spot fast-moving opportunities in smaller companies before they get widely noticed by using the 8 elite penny stocks with strong financials curated for financial strength and real business traction.
- Track where capital is quietly lining up around digital assets and payment rails by reviewing the hand picked 21 cryptocurrency and blockchain stocks that link crypto themes to listed equities.
- Focus on resilient operators positioned for long runway themes by filtering through the curated 30 resilient stocks with low risk scores that combine lower risk scores with solid fundamentals and staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com