


Wolfspeed shares have logged a 38.9% gain year to date, which naturally puts the focus on whether the current US$26.30 price still lines up with what the business is generating in sales. For anyone tracking the stock, the core issue now is how that share move stacks up against the revenue base supporting it.
- The 38.9% year to date return raises a straightforward issue for holders, because a move of that size quickly tests how much sales can justify on their own.
- The company is heavily focused on scaling its silicon carbide based products, which can affect both future revenue potential and how much near term investment is needed before those sales show up fully in the numbers.
- Your read on Wolfspeed is one view; the desks covering it have another. See what analysts think Wolfspeed's shares could be worth.
The stock's next move may depend on whether Wolfspeed's current market value is adequately backed by its sales performance and sales outlook.
If you want a wider view on whether a 38.9% year to date move still lines up with underlying sales, a focused screener of 30 high quality undervalued stocks can be a useful second reference point.
Is Wolfspeed Getting Expensive on Sales?
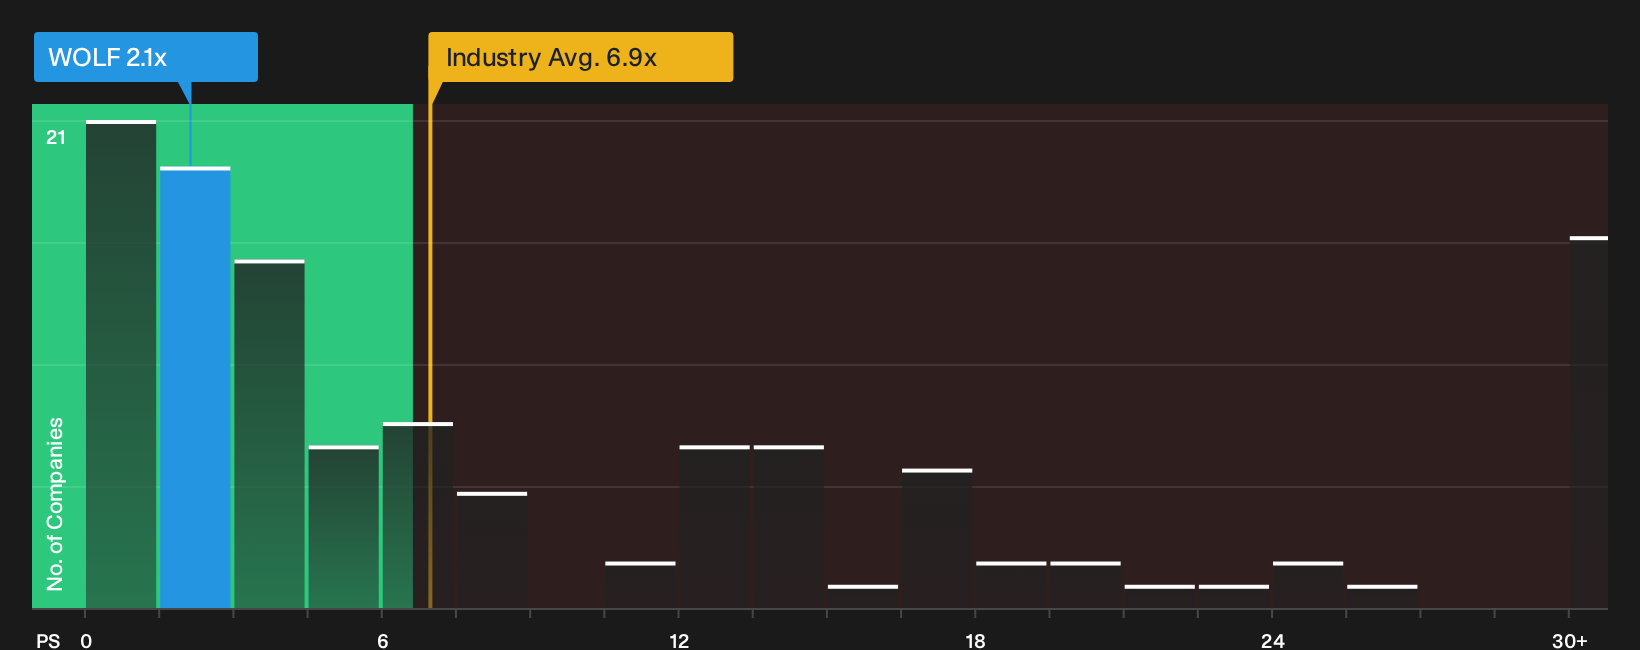
P/S fits Wolfspeed because the focus is firmly on building sales rather than near term profits. On that yardstick, the stock trades around 2.1x trailing revenue, which is well below the broader semiconductor sector on roughly 6.9x and also under the peer group near 12.1x. For a business still pouring cash into expansion, that gap indicates the market is attaching a much lower price tag to each dollar of Wolfspeed’s turnover than to many chip makers targeting similar end markets.
The fair multiple model, which adjusts for Wolfspeed’s growth profile, margins, size and risk, still suggests the current 2.1x is on the expensive side of what the fundamentals might justify. That tension between a headline discount to sector P/S levels and a richer reading against a tailored fair value range is what holders need to weigh. It puts the focus back on how investors view Wolfspeed’s ability to convert its silicon carbide buildout into durable, scale economic sales. Explore the numbers behind Wolfspeed's P/S valuation.
The Wolfspeed Narrative: What Would Justify Today's Price?
Narratives pick up where Wolfspeed's valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to be worth meaningfully more or less than today. Each scenario sets out its own set of moving parts behind a fair value estimate, so you can match those assumptions against Wolfspeed's actual results as new numbers are reported.
Community views on Wolfspeed split between those who see a silicon carbide leader gearing up for a bigger payoff and others who focus on execution risk and financing costs.
Bull case: 12% undervalued
"Rising power needs from AI data centers, including the shift from 400-volt to 800-volt architectures and much higher power per rack, align directly with Wolfspeed's silicon carbide strengths, which can support higher power density and system efficiency and may support revenue growth and better factory utilization over time…"
Discover why this Narrative puts Wolfspeed at 12% undervalued.
Bear case: 5% overvalued
"Current gross margins remain negative and factory underutilization is still the main drag, so any delay in customers moving from evaluation to volume orders could limit improvement in net margins and EBITDA…"
Explore why this Narrative puts Wolfspeed at 5% overvalued.
Wolfspeed's valuation still leaves one crucial piece off the table
Before deciding how Wolfspeed fits into your portfolio, it is worth asking who is actually steering the expansion, how their incentives are structured, and whether those rewards truly line up with your interests. See who runs Wolfspeed and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com