


Oklo (OKLO) just cleared an important regulatory step, with the Nuclear Regulatory Commission approving the Principal Design Criteria for its Aurora Powerhouse small modular reactor, which is sharpening attention on the company’s commercial progress and risk profile.
Despite the regulatory win, Oklo’s recent trading has been weak, with the share price down 13.5% over the past month and 23.4% over 90 days. The year to date share price return has declined 50.8%, and the 1 year total shareholder return is down 67.9%, even after a very large 5 year total shareholder return that sits close to 3x. This suggests that recent momentum has faded as investors weigh execution risk against long term nuclear power potential.
Scan other potential nuclear power beneficiaries and grid suppliers with the curated 19 nuclear energy infrastructure stocks, which could also be shaped by the same regulatory and energy security themes influencing Oklo.
Oklo now trades far below the average analyst price target, yet expectations for future projects and cash flows remain wide open. Where does a sensible fair value range actually land after this regulatory step and sharp share pullback?
Most Popular Narrative: 52.5% Undervalued
On the most followed narrative, Oklo’s fair value sits at $80.55, more than double the last close of $38.29. This highlights how much future execution is reflected in that gap.
Oklo is another modular / small nuclear reactor maker, calling them Aurora Powerhouses. But it is not trying to sell reactors; it is trying to sell long-term electricity contracts, maintaining ownership of the plants. We are talking recurring, predictable revenue, not just selling equipment. AI data centers are relevant here and represent a potential positive factor. Oklo has already signed major agreements, for example with Switch for 12 GW through to 2044. It also recently passed a major regulatory hurdle, as the NRC (Nuclear Regulatory Commission) approved Oklo’s Principal Design Criteria for Aurora. The reactors are not fully licensed or approved yet, but this development has a significant positive impact on uncertainty.
See why 55 investors see Oklo as 52% undervalued.
Result: Fair Value of $80.55 (UNDERVALUED)
However, the Oklo story still leans on unproven commercial plants and effectively zero current revenue, so any licensing setback or contract disappointment could quickly pressure that optimism.
Find out about the key risks to this Oklo narrative.
Another View: What Oklo’s P/B Ratio Says
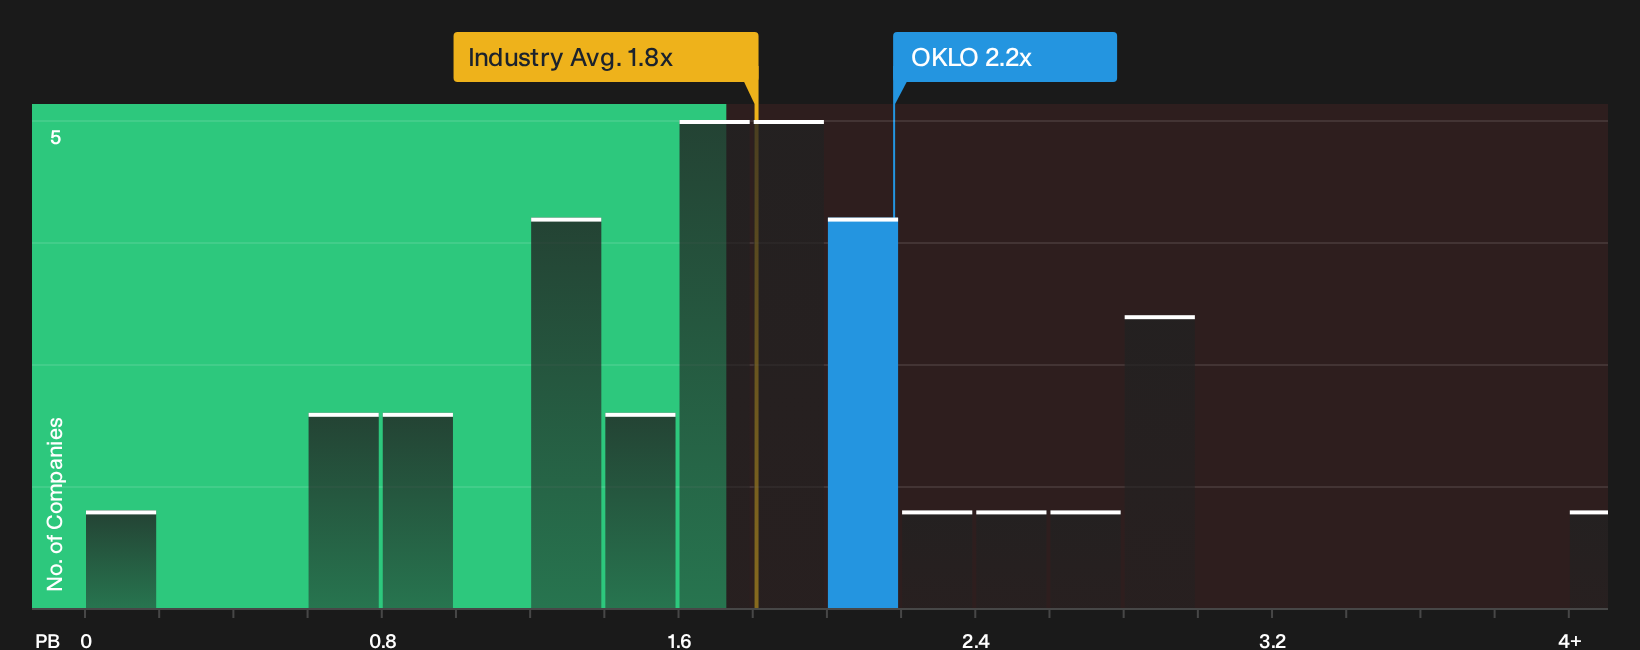
That $80.55 fair value hinges on future cash generation. A simple price to book cross check tells a harsher story. Oklo trades at a P/B of 2.2x, which is richer than both its direct peers at 1.7x and the wider US Electric Utilities group at 1.8x.
This gap means the stock already prices in more optimism than similar businesses, even though Oklo is loss making and has no meaningful revenue yet. If the story stumbles or timelines slip, there is less valuation cushion than the bullish narrative suggests. Are you comfortable paying above sector and peer levels for a concept that is still being proved?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Oklo can easily pull you in either direction, so move quickly, review the evidence yourself, and weigh both sides. To see the full balance of potential upside and the issues investors are watching, start with the 1 key reward and 6 important warning signs.
Looking for more investment ideas beyond Oklo?
If Oklo has your attention, do not stop there. Use the screener to identify other opportunities before they move beyond your reach.
- Target resilient compounding potential by scanning companies with dependable balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by checking the 30 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- Prioritize resilience by reviewing the 30 resilient stocks with low risk scores that aim to limit downside while still allowing for potential returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com