


Southern (SO) slipped 1.97% in the latest session, lagging the broader market as traders weighed an upcoming earnings release with EPS projected to increase 3.13% and refreshed analyst estimates suggesting a shifting outlook.
That 1.97% pullback adds to a weaker stretch for Southern, with the share price down 4.46% over the past week and 7.87% over the last month, while the 1-year total shareholder return is down 8.61% but the 5-year total shareholder return is up 60.58%. This suggests long-term holders have still seen substantial value creation even as short-term momentum has faded ahead of the upcoming earnings update.
Look beyond Southern's recent pullback and upcoming earnings to identify potential alternatives in utilities and other sectors with the hand picked 30 resilient stocks with low risk scores.
After a pullback that erased a chunk of recent gains but left long term returns firmly positive, the question for Southern now is whether the current price still compensates you for the risks on the table.
Most Popular Narrative: 17% Undervalued
Southern's most followed valuation story pegs fair value at $99.76, which sits well above the latest close at $82.89 and puts the focus squarely on whether its long term projects and contracts can justify that gap.
Accelerating large load and data center activity in Southern’s territories, including more than 17 GW of contracted large load agreements for the mid 2030s, a late stage pipeline of about 8 GW and a prospective funnel above 75 GW, points to a long runway of usage driven revenue and regulated rate base growth that may not be fully reflected in current valuation.
See why 63 investors see Southern as 17% undervalued.
Result: Fair Value of $99.76 (UNDERVALUED)
Still, Southern’s story can crack if large load contracts ramp more slowly than expected or if heavy capital spending and equity issuance dilute per share results.
Find out about the key risks to this Southern narrative.
Another Take On Southern’s Valuation
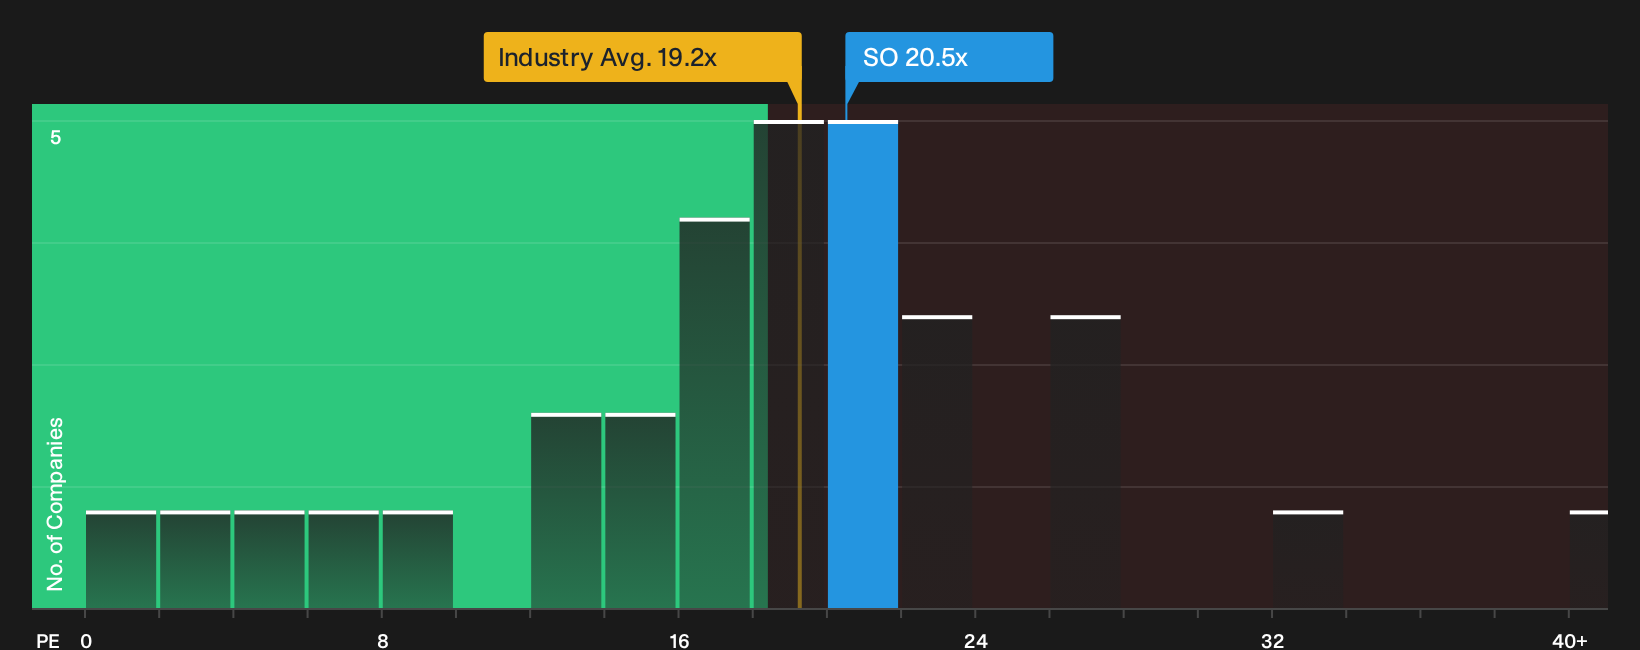
The analyst fair value story for Southern leans on future earnings. A simpler yardstick, the current P/E of 20.5x, tells a different story. That multiple is richer than the US Electric Utilities industry on 19.2x and slightly above peers at 20.3x, yet below the fair ratio of 23.5x. This suggests investors are already paying up for quality but not to an extreme. The gap between today’s P/E and that fair ratio reflects a mix of downside risk if sentiment cools and upside if the market leans further into the story. Which side of that trade-off fits your own risk comfort?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Southern's valuation and risk profile can feel messy, so move quickly, review the numbers, and pressure test the story yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Southern?
If Southern no longer feels like the only place to focus fresh capital, broaden your watchlist with targeted screeners that surface specific strengths across the market.
- Hunt for quality on sale by checking the 30 high quality undervalued stocks that combine solid fundamentals with attractive pricing.
- Strengthen your income base by scanning the 7 dividend fortresses that aim to pair higher yields with durable businesses.
- Prioritize resilience by working through the list of solid balance sheet and fundamentals (24 results) so you are not caught off guard when conditions turn rough.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com