


Global bond yields have surged to multi decade highs, lifting borrowing costs and squeezing weaker balance sheets. For Canadian penny stocks with cleaner finances, this tougher backdrop can filter out the more fragile stories and leave a smaller group of potentially resilient candidates. This article unpacks three financially solid low priced Canadian stocks that passed a strict quality screen, so you can decide which, if any, deserve a closer look.
The three examples below are only a small sample, as the full screen surfaced 347 more financially fit penny stocks with equally compelling narratives that are not covered here. To go straight to the source, use the Financially Fit Penny Stocks screener to identify, filter, and analyze the highest conviction ideas that match your own criteria.
Cronos Group (TSX:CRON)
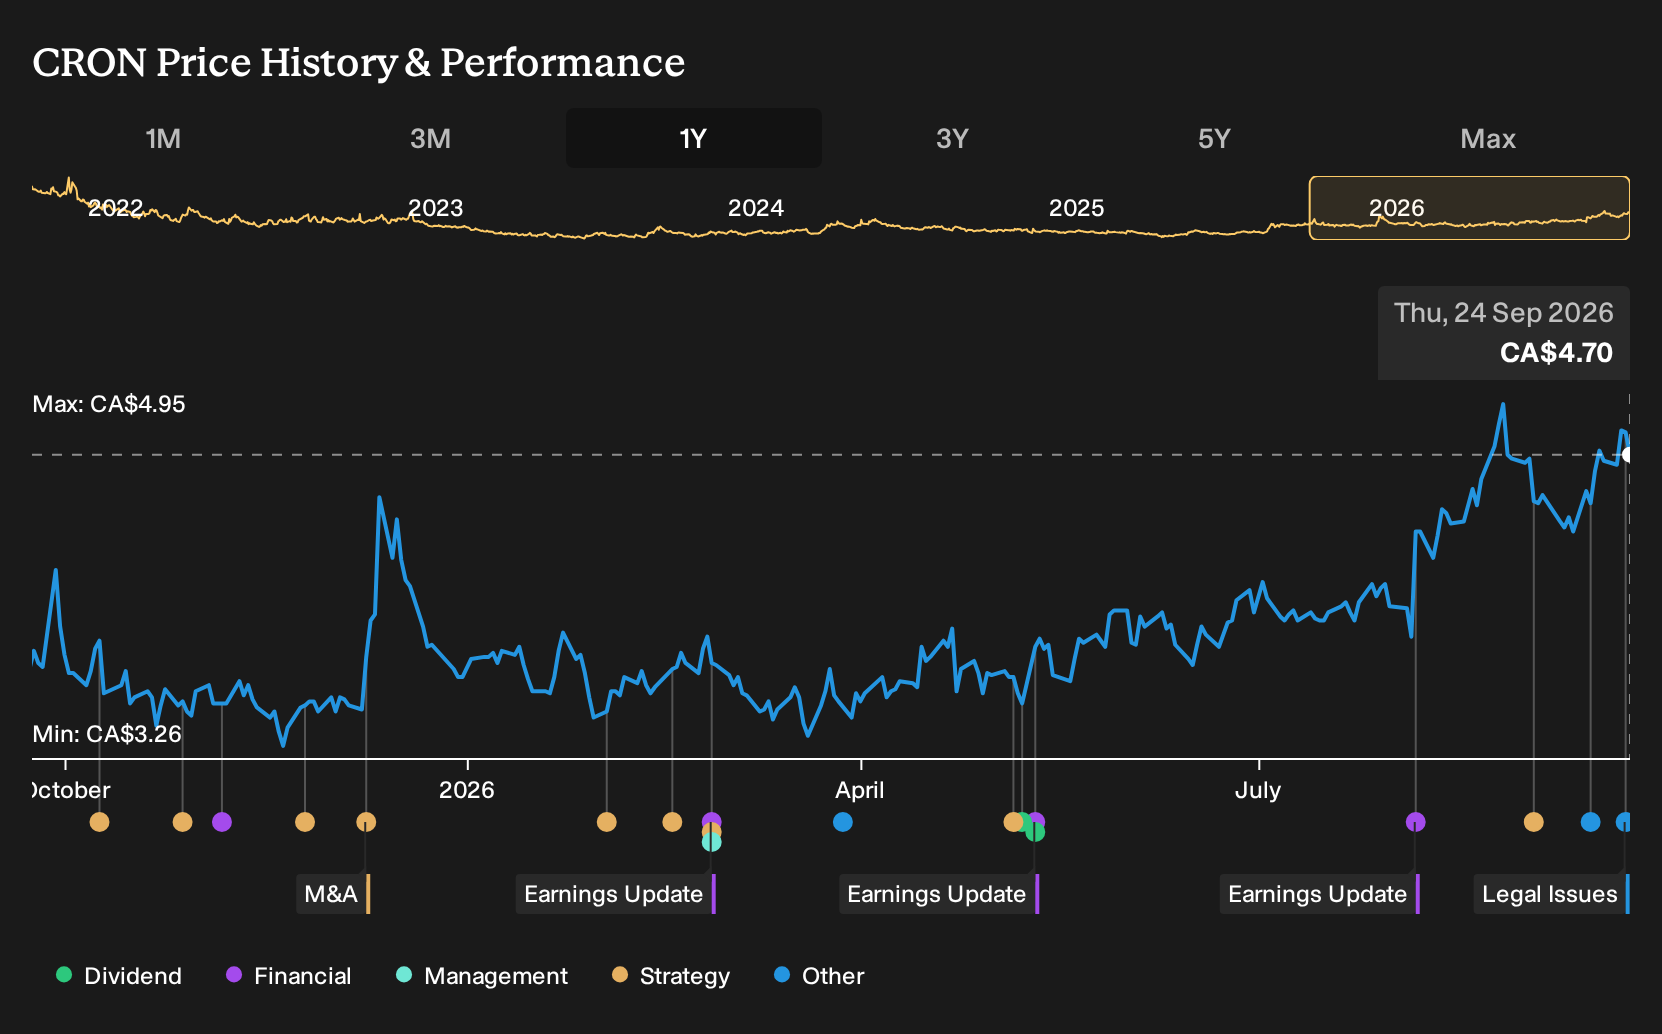
Cronos Group is a cannabinoid producer that fits the Financially Fit Penny Stocks theme through its revenue generating cannabis products sold under consumer brands like Spinach, Lord Jones, Lit, and Peace Naturals.
Cronos Group generates about $179 million from cultivating, manufacturing, and marketing cannabis and cannabis derived products, with sales spread across Canada, Israel, and other countries. The stock carries a market value of roughly $1.8b.
Cronos Group gives this screener a real business attached to a low priced share, with branded cannabis products already supporting earnings, cash returns, and a more resilient balance of risk and reward than many early stage peers.
"The strength and breadth of premium brands (Spinach, Lord Jones, PEACE NATURALS) across flower, vapes, edibles, and concentrates, coupled with industry-leading market shares in high-margin categories, point to sustainable pricing power and enduring consumer loyalty, supporting continued gross margin improvement and resilient long-term earnings growth."
The real test for Cronos Group is how one unresolved pressure on its cost of capital and funding mix shapes those margin ambitions over time.
That funding question is where things get interesting, and the full narrative for Cronos Group explains how Cronos Group could convert its brand strength into accelerating scale while that capital overhang slowly clears.
Omai Gold Mines (TSXV:OMG)
Omai Gold Mines focuses on acquiring and developing gold properties, anchored by its 100%-owned Omai prospecting license in Guyana, a single exploration asset that fits the Financially Fit Penny Stocks theme by tying future potential to a defined project. The business has a market value of about CA$1.7b.
Omai Gold Mines links a penny stock price to a single, tangible gold project that already has drilling momentum and a place in a junior gold ETF. Together, these factors can help support financial resilience for an early-stage explorer. The big unknown is how long funding holds up if that one pressure point tightens further.
If that funding window tightens further, the 1 key reward and 5 important warning signs (3 are major!) shows where Omai Gold Mines could accelerate or stall long before the market reacts.

McChip Resources (TSXV:MCS)
McChip Resources is a Toronto based resource investor with petroleum interests, mineral holdings and a stake in the Saskatchewan potash project. It generated about CA$3.6 million from oil and gas exploration and production in Canada and carries a market value of roughly CA$4.3 million.
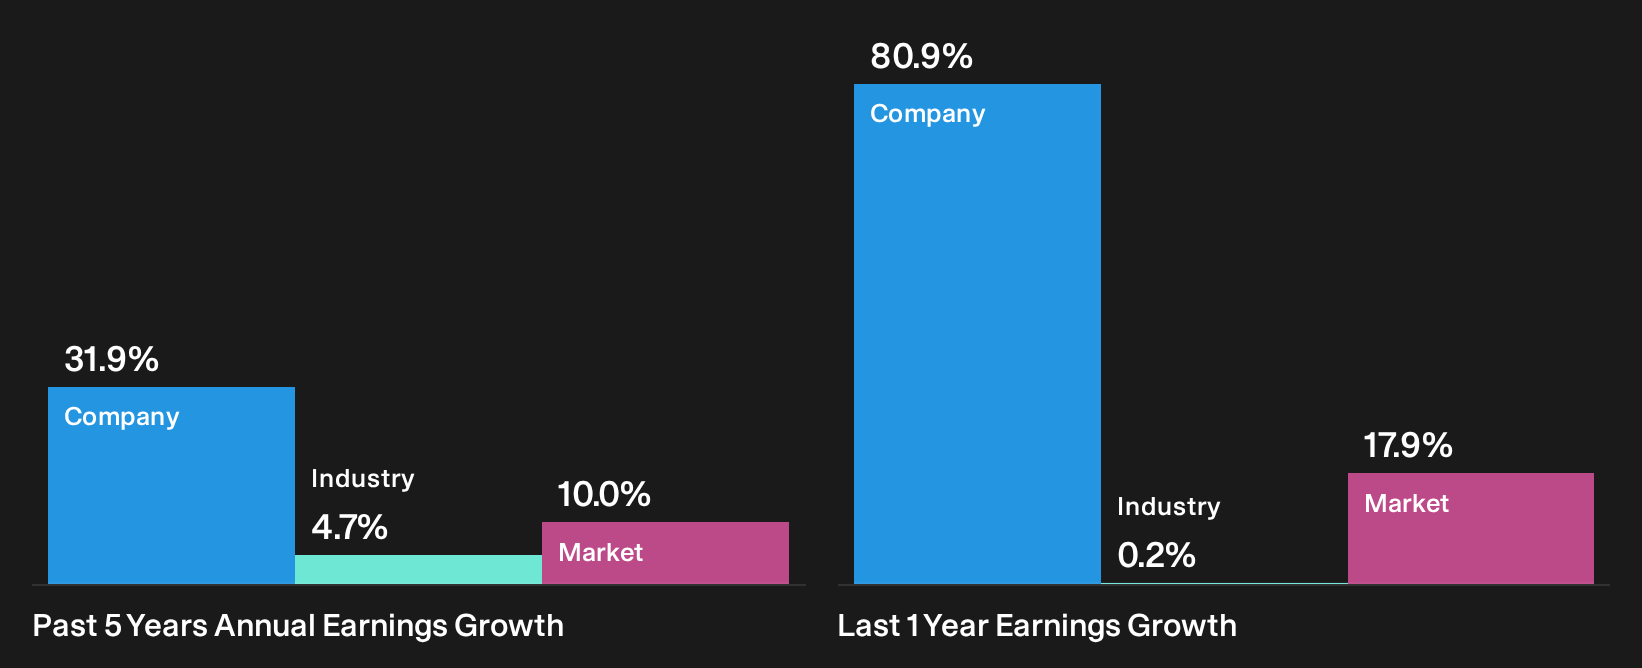
McChip Resources gives this penny stock screen a small, asset backed resource play, with earnings growth of 80.9% over the past year and net margins of 66.6% earlier in the track record. This points to past profitability that many tiny explorers never reach. The unresolved question is how that picture changes if one pressure around funding and dividend coverage tightens further.
That pressure point is exactly why the 2 key rewards and 3 important warning signs could be useful, before any shift in funding or payouts starts showing up in headlines.
Seeking Fresh Alternatives Before Everyone Else
Markets move fast and the first breakout waves rarely wait. Momentum, cash flows, and balance sheets can be flying or dropping before the crowd reacts. Check fresh ideas while it matters and get in early.
- Spot income workhorses that aim to keep paying through cycles by scanning the 1 dividend fortresses before yields get caught by late demand.
- Track the digital rails behind crypto momentum by reviewing the 21 cryptocurrency and blockchain stocks while many of these operators stay under the radar for now.
- Hunt for resilient growers with balance sheets built for shocks by using the 8 resilient stocks with low risk scores before defensive capital chases the same tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com