


- NFI Group subsidiary New Flyer of America announced that Houston METRO ordered 100 Xcelsior 40-foot compressed natural gas buses for approximately US$93 million, with funding supported by the FTA's 2025-2026 Low-No Program and Bus and Bus Facilities Projects, and the order added to NFI's firm backlog in Q2 2026.
- This contract extends a relationship with METRO that has been in place since 1991 and reinforces NFI Group's role as a supplier of lower-emission buses to a large, high-usage transit system, where bus service accounts for most of the ridership across roughly 1,300 miles of coverage.
- We will now look at how NFI Group's investment narrative could be influenced by the Houston METRO CNG order and related funding support.
NFI Group Investment Narrative Recap
NFI Group appeals to investors who believe that long term transit funding, a record multiyear backlog and operational tightening can support healthier cash generation. The Houston METRO CNG order adds to that contracted base and points to steady manufacturing activity, but it does not radically change the near term story on its own.
The biggest short term catalyst still revolves around turning that backlog into consistent free cash flow while interest costs remain a drag. High leverage and interest payments that are not well covered by earnings keep financial risk elevated, so execution on deliveries and margin discipline matter more than any single contract win.
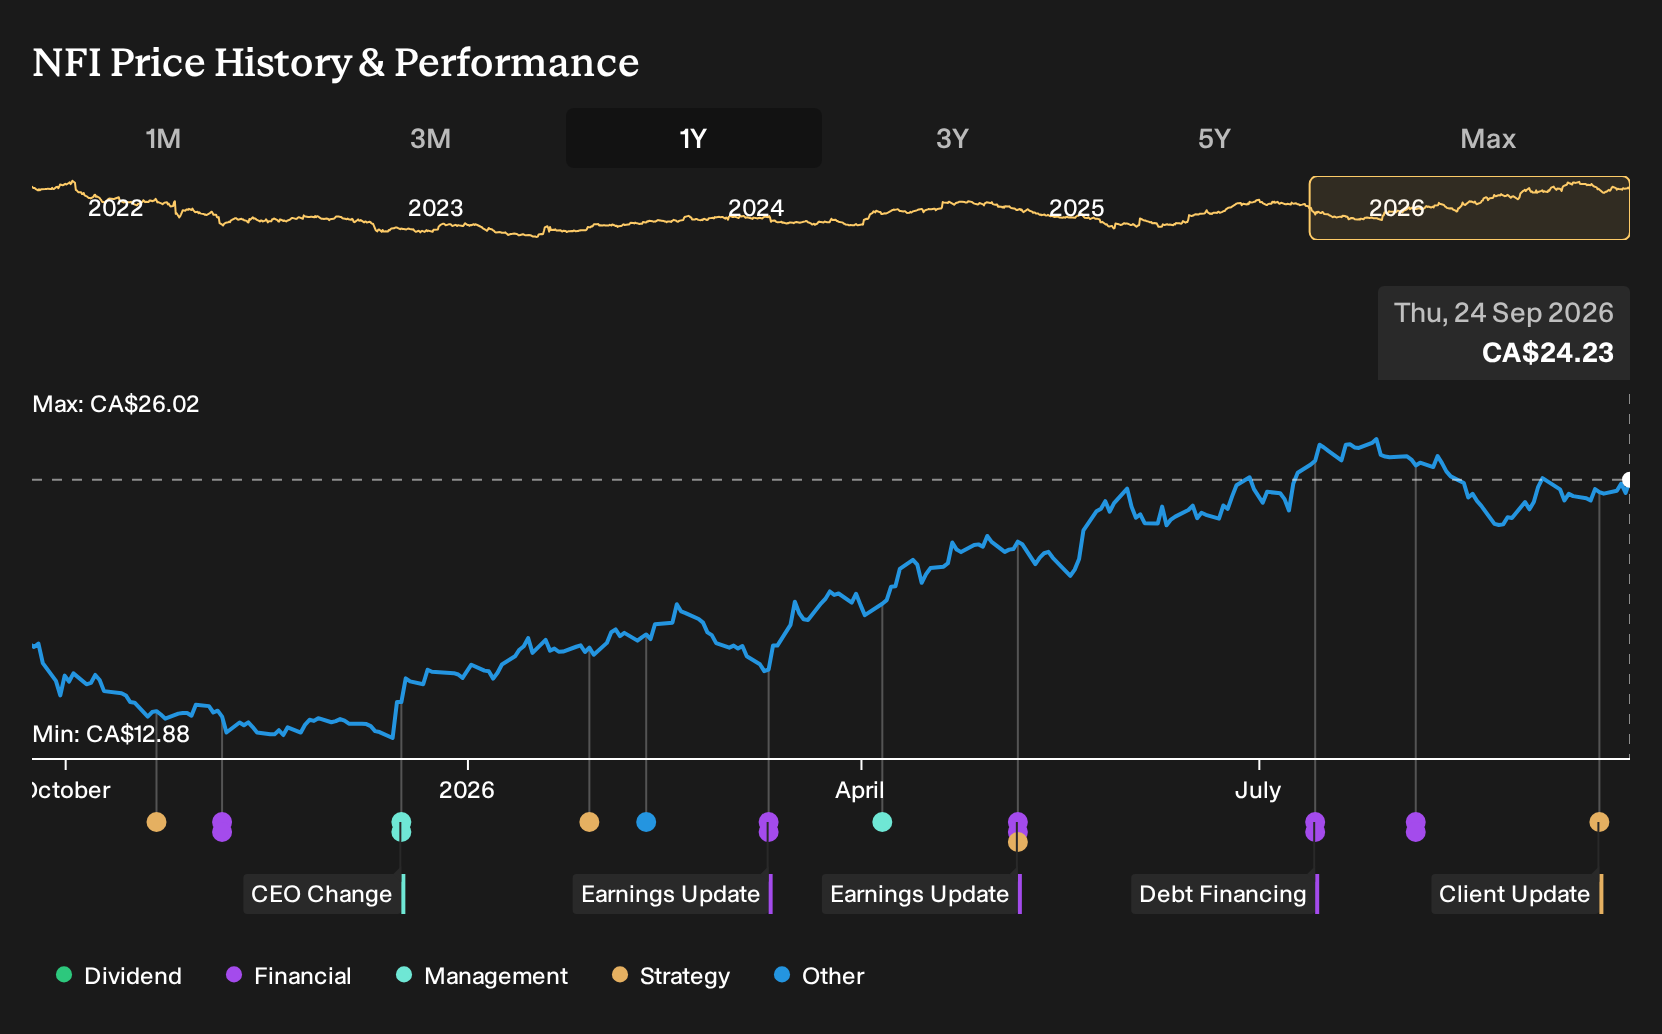
A recent update indicates that a Discounted Cash Flow model suggests NFI Group’s intrinsic value sits well above the current share price, which may shape how investors interpret the METRO deal. Reliable contract revenue and clearer cash inflows from large clients can support those long term free cash flow assumptions if production and delivery stay on track.
For catalysts, the METRO award links directly to the broader theme of multiyear government backed transit spending and NFI’s sizeable backlog. The key operational question for shareholders is whether management can convert that order book into higher quality earnings while managing debt, tariffs and competitive pressure in markets such as the U.K. without eroding margins.
NFI Group's narrative projects $4.7 billion revenue and $296.1 million earnings by 2029. This assumes 7.9% yearly revenue growth and an earnings increase of about $242 million from $54.0 million today.
Uncover why NFI Group's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate story for NFI Group leans hard on execution risk. The most bearish analysts focus on the long recall program and supplier constraints, and were already penciling in about $4.6b of revenue and $286.6 million of earnings by 2029. That is more cautious than consensus. The Houston METRO order could push some of those views to evolve, so treat this as a prompt to explore a wide range of opinions rather than a single “right” take.
Explore 3 other NFI Group fair value estimates, including one that suggests it could be worth just CA$28.49.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your NFI Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NFI Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NFI Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond NFI Group?
If NFI Group has sharpened your interest in infrastructure and cash flow driven stories, it can help to line it up against a broader watchlist of opportunities. The Simply Wall St Screener lets you filter for different financial traits so you can quickly spot which listed businesses deserve a closer look.
- If you want potential mispricing with stronger fundamentals, start with companies that screen well on cash generation and valuation through the 5 high quality undervalued stocks.
- If reliable income matters more to you than headline growth, narrow your research to payouts above 5% using the 1 dividend fortresses.
- If capital preservation is the priority, focus on businesses with sturdier finances and lower risk scores via the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com