


Chemed has had a mixed run in recent months, and the question now is whether the current share price lines up with the cash flows that underpin the business. With a fresh acquisition in its Roto-Rooter unit and a stock that has moved around this year, investors are being asked to reassess what those cash flows might be worth.
- Chemed shares are up 17.0% year to date, which puts more focus on whether the underlying cash generation can support that kind of move.
- Roto-Rooter’s purchase of its largest independent franchise territory may support expectations for future cash flows by pulling more of the plumbing and drain cleaning economics directly onto Chemed’s books.
- Prefer to judge Chemed on earnings? See why Chemed's 23.5x P/E tells a different valuation story.
The issue now is whether Chemed's current market price is adequately explained by the cash flows implied in a Discounted Cash Flow (DCF) view of the business.
If you are weighing Chemed against other cash flow focused ideas, it can help to compare it with companies flagged in the 30 high quality undervalued stocks
Does Chemed Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here uses Chemed’s future cash generation to anchor an estimate of what the shares might be worth. Latest twelve month free cash flow sits at about $331.2 million, with the projections assuming Chemed continues to produce growing but relatively measured free cash flow over the coming decade rather than rapid expansion.
Those steady cash assumptions still put the DCF estimate meaningfully above the current share price of $495.65. Because Roto-Rooter’s purchase of its largest franchise territory brings more of that plumbing and drain cleaning activity in house, the deal helps explain why a cash flow model can justify a value above where the equity trades today. Find out what Chemed could be worth using our Discounted Cash Flow (DCF) estimate.
The Chemed Narrative: What Would Justify Today's Price?
Narratives pick up where the DCF puzzle for Chemed leaves off. They spell out which paths for revenue, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s price, and they sit on Simply Wall St’s Community page. Each one presents Chemed's implied value as a thesis about the business that can be tracked over time rather than a single static snapshot.
One of the top community narratives on Chemed: 10% undervalued
"Chemed’s use of strong operating cash flow, minimal leverage, and a long history of returning capital to shareholders provides ongoing scope to compound earnings per share..."
Discover why this Narrative puts Chemed at 10% undervalued.
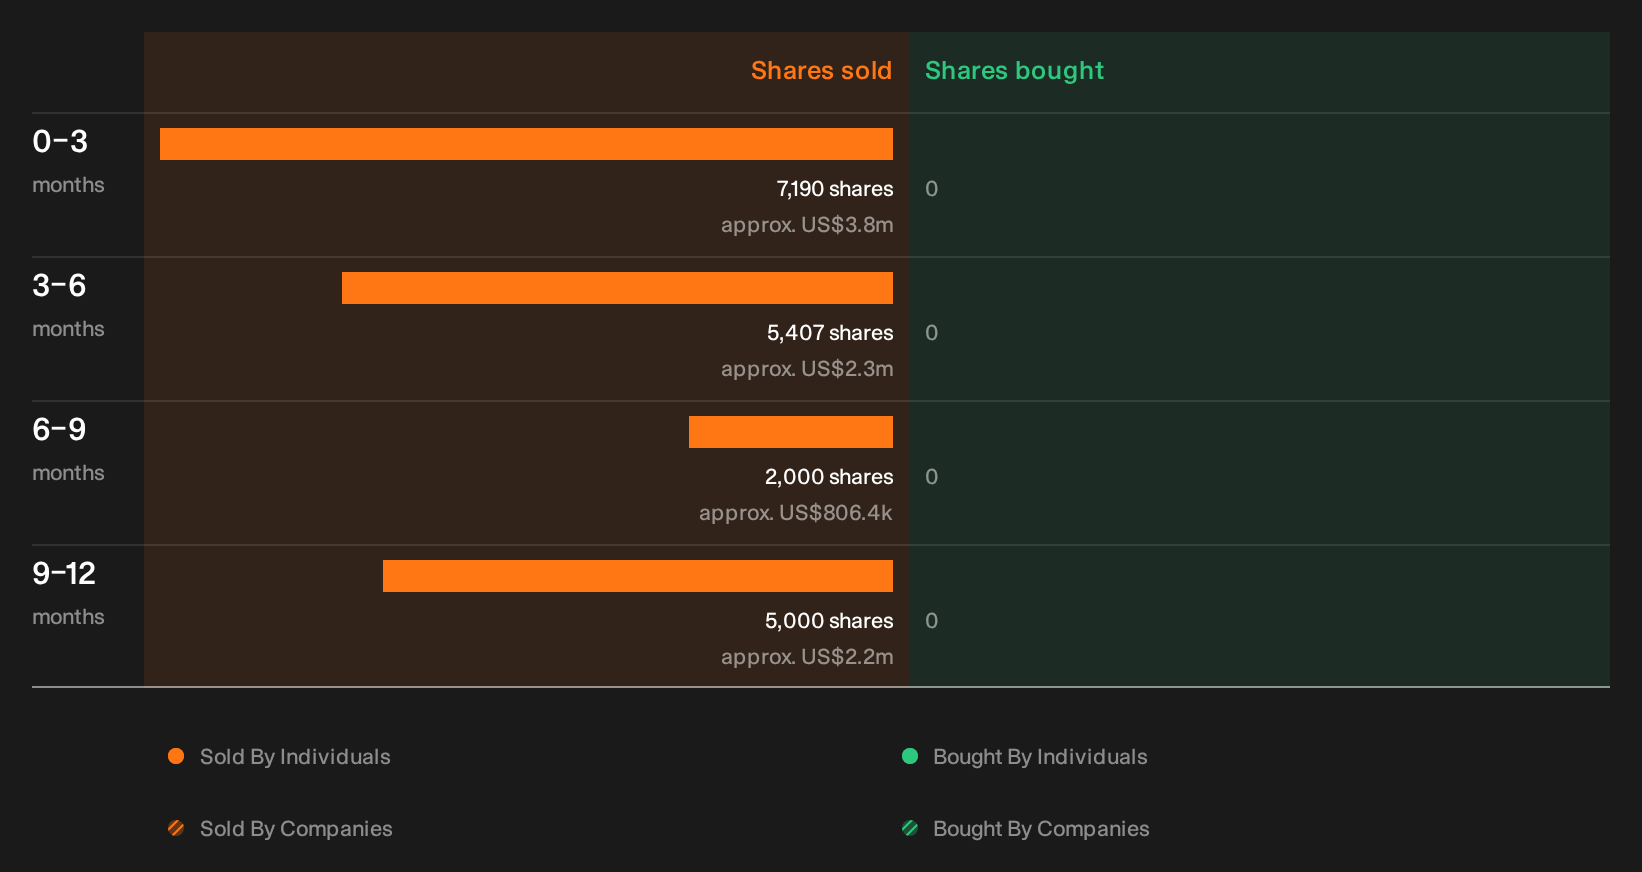
The Chemed story also hinges on who is selling
Price and cash flows only tell part of Chemed’s story. Recent transactions by people inside the business have been flagged by our checks, and the individuals, volumes and potential signals are there for you to inspect. See the recent insider selling flagged for Chemed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com