


Skyworks Solutions has seen its share price move around sharply in recent years, and the question for anyone looking at the stock now is whether the current level around US$87.81 is adequately supported by its earnings power. With the business also working through a major transaction, the link between the share price and the underlying profit stream is front of mind.
- Over the past 5 years the stock has fallen 38.6%, which puts a spotlight on whether the earnings profile today lines up with where the market is pricing the business.
- The planned merger with Qorvo and related exchange offers for Qorvo’s senior notes may reshape Skyworks Solutions’ scale, capital structure and future cash flows, which can all feed directly into how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on Skyworks Solutions worth weighing. See what analysts think Skyworks Solutions's shares could be worth.
The issue now is whether the current share price is justified by Skyworks Solutions’ earnings when set against the Fair Ratio benchmark.
For context on how Skyworks Solutions compares in this earnings-focused story, it can help to line it up against 30 high quality undervalued stocks.
Does Skyworks Solutions Look Pricey on Earnings?
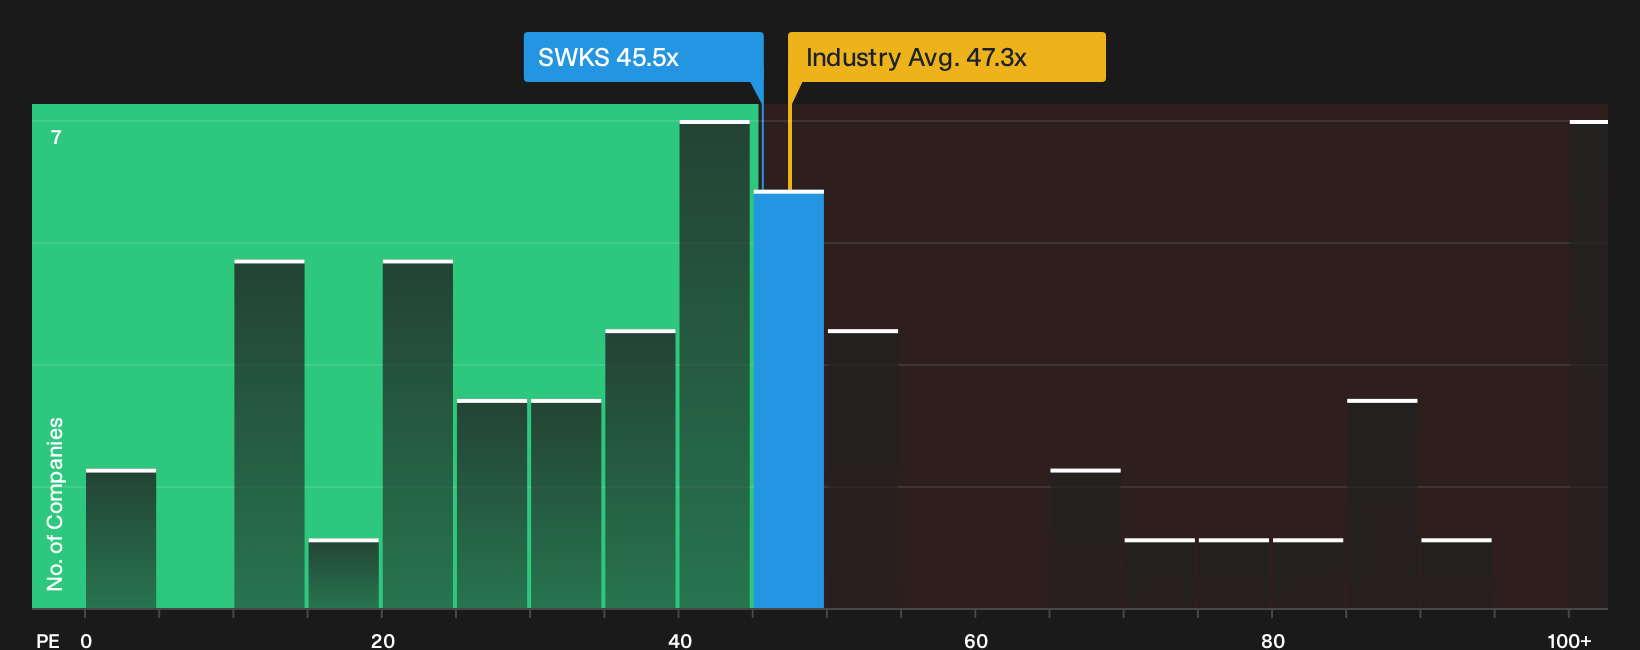
A P/E lens fits Skyworks Solutions because earnings are still a key reference point for how the market weighs its cash generation potential. On that metric, the stock trades on a P/E of about 45.5x, which is slightly below the broader semiconductor sector average of roughly 47.3x and under the peer group level near 53.2x.
Despite the ongoing Qorvo merger process and related note exchange offers, investors are still paying a P/E that sits above the level suggested by a tailored Fair Ratio model that adjusts for Skyworks Solutions’ growth profile, margins, size and risk. That gap points to a valuation that screens as overvalued on this earnings yardstick, so anyone looking at the shares now would need strong conviction that the combined business will justify paying a richer multiple than the Fair Ratio implies. Explore the numbers behind Skyworks Solutions's P/E valuation.
The Skyworks Solutions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Skyworks Solutions valuation puzzle leaves off, spelling out which paths for growth, profitability and earnings power would need to occur for today’s share price to look either too low or too rich. Rather than relying on a single multiple or one model result, each scenario lays out the assumptions that sit behind its view of fair value so you can compare those expectations with the company’s reported numbers over time.
One of the top community narratives on Skyworks Solutions: 28% overvalued
"The current valuation implies the market is already pricing Skyworks Solutions for successful execution on RF content growth, broad market expansion and merger synergies…"
Discover why this Narrative puts Skyworks Solutions at 28% overvalued.
One more Skyworks Solutions checkpoint that sits beyond today’s share price
Price multiples tell you what the market is paying today, but the projections that analysts publish for Skyworks Solutions a few years out give you a different lens on what that price might be assuming. Explore where analysts expect Skyworks Solutions to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com