


Bond yields are surging, oil is above US$100 a barrel, and cash suddenly looks less like dead money and more like a real decision point. That shift is pulling attention toward short-duration fixed income and money-market fund providers exposed to these rate moves. This article unpacks how that backdrop connects to three specific stocks and why understanding their stories could help you decide where to lean in or hold back.
The stocks covered below are just a sample of the idea. The full screen surfaced 20 more short-duration fixed income and money-market fund providers with equally compelling stories that are not covered here. To identify and analyze the highest conviction opportunities in this space, head straight into the Short-Duration Fixed Income and Money-Market Fund Providers screener.
Raymond James Financial (RJF)
Raymond James Financial sits at the crossroads of wealth management, banking and asset management, which puts its cash sweep and money-market channels squarely in focus when investors care more about capital preservation and short-duration income.
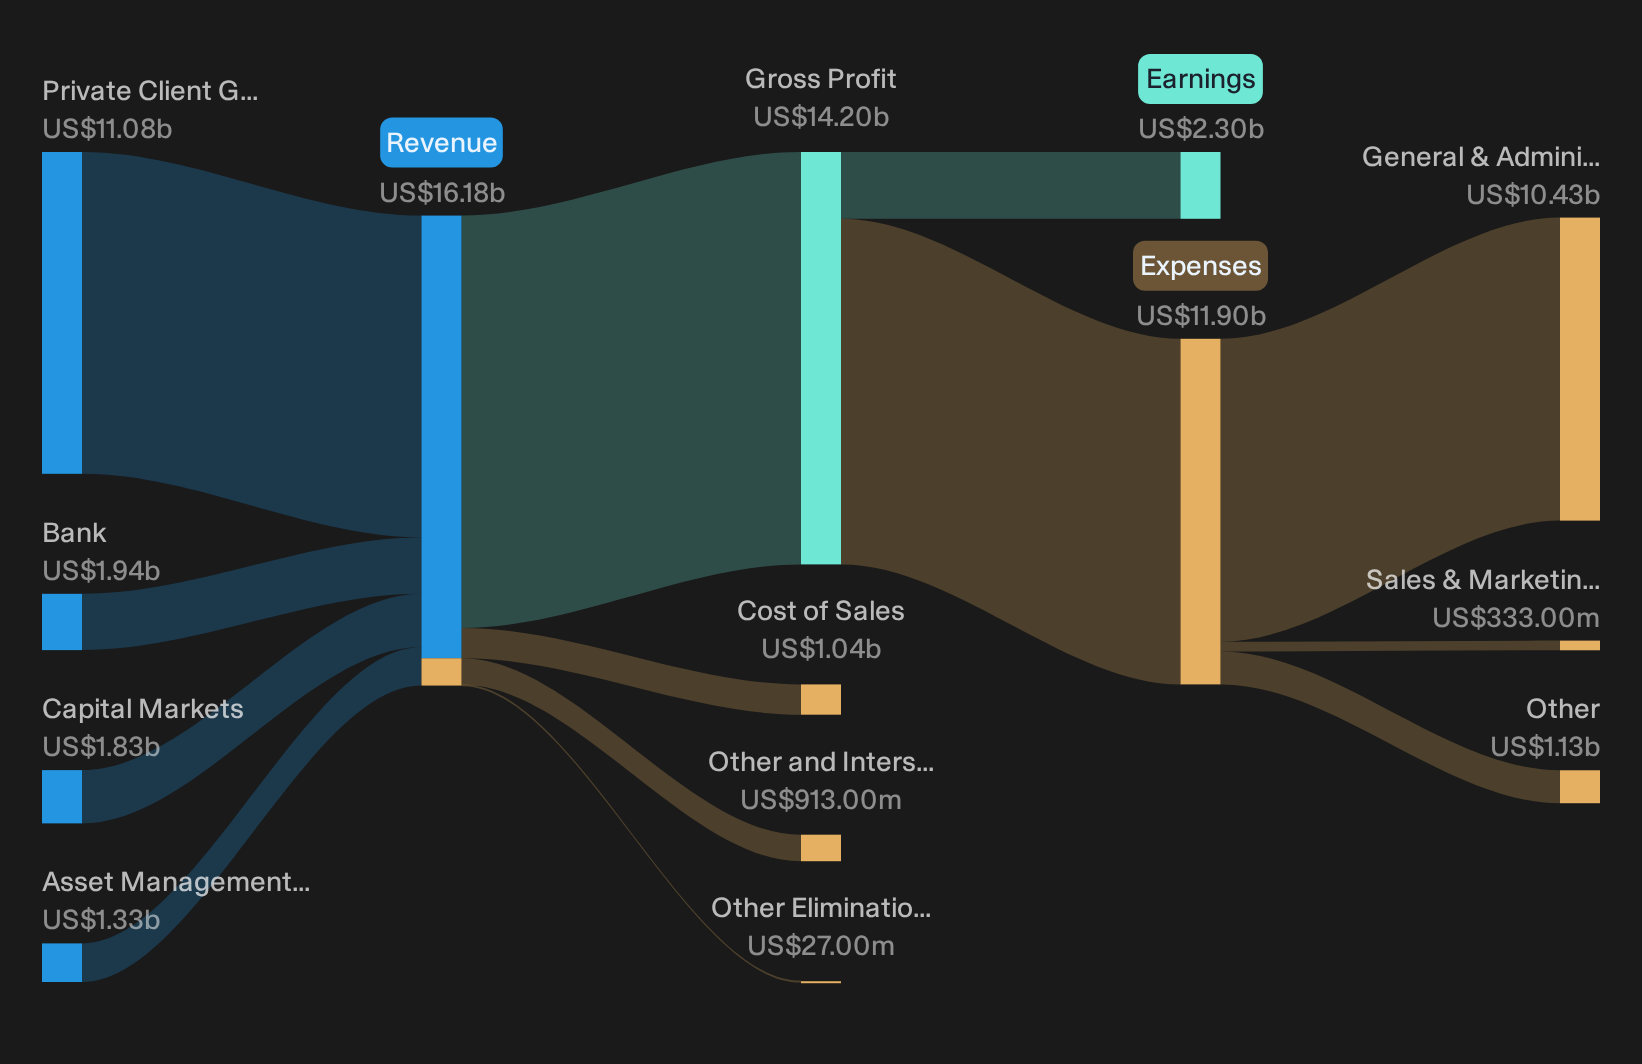
Raymond James Financial runs a diversified, advice-led platform. The Private Client Group generates about US$11.1b of its roughly US$15.3b in segment revenue, with smaller contributions from banking, capital markets and asset management. The group is valued at about US$30.4b in the equity market.
The build out of firmwide artificial intelligence capabilities, including more than US$1.1b in annual technology spending, the rollout of the Raimond AI assistant with a reported 99.5% satisfaction rate among 6,500 users, and broad training through the AI Academy, is expected to drive productivity gains that could support net margins.
What happens if one less visible pressure on Raymond James Financial’s balance between client cash flows and fee-based assets shifts more sharply than expected?
If that cash mix starts to decouple, read the full narrative for Raymond James Financial to see how Raymond James Financial’s model could absorb the shock and to identify where growth pressure may be building.
DWS Group GmbH KGaA (XTRA:DWS)
DWS Group GmbH KGaA is a Frankfurt based asset manager that runs everything from cash and short-duration bond funds to real estate and private equity, with its €4.8b Asset Management segment driving the business and the stock valued at about €14.2b.
DWS Group taps directly into the screener theme because it packages short-duration and cash-like products for clients who want capital preservation while yields are high, and management has been leaning into that toolkit rather than pulling back.
The expansion of DWS's Xtrackers ETF and Alternatives businesses taps directly into the growing global middle class and rising wealth, particularly in Asia and emerging markets, which is fueling strong demand for scalable, diversified investment solutions; this is poised to drive higher net flows and management fee revenue, counter to perceptions of a weak growth outlook.
What investors still have to weigh is how one quiet shift in the mix of those flows could reframe the debate around DWS Group’s earnings power.
That mix shift is where the story gets interesting, and the full narrative for DWS Group GmbH KGaA explains how DWS Group GmbH KGaA’s fee engine could accelerate or stall from here.

Northern Trust (NTRS)
Northern Trust plugs directly into the short duration and money market theme through its custody, cash management and fixed income funds for institutions and wealthy families. It also runs a large wealth unit and a broad asset servicing arm, making it a diversified fee engine.
Northern Trust generates about US$5.2b from Asset Servicing, US$3.5b from Wealth Management and US$400.7m from Other activities, with a market value of roughly US$31.8b.
Northern Trust’s appeal in this screen comes from how its cash and short term fixed income franchises intersect with a tougher rate backdrop, and how that intersection ties back to higher value services for large asset owners.
Alternative assets under administration now exceed US$1t, with new semi liquid mandates and a roughly 50% quarter over quarter rise in hedge fund launches in Q2 2026. This suggests an expanding fee pool from complex asset servicing that can influence future revenue and margins.
The real swing factor is what happens to Northern Trust’s earnings power if pricing pressure creeps into those cash heavy liquidity solutions just as costs reset.
If that pricing risk is what you are focused on, the full narrative for Northern Trust explains how Northern Trust’s short duration engine could quietly re rate.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time momentum headlines hit, early entries are already flying. Scan these under the radar lists while it still matters and get in early.
- Target sturdy cash generators with resilient balance sheets before the crowd notices the list of solid balance sheet and fundamentals (24 results) hiding in plain sight.
- Spot early trend leaders in automation by running through the curated 93 robotics and automation stocks before valuations catch the breakout momentum.
- Position ahead of the next AI build out cycle by checking the hand picked 84 AI infrastructure stocks while it remains under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com