


With a market cap of $12.2 billion, Hasbro, Inc. (HAS) is a global play and entertainment company built around a portfolio of iconic toy, game, and entertainment franchises. Its brands include MAGIC: THE GATHERING, Dungeons & Dragons, Monopoly, Nerf, Transformers, Play-Doh, and Peppa Pig. Based in Pawtucket, Rhode Island, the company operates through four segments: Consumer Products, Wizards of the Coast, Digital Gaming, and Entertainment.
Companies worth $10 billion or more are generally described as “large-cap” stocks, and Hasbro fits this criterion perfectly. Its franchise-first strategy allows the company to monetize these brands across toys, tabletop and digital gaming, entertainment, and licensing, creating multiple revenue streams from the same intellectual property. Its growing digital gaming and licensing businesses, particularly Wizards of the Coast, further diversify the company beyond traditional toys and provide opportunities for recurring, higher-margin revenue.
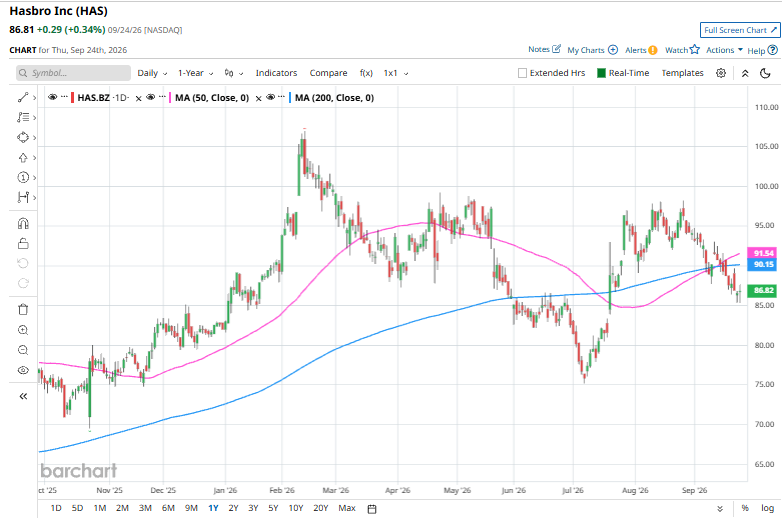
Hasbro’s stock has had a bumpy ride, retreating 18.9% from its 52-week high of $106.98. Over the past three months, shares of HAS have gained 4.2%, underperforming the S&P 500 Index’s ($SPX) 4.7% rise.
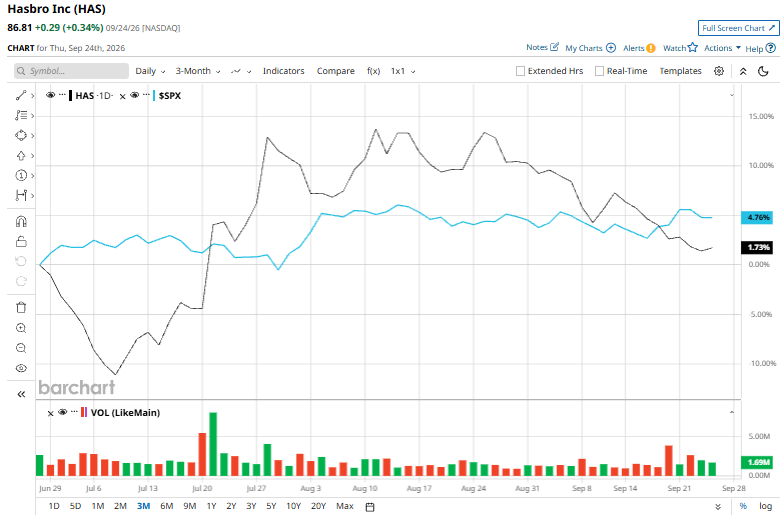
Hasbro has delivered solid gains over the longer term, but the broader market has pulled further ahead. HAS is up 5.9% year to date, compared with the S&P 500’s 12.5% advance, and its 15.4% 52-week gain trails the index’s 16.7% rise.
Hasbro’s technical momentum has lost its footing, with shares recently slipping below both the 50-day and 200-day moving averages, signaling a shift toward a downtrend.
Hasbro’s underperformance over the past year reflects sluggish top-line growth, weaker profitability, and modest earnings expansion. Revenue has declined 3.5% annually over the past five years, suggesting its portfolio has struggled to consistently generate growth. Meanwhile, an operating margin of 9.7% trails the industry average, pointing to pressure from its cost structure. Earnings growth has also been relatively muted, with EPS increasing just 2.7% annually over the past five years, leaving Hasbro with less earnings momentum than its broader industry peers.
Hasbro has significantly outpaced rival Mattel, Inc. (MAT), with the performance gap widening across both time frames. MAT stock has decreased 33.8% on a YTD basis and 23.3% over the past 52 weeks.
Due to Hasbro’s outperformance, analysts are strongly optimistic about its prospects. The stock has a consensus rating of “Strong Buy” from the 14 analysts covering it, and the mean price target of $109.71 represents a premium of 26.4% over the current market prices.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.