


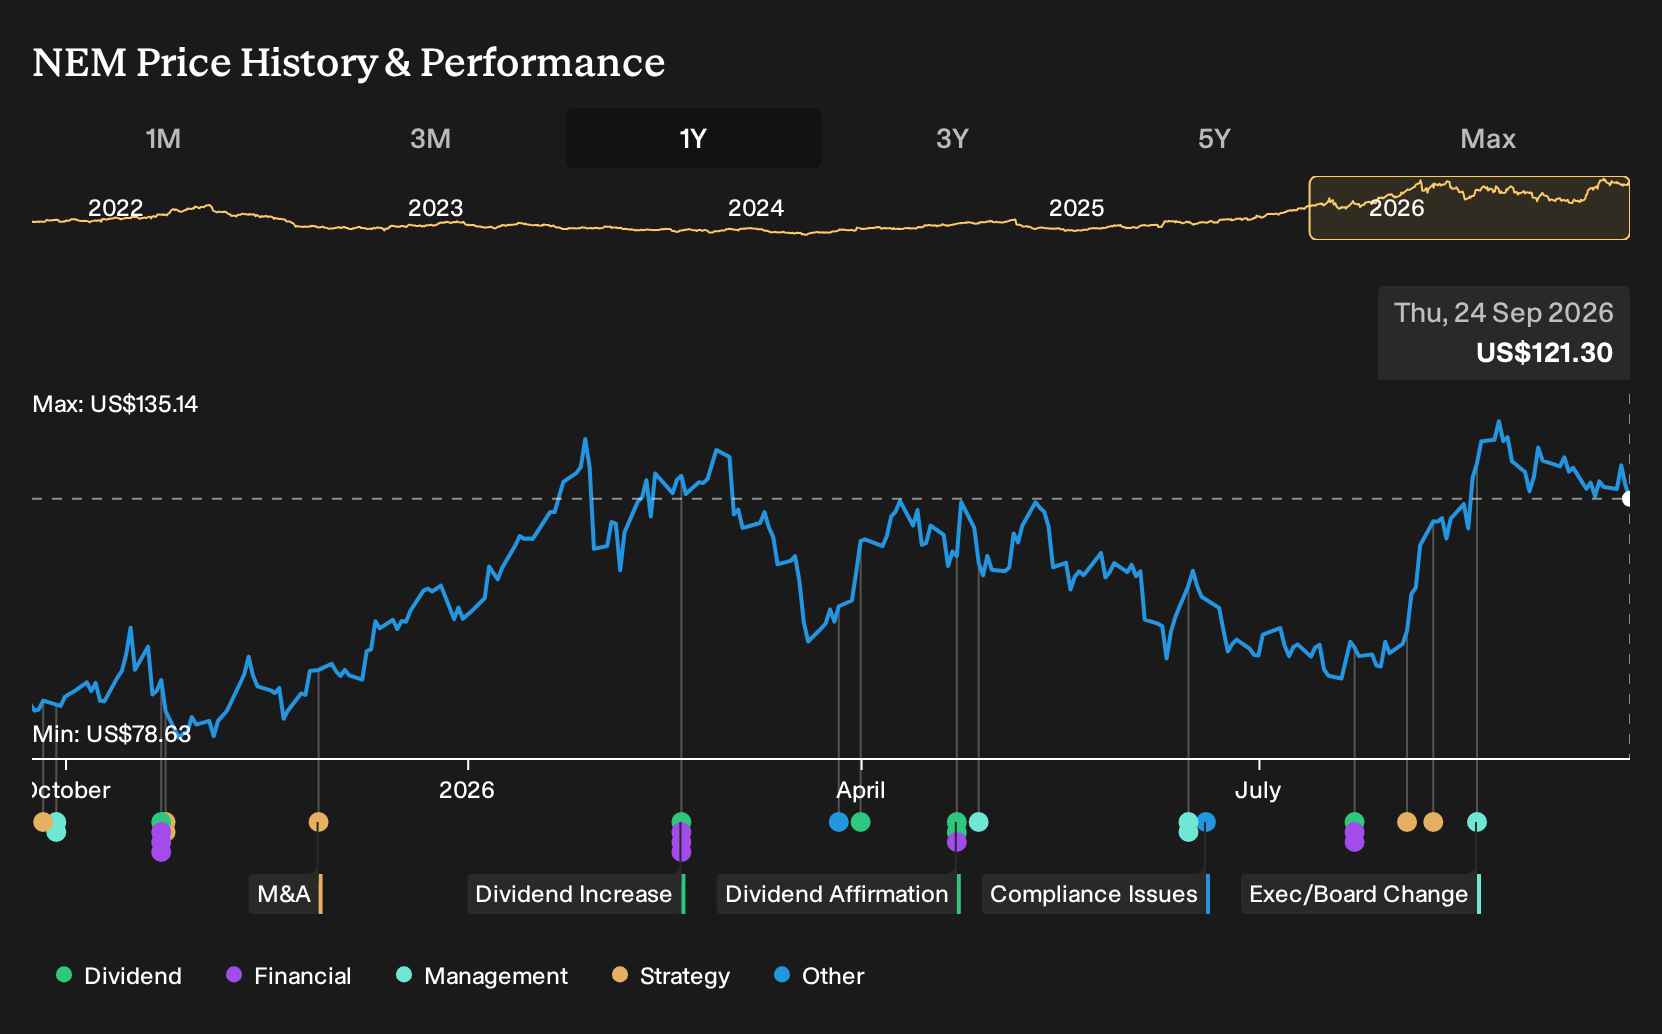
- Newmont recently saw pressure after gold prices fell below $4,350 an ounce following hawkish Federal Reserve commentary, a shift that directly affects the miner's earnings and cash generation given its heavy exposure to bullion-linked revenue.
- The move in the gold price comes just as analysts anticipate higher earnings per share and revenue for Newmont, sharpening the focus on how sensitive its operating results remain to metal pricing even when core production and assets look relatively well positioned.
- We will look at how Newmont's investment narrative holds up when gold prices weaken after hawkish Federal Reserve signals hit bullion.
Scan 36 elite gold producer stocks to see how other gold producers are reacting to the same Fed-driven pressure that just hit Newmont.
Newmont Investment Narrative Recap
To own Newmont, you need to believe in a long runway for gold production across a diversified set of mines and steady execution on cost control and project delivery. The recent Fed driven hit to bullion tests that belief, because earnings and cash flow remain closely tied to metal prices even as assets like Lihir, Boddington, and Tanami work on productivity gains.
In the short term, the key swing factor is whether upcoming results, where Wall Street expects higher EPS and revenue, confirm that operations are running tightly even with softer gold. The biggest immediate risk is that weaker bullion coincides with higher sustaining and development capex, which would pressure margins and reduce free cash generation if cost savings underdeliver.
The earnings setup is the announcement most investors will care about in this pullback. Analysts are looking for roughly 12.28% EPS growth and 9.66% revenue growth year over year, which puts a spotlight on how well Newmont is integrating its newer assets and managing grade declines at mines such as Cadia, Peñasquito, and Lihir.
If those numbers come through close to expectations while gold trades below recent highs, it would suggest the business is offsetting macro pressure through operating discipline and scale. A softer print, especially if tied to safety issues, integration hiccups, or higher than planned capex, would reinforce the risk that Newmont’s leverage to bullion and rising costs is still the dominant driver for the stock in the near term.
Newmont’s current earnings are reported at US$8.6b, with analysts expecting US$12.3b of earnings and US$31.4b of revenue by 2029. That profile is based on an assumption of revenue increasing by 6.8% each year and implies an earnings uplift of about US$3.7b from today’s level.
Uncover how Newmont's fair value indicates a 10% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Some of the lowest Newmont forecasts lean heavily on the risk that long term gold demand fades. Those analysts were modelling revenue of about US$24.9b and earnings near US$9.4b by 2029, well below the US$31.4b and US$12.3b consensus path. After the Fed driven gold drop, that gap in views may widen.
Explore 8 other Newmont fair value estimates, including one that suggests as much as 23% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Newmont research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Newmont. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newmont's overall financial health at a glance.
Looking For More Investment Ideas Beyond Newmont?
If this Newmont story has sharpened your thinking on gold exposure, it may be a good moment to broaden your watchlist using the Simply Wall St Screener and compare how different businesses stack up on quality, value, and resilience.
- For investors who care most about balance sheet strength and durable fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that helps you focus on financially robust companies.
- If you want ideas where market expectations look modest relative to business quality, scan a 16 high quality undiscovered gems that highlights lesser known stocks with solid underlying metrics.
- For a steadier ride through different market cycles, consider a 30 resilient stocks with low risk scores that filters for resilient businesses with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com