


- Peyto Exploration & Development confirmed a monthly dividend of $0.12 per common share for September 2026, to be paid on 15 October 2026 to shareholders of record on 30 September 2026. The company also reported Q2 2026 cash costs before royalties of $1.04 per Mcfe.
- The 10 year natural gas supply agreement with Centrica Energy, which begins in 2029 and targets premium European markets, is paired with Peyto Exploration & Development’s low cost Deep Basin operations and active hedge book to support a more diversified revenue mix and consistent monthly payouts.
- We will now examine how Peyto Exploration & Development's long term Centrica supply agreement could reshape its broader investment narrative.
Peyto Exploration & Development Investment Narrative Recap
To own Peyto Exploration & Development, you need to be comfortable with a focused Alberta Deep Basin gas producer that relies on low cash costs, a sizeable hedge book and infrastructure control to support monthly dividends. The latest affirmation of the CA$0.12 September 2026 payout signals that management is still aligning near-term capital allocation with that income focus rather than aggressively pursuing volume growth.
The main near-term catalyst is operational and pricing stability as Peyto keeps cash costs near the CA$1.04 per Mcfe level reported in Q2 2026 while managing AECO exposure. The key risk remains concentrated Alberta gas reliance, where infrastructure constraints, regulatory changes and local price discounts could quickly compress margins and test dividend flexibility.
The Centrica natural gas supply agreement is the announcement most closely tied to the current dividend story. It connects Peyto Exploration & Development’s Deep Basin output to premium European markets starting in 2029, giving the business an additional outlet beyond domestic hubs such as AECO, Empress and Eastern Canada over time.
In terms of catalysts, that contract adds clearer visibility on potential future market diversification, alongside the existing hedge program that already dampens realized price swings. The execution risk lies in bridging the period between today’s Alberta-centric operations and that potential future export exposure, while still funding drilling, coping with policy and tax costs, and sustaining monthly distributions at current levels.
Peyto Exploration & Development's current earnings are CA$475.6 million, with analysts projecting revenue to climb to CA$1.5b and earnings to reach CA$354.7 million by 2029. That outlook is based on an assumed 9.2% yearly revenue growth rate and an earnings decline of about CA$120.9 million from today's level to the 2029 consensus figure.
Uncover why Peyto Exploration & Development's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
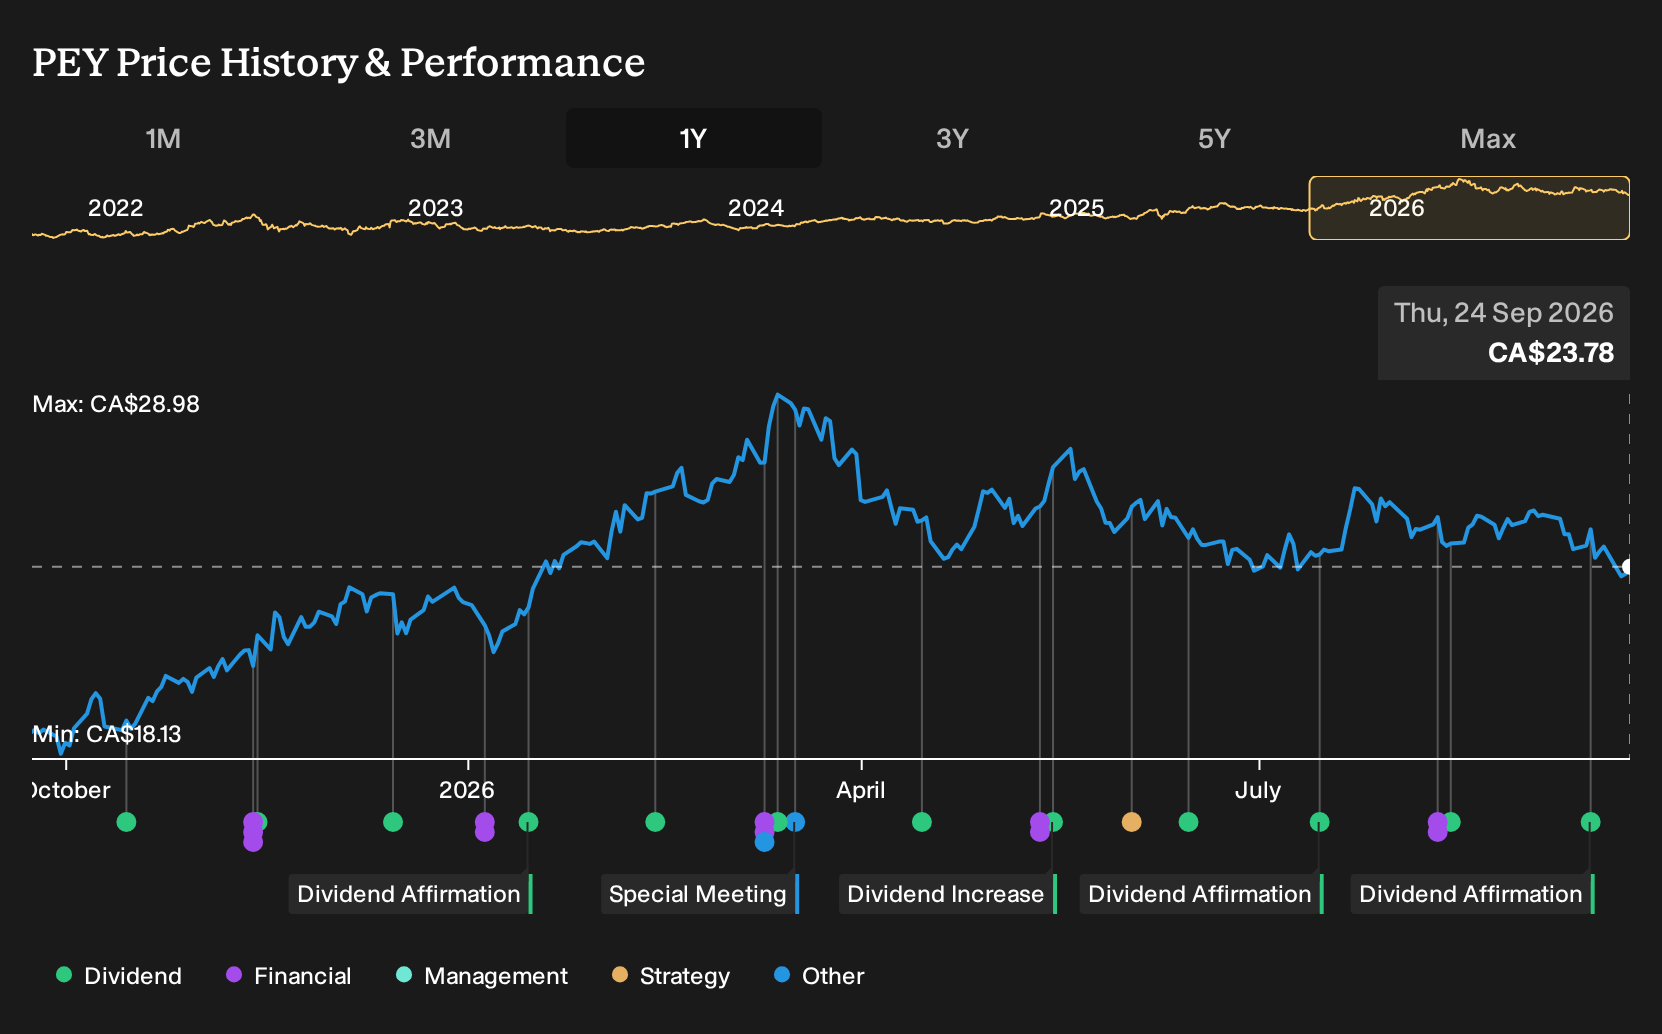
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly CA$27.78 to CA$51.26, which shows how far apart private investors can be on Peyto Exploration & Development. Those views predate the latest dividend affirmation and Centrica export contract. Revisit the risks around AECO pricing, Alberta concentration and policy costs, and compare several alternative viewpoints before forming a stance.
Explore another Peyto Exploration & Development fair value estimate, including one that suggests as much as 116% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Peyto Exploration & Development research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Peyto Exploration & Development. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Peyto Exploration & Development's overall financial health at a glance.
Looking For More Investment Ideas Beyond Peyto Exploration & Development?
If Peyto Exploration & Development fits your income and risk preferences, it can be helpful to line it up against a broader watchlist built from consistent rules. The Simply Wall St Screener lets you scan the market using the same type of cash flow, balance sheet and dividend filters that underpin this analysis, so you can spot other candidates that match your criteria rather than relying on headlines or hunches.
- If you want income to feel more predictable, compare Peyto Exploration & Development with other companies offering strong yields and resilient payouts by reviewing 1 dividend fortresses.
- If value is your priority, build a bench of potential ideas by scanning for solid businesses trading below their estimated worth using the 5 high quality undervalued stocks.
- If capital preservation ranks high on your checklist, start a shortlist of steadier performers by filtering for companies with more muted risk profiles through the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com