


Walmart shares have climbed over several years while the retailer pushes deeper into areas like digital payments, advertising and ultra fast delivery. This raises a simple question for you as an investor: Is the earnings power of the business strong enough to support where the stock trades today?
- Over the past 5 years, Walmart has delivered a share price return of 150.7%, which puts real pressure on its earnings to justify the move.
- New efforts around payments, retail media and ultra fast delivery can shift margins and cash generation, which matters directly for how much earnings investors are willing to pay for.
- Your read on Walmart is one view; the desks covering it have another. See what analysts think Walmart's shares could be worth.
The issue now is whether Walmart's current share price fairly reflects what its earnings can support over time.
If you want to test the same earnings question you are asking of Walmart across a broader set of retailers, take a look at 30 high quality undervalued stocks
Is Walmart Fairly Priced on Earnings?
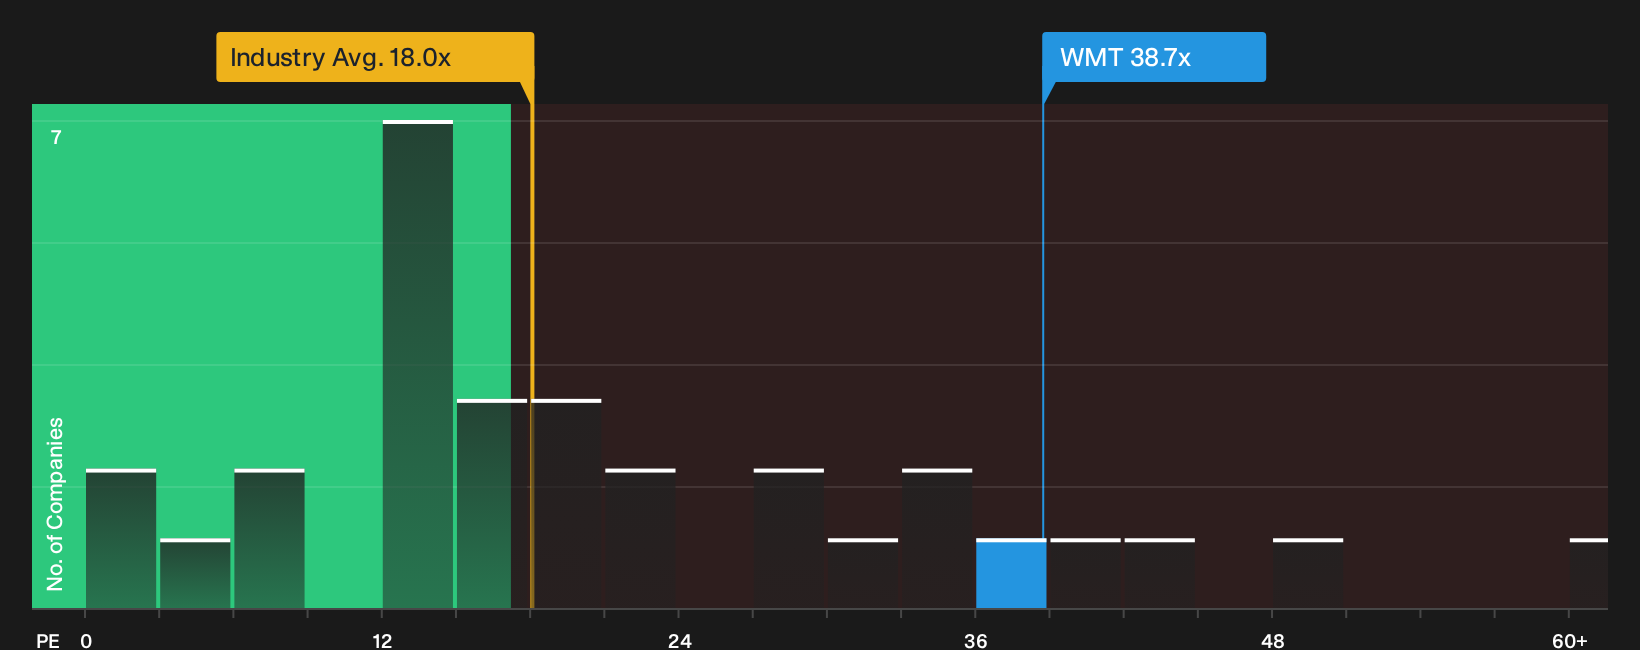
For a mature retailer like Walmart, the P/E ratio is often the cleanest way to see what investors are paying for each unit of earnings. Walmart trades on a P/E of about 38.7x, compared with roughly 18.0x for the wider Consumer Retailing industry and a peer average near 22.5x. That is a clear premium to both the sector and closer peers, which tells you the market is willing to ascribe a higher price to each dollar of profit than it does for many large retailers.
The fair multiple that folds in Walmart specific factors, including its scale, margins and risk profile, points to a level slightly below the current P/E. As a result, the shares screen a little expensive on this framework rather than outright stretched. Because the Sam's Club and Walmart Connect advertising efforts are gaining attention, investors appear comfortable paying up in the hope that fee based revenue can support that richer multiple. If you hold the view that earnings power can catch up to this price tag, the current P/E may look acceptable rather than extreme. Explore the numbers behind Walmart's P/E valuation.
The Walmart Narrative: What Would Justify Today's Price?
Walmart's Simply Wall St Narratives take the valuation puzzle you have just seen and turn it into a set of clear future paths that could leave the stock priced materially higher or lower than it is today. They sit on the Community page and spell out which mix of growth, margins and earnings power would need to hold for the current multiple to make sense. Where a single ratio or model gives one headline figure, Narratives lay out the underlying future it assumes so you can watch in real time whether that story is actually playing out.
One of the top community narratives on Walmart: 16% undervalued
"Expansion of higher margin business streams, Walmart Connect, marketplace, and Walmart+ memberships is diversifying Walmart's income base beyond retail..."
Discover why this Narrative puts Walmart at 16% undervalued.
One more Walmart check that sits beside the price tag
Before you finish your work on Walmart, it is worth asking who is actually steering this giant and how their pay packets line up with the outcomes you care about. See who runs Walmart and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com