


CoreCivic (CXW) drew fresh attention after recent trading, with the share price closing at US$34.36. Investors are weighing that move against strong year to date and 1 year total return figures.
The sharp 6.44% 1 day share price return contrasts with a 7 day share price return that slipped 3.32%. However, CoreCivic still shows an 80.65% year to date share price gain and a 286.07% 5 year total shareholder return, suggesting momentum has been building over a longer horizon.
Compare CoreCivic's sharp move with other potential momentum plays by scanning a curated list of 30 high quality undervalued stocks that combine strong returns with solid fundamentals.
CoreCivic now carries a market value of about US$3.2b on the back of that run. The business looks sizeable and profitable. The open question is whether the current share price already reflects that strength.
Most Popular Narrative: 18% Undervalued
CoreCivic's most followed valuation narrative points to a fair value of $41.80 per share, compared with the last close at $34.36. This puts the current move in the context of a bigger debate about what its detention assets and contracts might be worth.
The unprecedented increase in mandatory government funding for federal detention and border security (notably, $75 billion for ICE and multi-year appropriations through 2029) is catalyzing rapid contracting activity and the reactivation of idle facilities. This will significantly boost CoreCivic's recurring revenue and occupancy rates in future quarters.
Pressing demand for secure and reliable detention capacity due to record-high ICE populations and anticipated increases in U.S. Marshals Service detainees is driving new and expanded contracts. This will lift utilization rates at CoreCivic's facilities, with high incremental margins as idle beds are filled.
See why 15 investors see CoreCivic as 18% undervalued.
Result: Fair Value of $41.80 (UNDERVALUED)
Still, any shift in federal detention policy or a slower than expected detainee ramp at key CoreCivic facilities could quickly challenge the current 18% undervaluation story.
Find out about the key risks to this CoreCivic narrative.
Another View on CoreCivic's Valuation
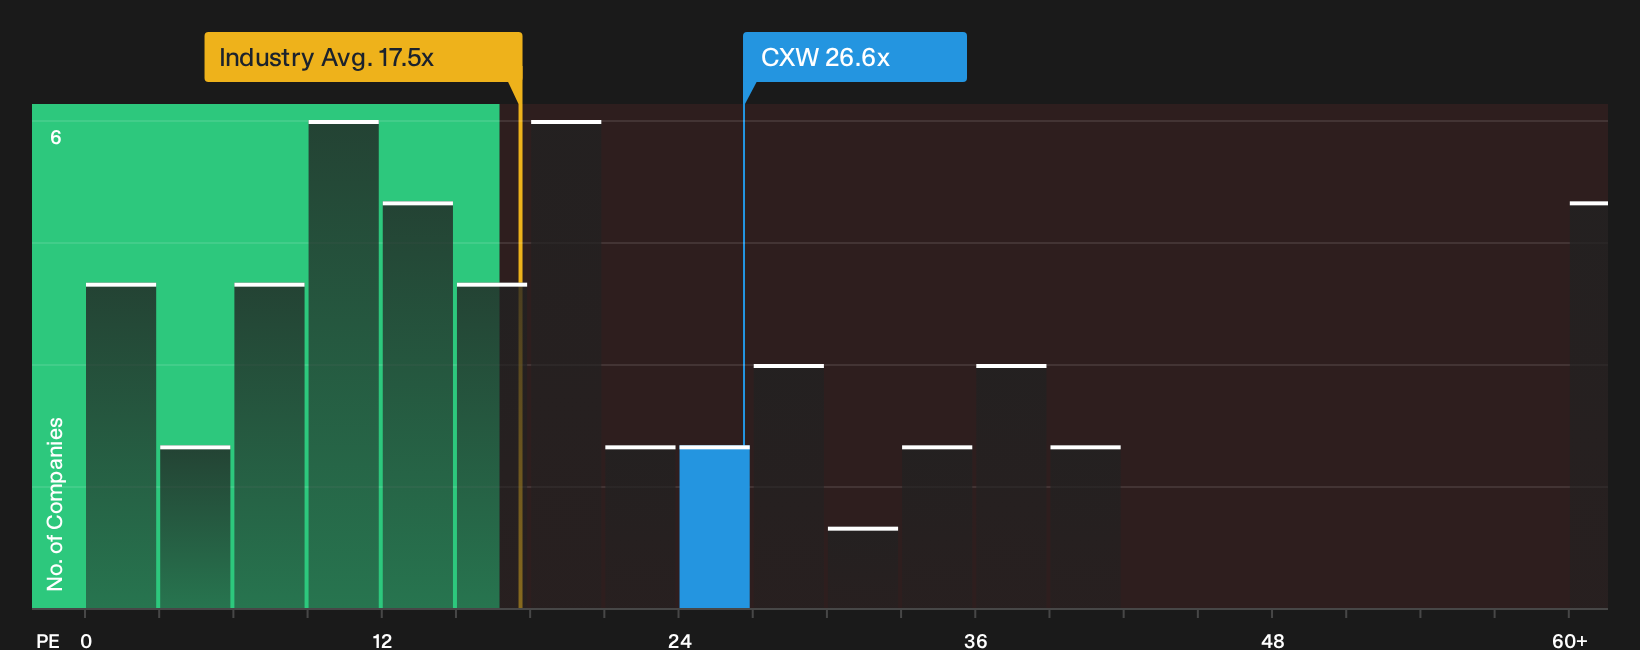
While the analyst narrative pegs CoreCivic as 18% undervalued on a fair value of $41.80, current market ratios tell a different story. The stock trades on a P/E of 26.6x, compared with an industry average of 18x and a fair ratio estimate of 8.7x. That gap points to meaningful valuation risk. Which signal do you trust more: the narrative or the multiple?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around CoreCivic's valuation can create a lot of noise, so act while the data is fresh and build your own view with the 2 key rewards and 3 important warning signs.
Looking for more CoreCivic-sized opportunities?
If CoreCivic has your attention, do not stop here. Use the screener to quickly surface fresh ideas that fit your risk, income, and quality preferences.
- Target higher income potential by scanning a focused set of resilient payers through the 8 dividend fortresses.
- Hunt for quality at a discount by reviewing a curated group of mispriced opportunities with the 30 high quality undervalued stocks.
- Dial down portfolio stress by checking a carefully filtered pool of steadier candidates via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com