


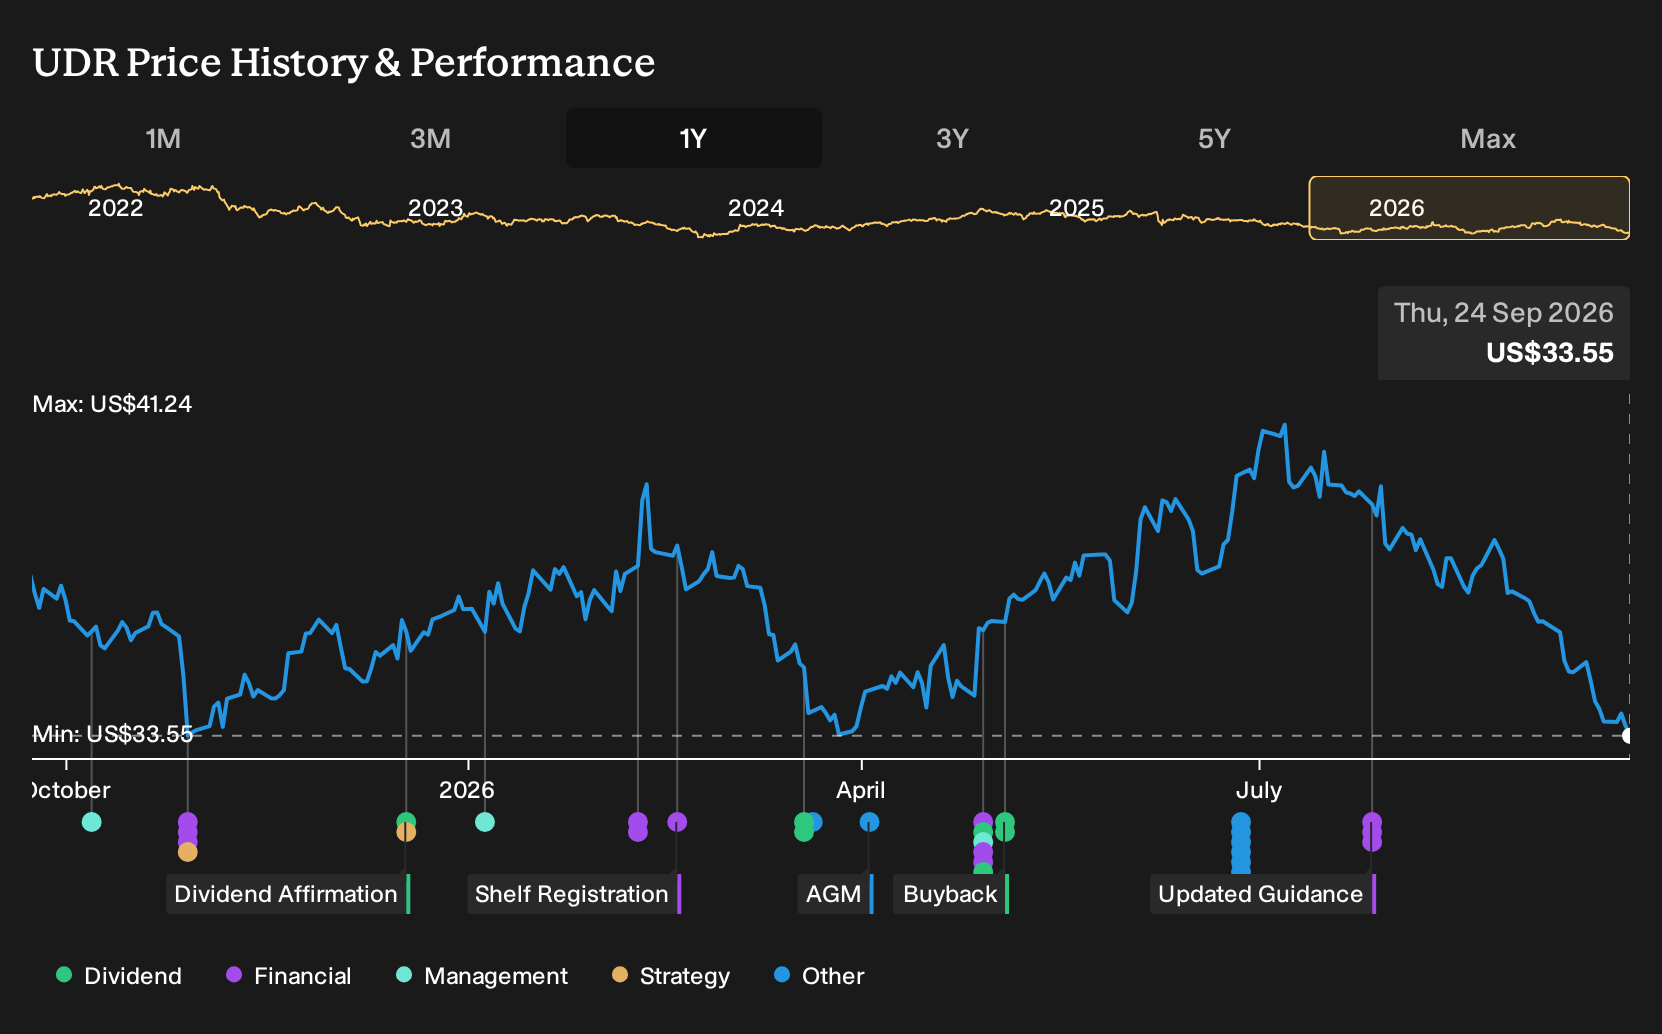
- UDR, Inc. confirmed that its Board of Directors declared regular monthly dividends of $0.145 per common share on its common stock, with record dates in October, November, and December 2026 and corresponding payable dates in November and December 2026, decisions that were set ahead of those months.
- The reaffirmed dividend schedule is presented alongside higher full year FFOA and same store NOI guidance. This highlights how UDR’s operating performance and cash distribution plans are being managed together despite pressure from elevated apartment supply and softer demand in some Sun Belt markets.
- We will now examine how UDR’s raised full year FFOA outlook could reshape the existing investment narrative around its apartment portfolio.
Scan how UDR’s reaffirmed dividend and updated FFOA outlook compare with other income-focused real estate stocks by reviewing our hand-picked list of 8 dividend fortresses in the market today.
UDR Investment Narrative Recap
To own UDR, you need to be comfortable with a multifamily REIT that leans on data driven operations and capital recycling, while accepting near term noise in certain markets. The raised FFOA and same store NOI outlook points to operations that are more resilient than feared, although the change is modest relative to broader concerns around earnings trends.
The key short term swing factor remains how quickly oversupply in Sun Belt regions and softer leasing in parts of Florida and Nashville stabilise. That pressure still risks holding back same store revenue and NOI. Legal and regulatory overhangs around pricing tools and rent control remain the biggest wild cards, and the new guidance does not remove them.
The reaffirmed monthly dividend of US$0.145 per share for October through December 2026 is the most relevant fresh data point for investors watching UDR today. It indicates that management currently views the cash flow profile as consistent with its existing payout level, even as leasing conditions vary across markets.
For you as a shareholder or potential shareholder, that dividend decision sits alongside the higher FFOA and same store NOI guidance as a test of execution on the core catalysts. These catalysts include using Orion analytics to sharpen pricing, recycling roughly US$650m of older assets into higher return opportunities, and managing Sun Belt softness and regulatory risk without eroding long term earnings power.
What UDR’s Long Range Forecasts Assume
UDR's narrative projects US$1.8b revenue and US$185.9m earnings by 2029. This assumes revenue grows by 1.0% a year and earnings decline by about US$331m from US$517.3m today.
Uncover why UDR's fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$41.5 and US$56.6, which shows how far private investors can spread on UDR. Those opinions sit beside clear risks around Sun Belt oversupply and regulatory pressure, as well as possible catalysts from Orion driven pricing and capital recycling. Explore the full range before deciding where you stand.
Explore another UDR fair value estimate, including one that suggests it could be worth just $41.55!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UDR research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for UDR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UDR's overall financial health at a glance.
Looking For More UDR Investment Ideas And Comparisons?
If UDR has sharpened your focus on income reliability, balance sheet strength, or potential mispricing, it can help to line it up against a broader watchlist of candidates. The Simply Wall St Screener gives you a fast way to scan other companies that share similar traits, then filter down to the few that genuinely deserve your time.
- For investors who want a margin of safety built into earnings power, start by reviewing 30 high quality undervalued stocks. This combines fundamental strength with what may be conservative pricing.
- If capital preservation and smoother portfolio swings matter most to you, narrow your search using a 30 resilient stocks with low risk scores. This screens for resilient businesses with lower risk profiles.
- When you want sturdier finances behind future dividends or reinvestment plans, broaden your research through a list of solid balance sheet and fundamentals (24 results). This highlights companies with stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com