


- DPM Metals reported extensive Brevene Porphyry South gold copper drilling results, with long high grade intercepts, confirmed vertical and lateral continuity, and early metallurgical testwork indicating that conventional flotation processing is feasible.
- The company is working to convert the Brevene exploration licence into a mining concession within Bulgaria’s existing permitting framework. This process could influence how efficiently DPM Metals turns this deep porphyry discovery into a producing asset.
- The impact of the large Brevene Porphyry South mineralized envelope on DPM Metals' investment narrative will now become clearer.
DPM Metals Investment Narrative Recap
To own DPM Metals, you need to believe the Brevene Porphyry South discovery and the broader project pipeline can offset future pressure points such as Ada Tepe closing and the Coka Rakita timing gap. The big near term swing factor is how quickly Brevene can move from exploration success toward a defined development path.
The main operational risk still sits around project timing, permitting and cost inflation, rather than this week’s corporate news. The Peter Brady appointment supports the permitting and governance side of that equation, but does not change the fact that any delays at Coka Rakita, Loma Larga or Brevene could strain future production and cash generation.
The appointment of Peter Brady as Executive Vice President is the announcement most directly tied to the Brevene story. His background in environmental law, regulatory compliance and complex mining transactions lines up with what DPM Metals needs as it works to convert Brevene from exploration licence to mining concession in Bulgaria.
For you as a shareholder, that matters because the permitting path is a key catalyst and a key risk. Strong in house legal and governance capability can help the business manage environmental approvals, concession terms and future project financing across Coka Rakita, Chelopech extensions and Loma Larga, all of which sit alongside Brevene in the medium term project queue.
DPM Metals' current analyst narrative points to forecast revenue of $1.3b and consensus earnings of $766.2 million by 2029. This is based on revenue that is expected to remain fairly flat and earnings rising from $649.3 million today, which implies an earnings increase of about $116.9 million over that period.
Uncover why the forecast for DPM Metals' fair value is essentially in line with its current price.
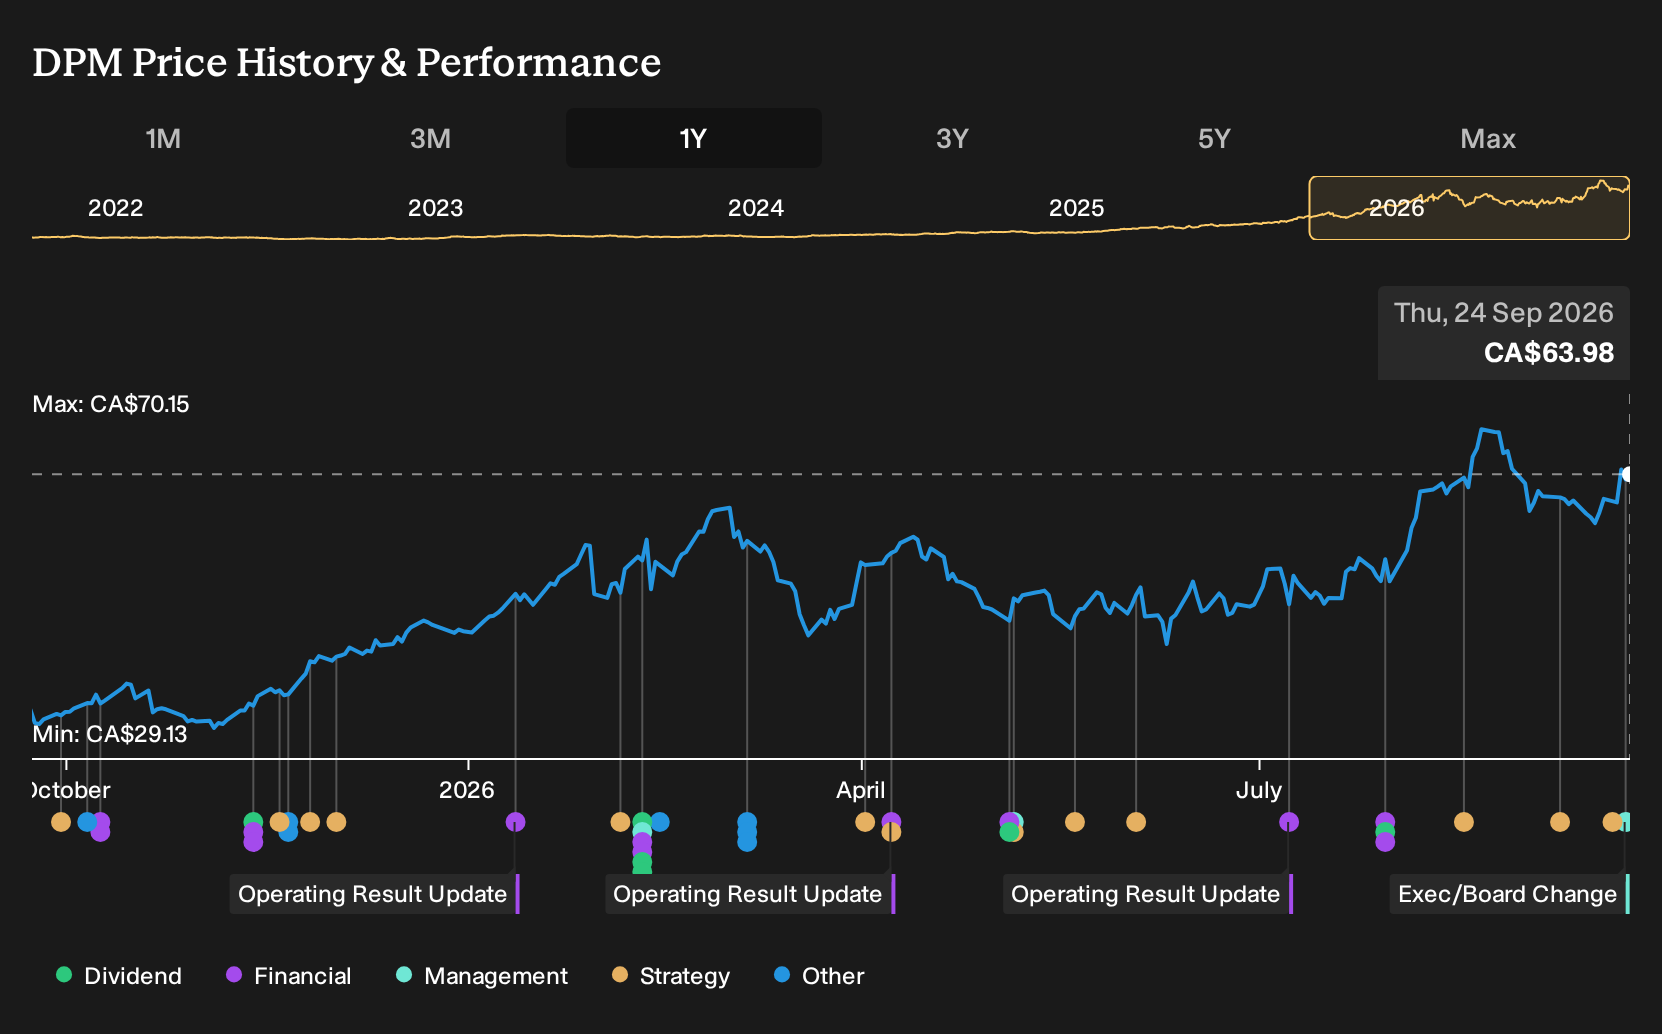
Exploring Other Perspectives
One alternate view fixates on cost inflation risk rather than Brevene or Coka Rakita timing. The most cautious analysts had pencilled in revenue drifting to about $1.0b and earnings of roughly $566.6 million by 2029. That is a much more pessimistic DPM Metals story, and could shift again once this week’s hiring and drilling news is absorbed.
Explore 3 other DPM Metals fair value estimates, including one that suggests it could be worth just CA$62.92.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DPM Metals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for DPM Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DPM Metals' overall financial health at a glance.
Looking for more investment ideas beyond DPM Metals?
Once you have a view on DPM Metals, it can help to compare its risk, income and valuation profile with a broader watchlist built using the Simply Wall St Screener.
- For investors who want potential mispricings backed by solid fundamentals, scan a curated group of 5 high quality undervalued stocks that might warrant a closer look beside DPM Metals.
- If capital preservation and steadier balance sheets are a priority, build a short list from our 8 resilient stocks with low risk scores to see how they stack up against your current holdings.
- For those hunting earlier stage opportunities with stronger finances than the label suggests, filter the market using our 19 elite penny stocks with strong financials to spot candidates for deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com