


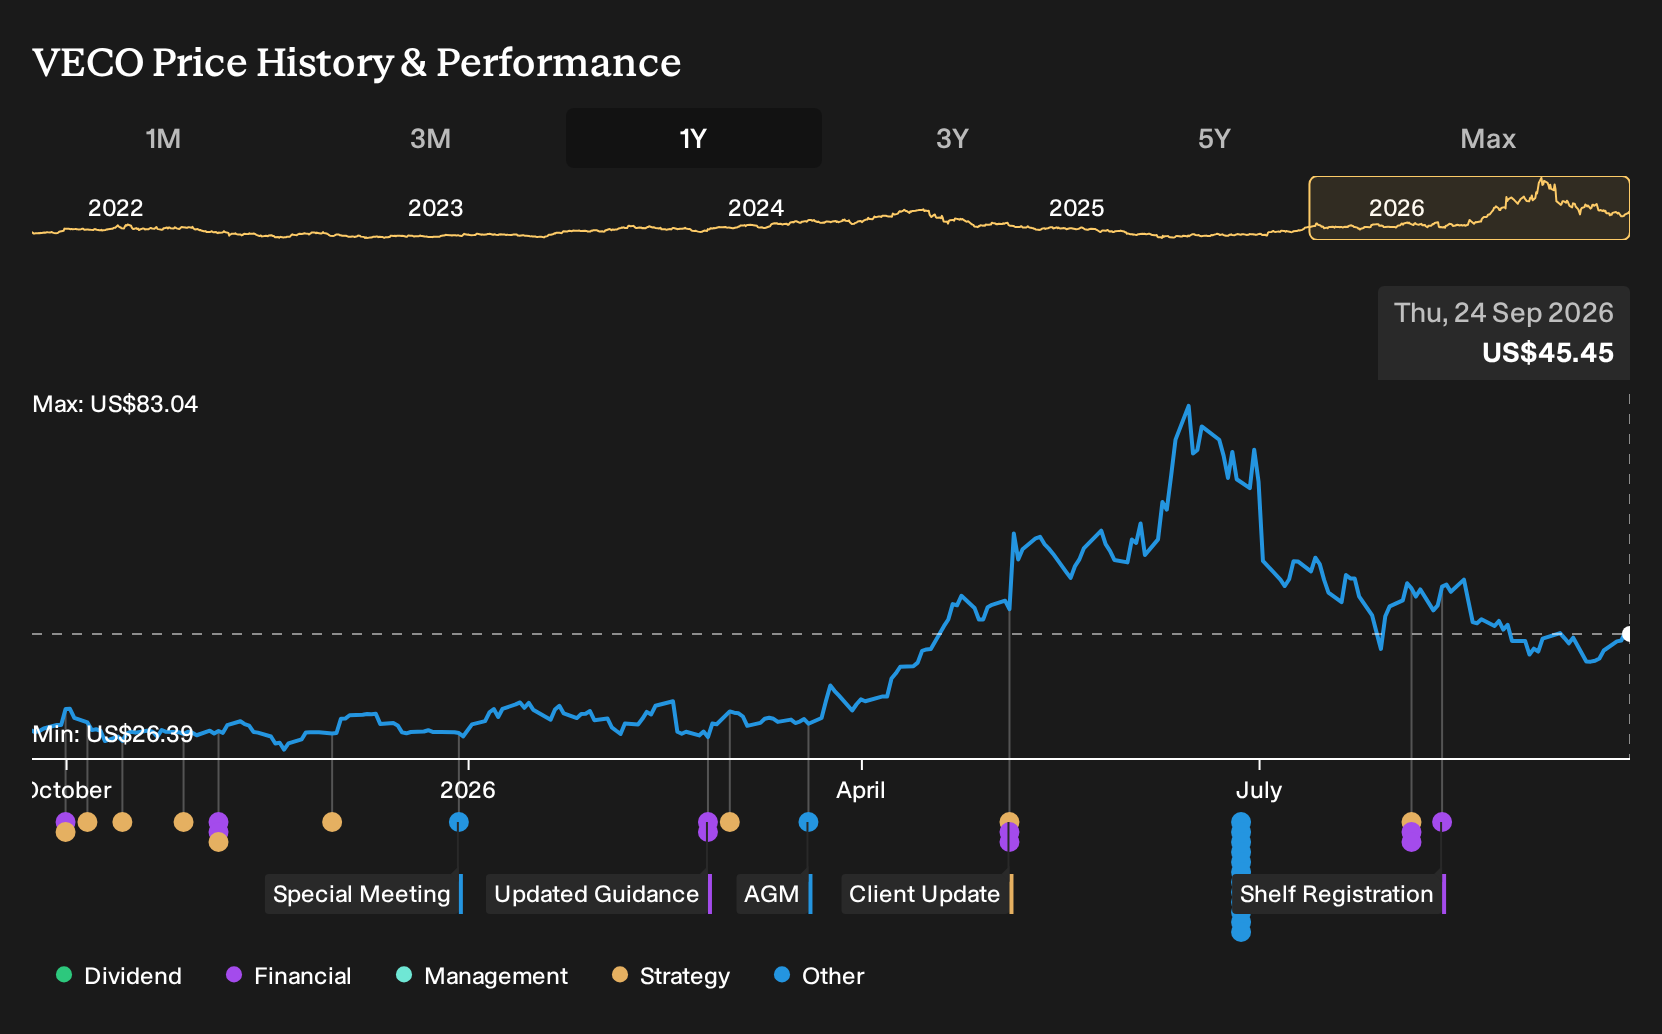
- Veeco Instruments has attracted fresh attention after a period of strong year to date share performance, supported by analyst views that its current valuation sits below their fair value estimates and by expectations for expanding profit margins.
- The focus is shifting to Veeco Instruments' ability to turn its specialized semiconductor and thin film equipment portfolio into sustained earnings growth while managing concentrated customers, policy exposure, and uncertain timelines for new product adoption.
- The next step is an assessment of how this renewed focus on profit margin expansion could reshape Veeco Instruments' broader investment narrative.
Extend your search beyond Veeco Instruments and compare this setup with a hand picked group of potential breakout opportunities screened as 30 high quality undervalued stocks.
Veeco Instruments Investment Narrative Recap
For a shareholder in Veeco Instruments, the core belief is that demand for its semiconductor and thin film tools translates into steadier earnings and healthier margins over time. The recent share move sharpens attention on whether management can turn a 3.4% net margin into something more durable while handling cost inflation and higher risk funding that is fully reliant on borrowing.
The short term swing factor is how quickly newer process platforms and services revenue convert into higher quality earnings, given the recent one off loss of US$11.1m and margin compression from 8.7%. The biggest operational risk right now is customer and regional concentration, especially exposure to China, which could still disrupt order patterns without much warning.
There have been no fresh company announcements disclosed alongside this move, so the most relevant reference point is the existing guidance narrative around AI, advanced packaging and 3D architectures as key demand drivers for Veeco Instruments. That story is linked directly to the long term expectations for revenue growth of 27.8% per year and earnings expansion that analysts currently model.
For you, the question is execution. Can Veeco Instruments convert that opportunity into smoother orders from foundries and integrated device manufacturers, while lifting return on equity from 2.6% and rebuilding margins from recent pressure? Any updates to order backlog, regional mix, or service revenue in upcoming reports would likely matter more than the latest price move itself.
Veeco Instruments' narrative projects US$1.3b revenue and US$281.3m earnings by 2029. This assumes 25.0% yearly revenue growth and an earnings increase of about US$258m from US$23.1m today.
Uncover why Veeco Instruments' fair value indicates a 33% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Veeco Instruments, the most optimistic analysts lean hard into AI driven demand as a catalyst. They were already penciling in about US$1.5b of revenue and US$469.3m of earnings by 2029, far above consensus. Those projections pre date this latest move, so expectations may change as new information becomes available.
Explore 4 other Veeco Instruments fair value estimates, including one that suggests as much as 45% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Veeco Instruments research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Veeco Instruments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Veeco Instruments' overall financial health at a glance.
Looking For More Investment Ideas Beyond Veeco Instruments?
If Veeco Instruments has sharpened your interest in targeted opportunities, it can be useful to line it up against a broader watchlist built from clear, rules based screens. In this way, you can see how this stock compares on factors such as balance sheet strength, income potential, or under followed quality.
- For resilience and capital preservation, consider companies with stronger finances by checking out the list of solid balance sheet and fundamentals (24 results).
- If income is your priority, focus on businesses with robust cash flows and higher yields by reviewing the 8 dividend fortresses.
- To hunt for lesser known prospects with solid fundamentals, widen your search with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com