


- Super Micro Computer recently began shipping fully integrated NVIDIA Vera Rubin NVL72 racks that combine 72 Rubin GPUs, 36 Vera CPUs, and its in-house direct liquid cooling and Data Center Building Block Solutions for turnkey AI data center deployments.
- The Vera Rubin NVL72 rollout extends Super Micro Computer's role from server supplier to full-stack AI infrastructure partner by covering design, manufacturing, cooling, networking integration, and on-site deployment across megawatt scale projects.
- We will now see how Super Micro Computer's investment narrative could be influenced by full-stack Vera Rubin NVL72 liquid cooled racks.
Super Micro Computer Investment Narrative Recap
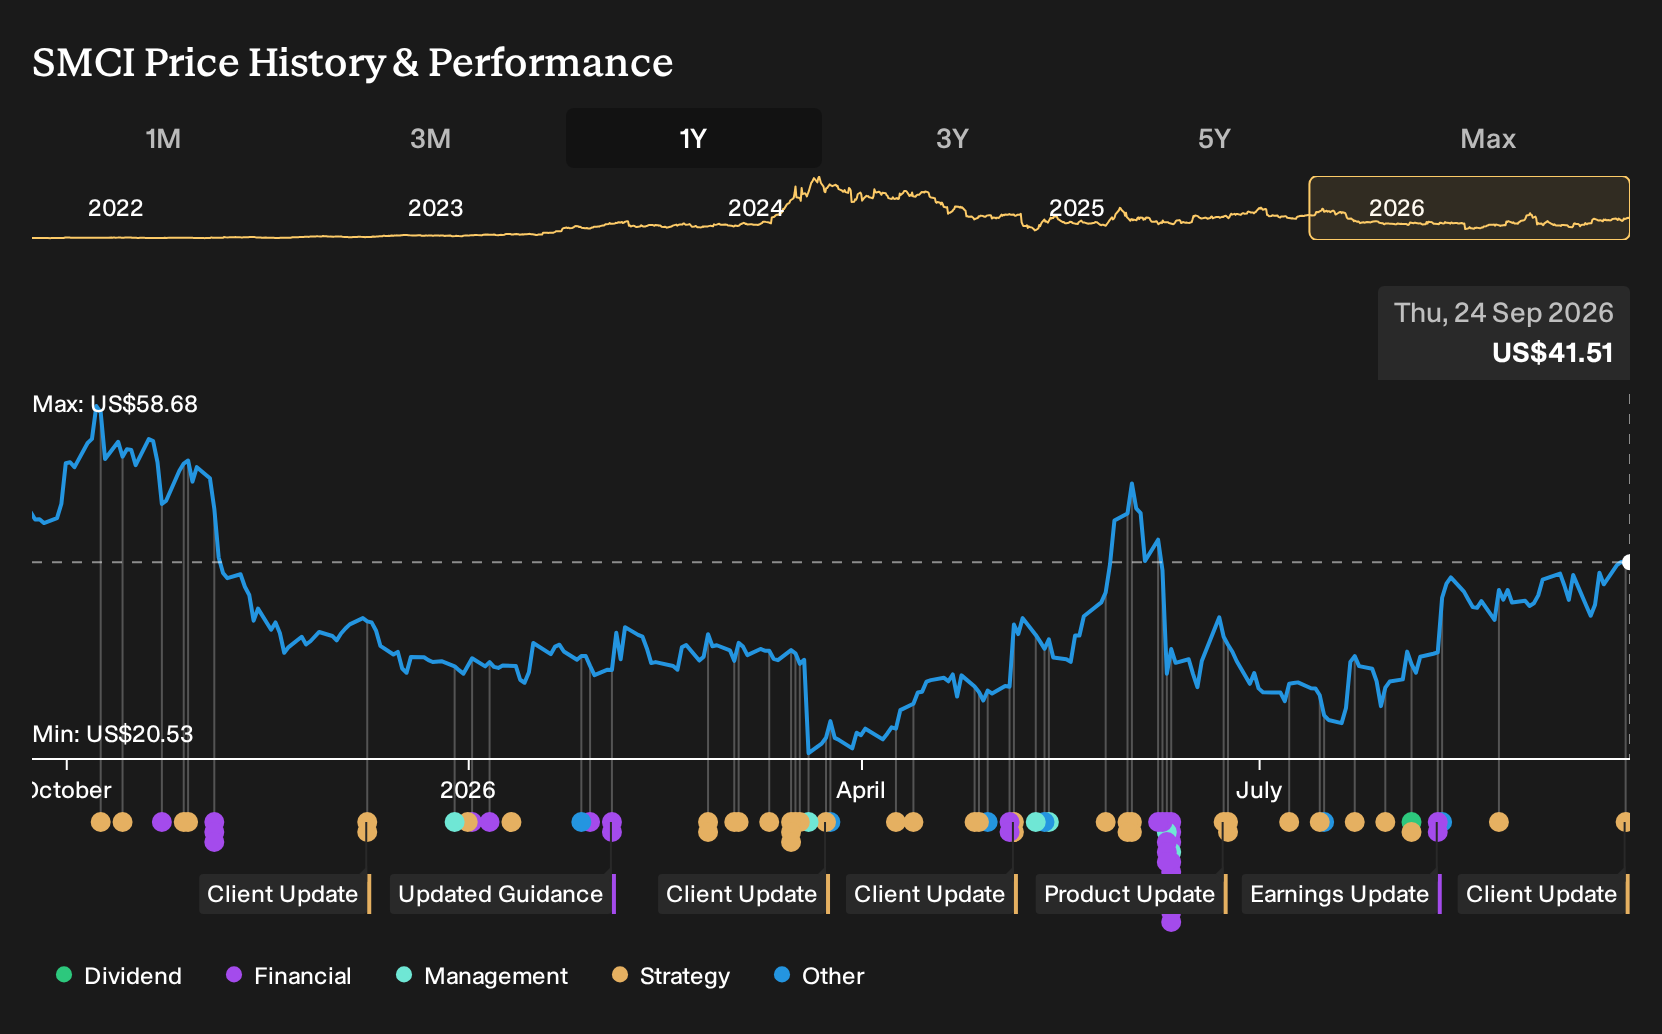
To own Super Micro Computer, you need to believe that AI infrastructure spending stays strong enough for its high performance servers and full-rack solutions to keep winning large deployments. The Vera Rubin NVL72 launch feeds directly into that AI data center build out and supports the short term catalyst, converting its roughly US$60b order book into shipped systems on schedule.
The biggest near term risk still sits in execution and pricing. Super Micro is leaning heavily on DCBBS and liquid cooled racks to support margins in a market where management already talks about price wars in commodity hardware. Any delays, customer concentration issues, or sharper discounting could offset the operational upside from Rubin driven demand.
The Rubin NVL72 rollout connects tightly with Super Micro Computer’s earlier disclosure that its DCBBS Blueprint can scale one Vera Rubin NVL72 Scalable Unit to 1,152 GPUs across 16 racks with balanced power, cooling, storage, and networking. That blueprint turns the firm into a one stop build partner for megawatt scale AI clusters rather than a component supplier.
For investors watching catalysts, that same announcement also highlights where execution can strain. The company now owns more of the stack, from cold plates and CDUs to networking integration and on site deployment, which increases project complexity and working capital needs. Delivery timetables, supply chain stability, and any disruption from legal disputes around components all feed directly into how quickly that US$60b order pipeline translates into recognized revenue.
What The Consensus Numbers Assume For Super Micro Computer
Super Micro Computer's narrative projects US$91.7b revenue and US$3.4b earnings by 2029. That rests on analysts modeling 32.9% yearly revenue growth and an earnings increase of about US$1.2b from US$2.2b today.
Uncover why Super Micro Computer's fair value is essentially in line with its current price.
Exploring Other Perspectives
One alternate view focuses on excess inventory risk. Before this Rubin news, the most cautious analysts were only penciling in about US$80.2b of revenue and US$2.9b of earnings by 2029, with a much lower 7.9x P/E. That is a far more skeptical story than consensus, and it might shift as full-stack Vera Rubin racks are rolled out.
Explore 11 other Super Micro Computer fair value estimates, including one that suggests as much as 41% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Super Micro Computer research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Super Micro Computer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Super Micro Computer's overall financial health at a glance.
Looking For More Investment Ideas Beyond Super Micro Computer?
If the Super Micro Computer story has you thinking about where AI infrastructure and related themes might lead next, it can help to scan a broader field of stocks with similar resilience or different risk profiles using the Simply Wall St Screener.
- For investors who want potentially steadier portfolios with fewer shocks, consider reviewing 30 resilient stocks with low risk scores to keep overall risk scores in check while still aiming for exposure to equity returns.
- If balance sheet strength matters most to you, filter for companies with solid cash positions and manageable debt using our list of solid balance sheet and fundamentals (24 results) to see which businesses may be better positioned for future funding needs.
- Those hunting for potential mispricings can cast a wider net across companies that combine quality fundamentals with lower implied valuations by scanning our 30 high quality undervalued stocks and building a watchlist from there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com