


Alphabet (GOOG) (GOOGL) stock has underperformed the broader equity market so far in 2026. Shares of the Google parent have gained about 10% year-to-date (YTD), compared with a 13% increase in the S&P 500 ($SPX).
While Alphabet stock has underperformed the broader market, the tech giant’s growth outlook remains solid. The tech giant is well positioned for strong growth, supported by diversified revenue streams and expanding exposure to several high-growth markets.
Alphabet’s strong cloud backlog points to sustained demand for Google Cloud Platform (GCP), while expanding adoption of its Tensor Processing Units (TPUs) creates a substantial opportunity as demand for artificial intelligence (AI) infrastructure accelerates.
Alphabet will also benefit from its growing subscription ecosystem, which provides recurring revenue. Meanwhile, the continued resilience of its core Search business and higher engagement on YouTube will support its advertising revenue, providing significant cash and strengthening its ability to fund investments in AI and other growth initiatives.
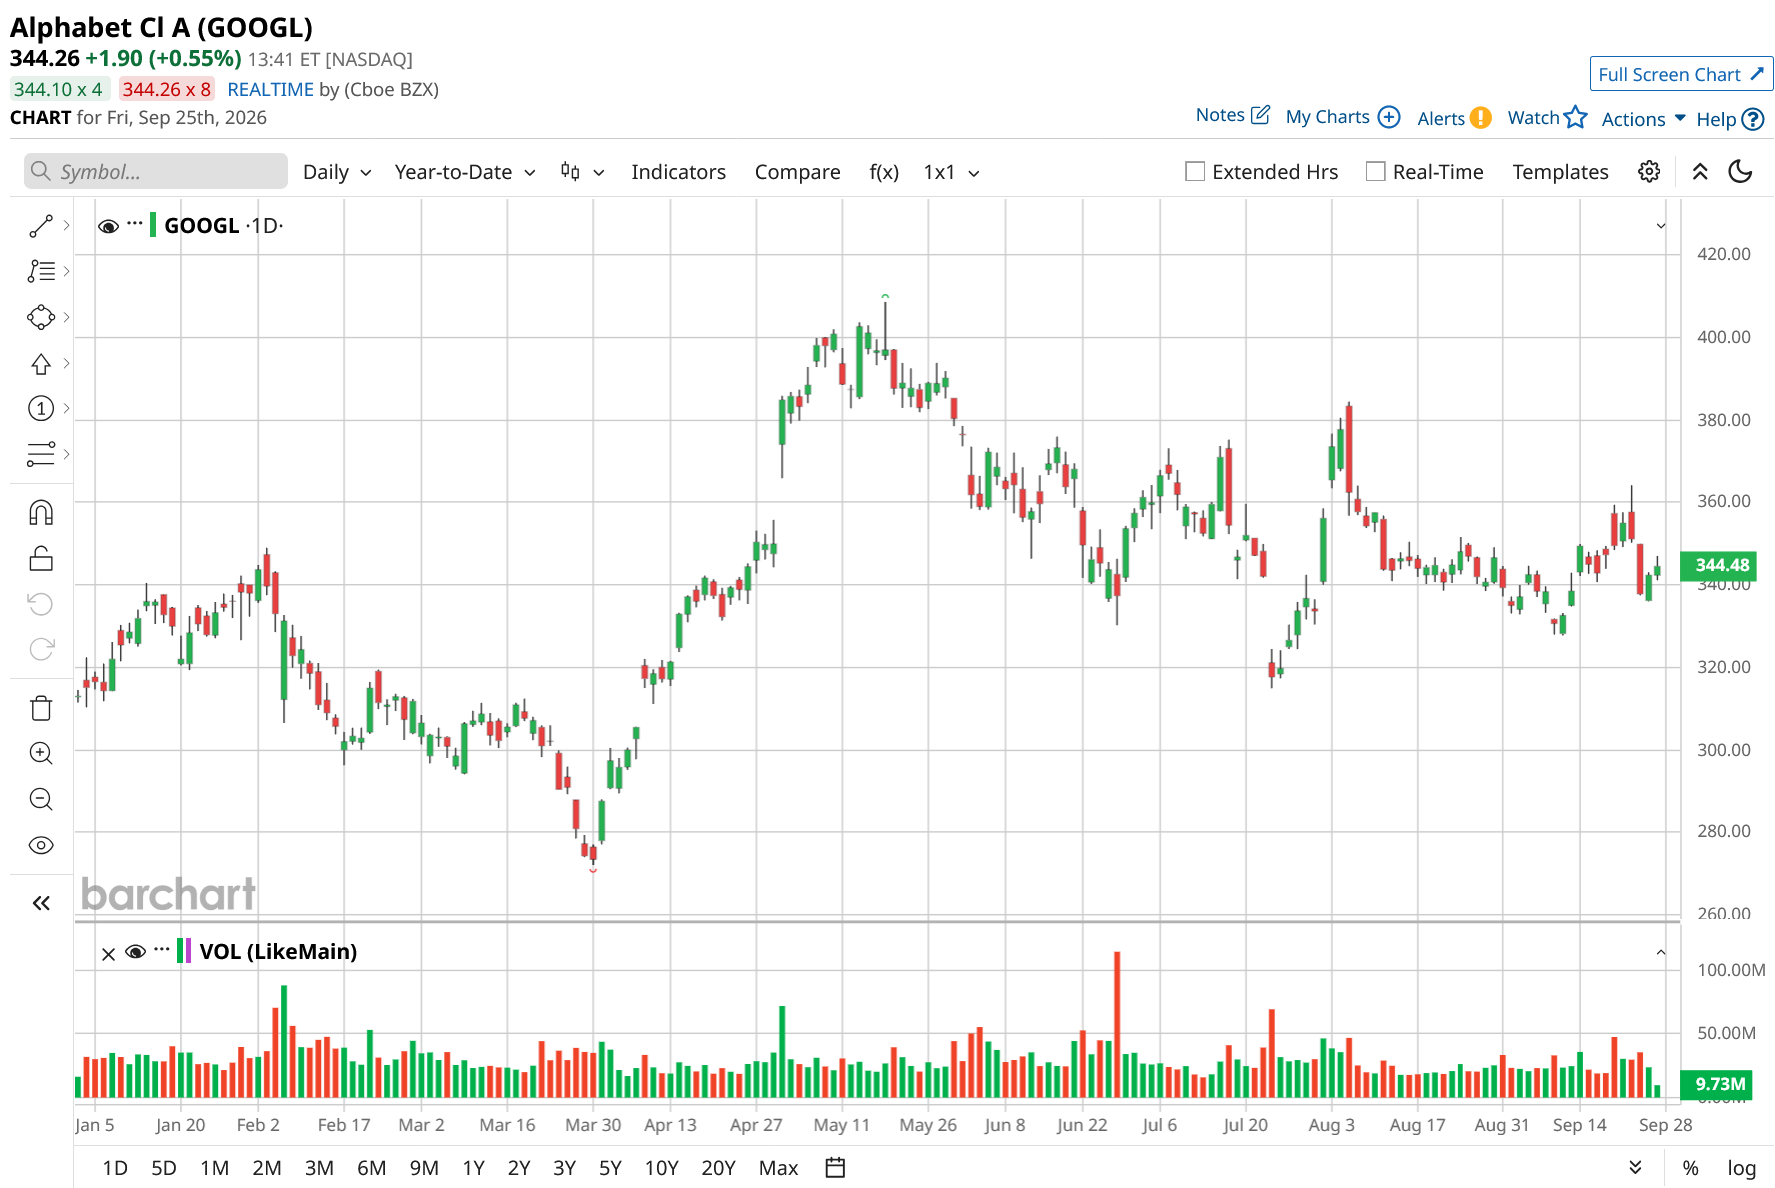
Alphabet’s Diversified Growth Engines Strengthen Investment Case
Alphabet’s growth outlook remains solid, driven by its diversified revenue base, including cloud, AI, advertising, and subscription businesses. While advertising continues to provide a substantial earnings base, the rapid expansion of Google Cloud and growing monetization of AI-related products are creating additional sources of revenue and profit growth.
While Alphabet is investing significantly in AI capabilities, the move is accelerating its growth. The most significant evidence that Alphabet’s infrastructure investments are beginning to pay off is the acceleration in Google Cloud. Cloud revenue climbed 82% year over year to $24.8 billion in the second quarter, compared with 63% growth in the first quarter. The acceleration reflects stronger demand for GCP, AI infrastructure, and enterprise AI solutions.
The improvement in profitability is particularly notable. Google Cloud generated $8.8 billion in operating income, more than three times the prior-year level. Its operating margin expanded from 20.7% to 35.6%.
Looking ahead, Alphabet’s expanding Cloud backlog supports the growth outlook. Its backlog increased by more than $50 billion sequentially to $514 billion. The company also began recognizing revenue from TPU systems deployed in customers’ data centers during the second quarter. TPUs represent another solid avenue for Alphabet to monetize its AI infrastructure capabilities.
Management expects only a relatively small portion of revenue from existing TPU system agreements to be recognized in the current year, with recognition expected to accelerate as the company exits 2026. Management expects to realize the substantial majority of revenue associated with these agreements in 2027. Consequently, TPU-related revenue could become a more meaningful contributor to Alphabet’s financial performance over the next several years.
At the same time, Alphabet’s core advertising business continues to demonstrate resilience. Google Search and other advertising revenue increased 17% year over year to $63.3 billion in the second quarter, while YouTube advertising revenue grew 13% to $11.1 billion.
The growing integration of AI into Search is driving user engagement and supporting advertising monetization.
In addition, Alphabet’s revenue diversification extends beyond advertising and Cloud. Subscription, platforms, and devices revenue increased 15% in the second quarter, supported by growth in YouTube subscriptions and Google One.
YouTube Music and YouTube Premium continued to drive subscription expansion, while Google One benefited from rising demand for AI-focused plans. This creates an additional monetization channel for Alphabet’s AI investments.
Overall, Alphabet is well-positioned to deliver strong growth ahead, led by its diversified revenue base and acceleration in its cloud business.
Valuation Indicates Room for Upside
Alphabet’s valuation appears relatively undemanding given its growth prospects. GOOGL stock trades at a forward price-to-earnings (P/E) multiple of 17.1x, notably lower than several large technology peers. By comparison, Microsoft (MSFT) and Amazon (AMZN) trade at forward P/E multiples of 25.4 and 31.8, respectively.
Although elevated capital expenditure could weigh on margins and free cash flow in the near term, these investments are strengthening Alphabet’s competitive position and accelerating its growth.
Its solid growth trajectory and relatively low valuation suggest further upside in GOOGL stock.
Alphabet Stock Is a Buy Now
Alphabet’s accelerating Cloud business, expanding AI monetization, resilient advertising, and growing subscription revenue provide a diversified base for solid growth ahead. While elevated AI-related capital spending may pressure near-term margins and free cash flow, the resulting infrastructure investments are strengthening Alphabet’s position in high-growth markets.
With shares trading at about 17.1 times forward earnings, Alphabet appears reasonably priced against its expected growth and valuations across other large-cap technology companies, adding to its investment appeal.
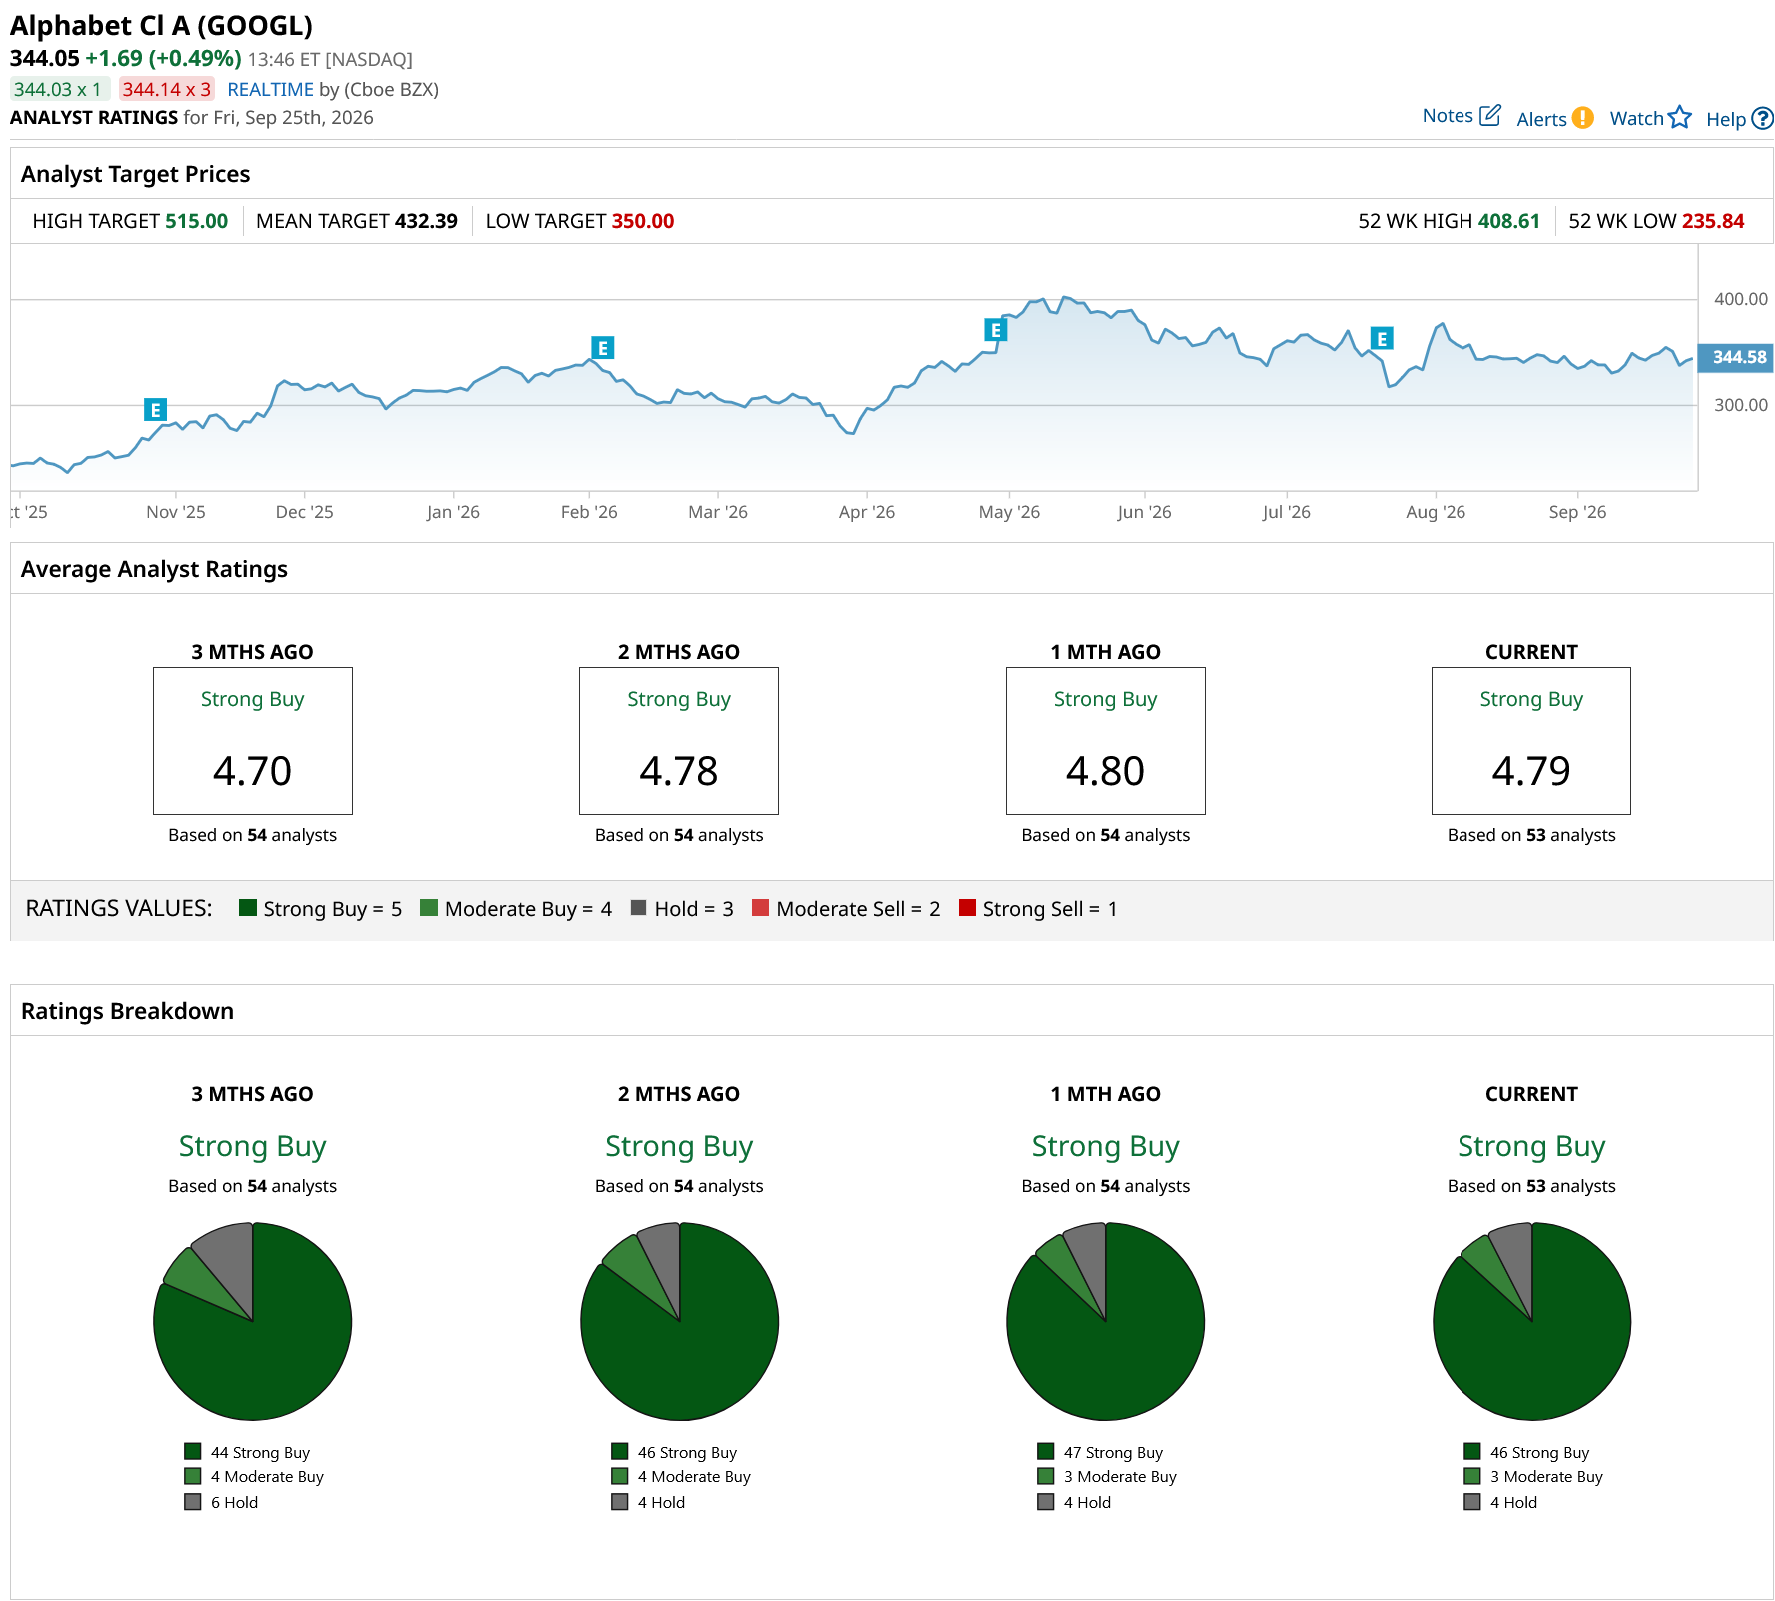
Analysts remain positive on the company, with Alphabet's stock currently sporting a “Strong Buy” consensus rating.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.