


Mastercard (MA) is back in focus after SoFi Bank began using SoFiUSD, a bank issued stablecoin, to settle an estimated $25b card program directly on Mastercard’s global payments network.
For context, Mastercard’s recent performance has been mixed, with a 90-day share price return of 13.44% but a 30-day share price return that declined 5.55%. At the same time, the 3-year total shareholder return of 44.27% and 5-year total shareholder return of 67.70% point to a much stronger longer run. Frequent headlines around SoFiUSD settlement, new open finance tools with Lenders Cooperative, and fresh card issuing partnerships such as KEO Capital help explain why sentiment has stayed engaged. However, the softer recent month suggests some investors are still reassessing how these projects affect Mastercard’s risk profile and future cash generation.
Scan how Mastercard’s SoFiUSD move compares with other payment and fintech stocks by sorting through our hand picked 16 high quality undiscovered gems in the same broader theme.
Mastercard has a fresh story in stablecoin settlement, a long run of shareholder gains and a recent pullback in the share price. Is this a sensible entry now, or does patience make more sense once the numbers are on the table?
Most Popular Narrative: 24.5% Undervalued
According to the most followed narrative on Mastercard, a fair value of $750 sits well above the recent $566.08 close. This paints the SoFiUSD settlement as part of a wider gap between price and business strength.
This will not excite anyone chasing a big yield today. What it offers instead is a business that compounds safely, a payout growing at double-digit rates from a tiny base, and a price that does not currently reflect either of those things. Setups like that do not come around often, and the current pullback looks more like an entry point than a warning sign.
See why 138 investors see Mastercard as 25% undervalued.
Result: Fair Value of $750 (UNDERVALUED)
Still, Mastercard faces clear swing factors, including heavier regulatory pressure on fees and faster adoption of rival payment rails that could weaken its SoFiUSD edge.
Find out about the key risks to this Mastercard narrative.
Another View On Mastercard’s Valuation
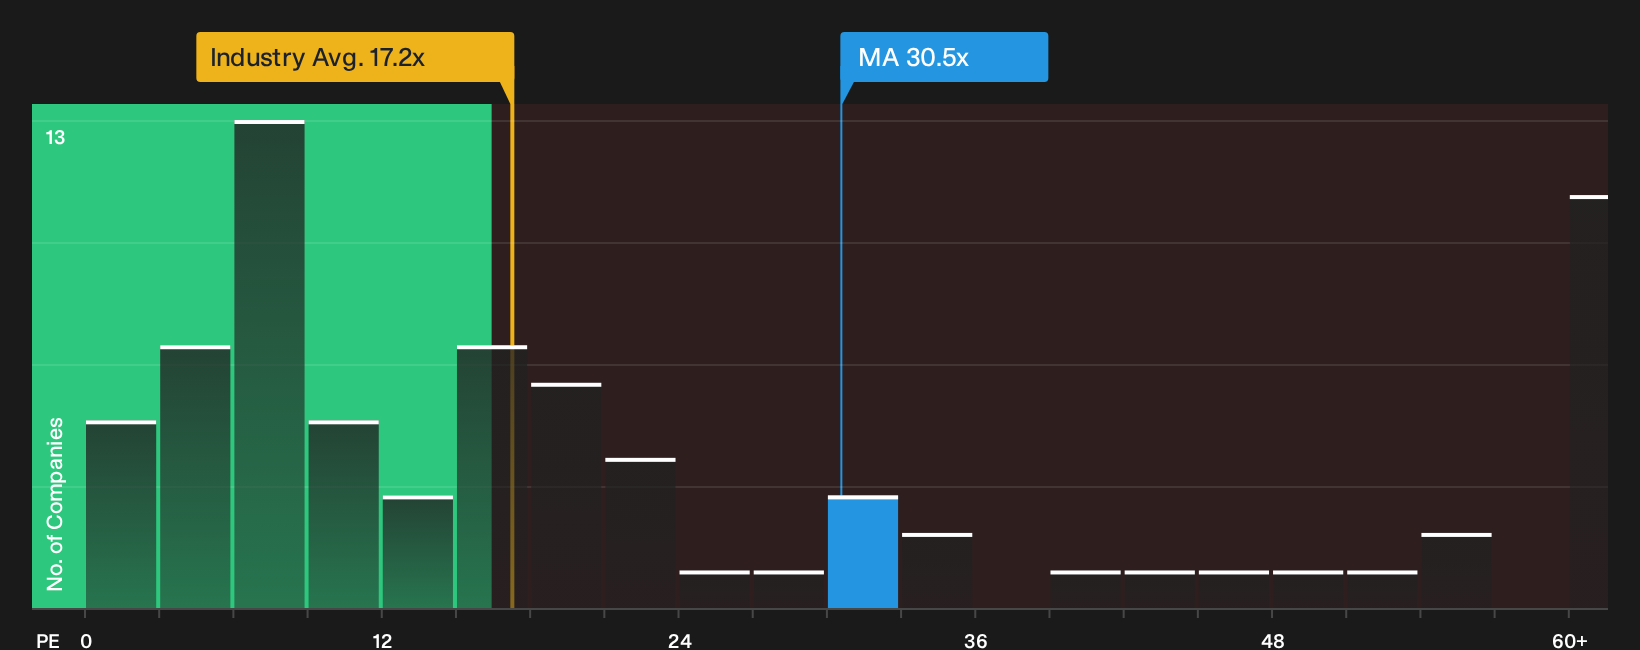
The first narrative leans on fair value estimates around $750, which puts Mastercard at a 24.5% discount to that mark. Look at the P/E lens and the picture changes. The stock trades at 30.5x earnings, well above the US Diversified Financial industry at 17.2x and above its own fair ratio of 21.4x. That premium hints at meaningful valuation risk if sentiment cools, so how comfortable are you paying a higher multiple for quality that much of the market already knows?
For a closer look at how this pricing gap shows up in the numbers, check the valuation breakdown next See what the numbers say about this price — find out in our valuation breakdown.
Here is how Mastercard’s P/E compares with peers visually
Next Steps
So is sentiment here too gloomy or not cautious enough, given Mastercard has clear risks on one side and meaningful potential rewards on the other? Act quickly, review the underlying data, and weigh both angles by checking the 3 key rewards and 2 important warning signs.
Ready To Find Your Next Mastercard Sized Idea?
Mastercard is only one way to put capital to work. Use the Simply Wall St Screener to spot other opportunities that fit your style before the market does.
- Target resilient potential by scanning a 30 resilient stocks with low risk scores that may help you stay invested when conditions get choppy.
- Hunt for mispriced quality and surface a 30 high quality undervalued stocks that could suit investors who care about both fundamentals and price.
- Zero in on balance sheet strength and filter through a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without relying on hope.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com