


Central banks are tightening policy to keep inflation in check, and higher borrowing costs are putting more pressure on profit quality. Cash is king again. For Australian investors, that puts businesses with strong cash generation and discounted valuations in a sweet spot. This article walks through three stocks flagged by our cash flow value screen that appear to be priced as if the market is still ignoring their balance sheet strength.
The three stocks below are just a sample from this idea, and the full screen on Simply Wall St has surfaced 3 more companies with equally cash-rich stories that are not covered here. To go deeper, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the cash flow opportunities that best fit your investing style.
Woodside Energy Group (ASX:WDS)
Woodside Energy Group is a Perth based hydrocarbon producer whose LNG projects feed directly into the cash flow focused theme of this screener. This gives investors a way to look at sizeable energy assets through the lens of recurring cash generation rather than just spot prices.
Woodside Energy Group develops and sells LNG, pipeline gas, crude oil and natural gas liquids, with around A$7.3b from Australia, A$4.6b from international operations and A$1.9b from marketing, and carries a market value of roughly A$60.3b.
"Investor optimism appears driven by expectations for long-term demand growth in Asian and emerging markets, with Woodside's global LNG expansion (Louisiana, Scarborough) positioned to capture this demand. However, these assumptions may underestimate the potential for rapid decarbonization policies or renewable adoption, which could affect future revenue and volumes if LNG demand softens in key markets."
For anyone weighing Woodside Energy Group, the real test lies in how pressure on future cash generation ultimately feeds through to valuations.
That tipping point for future cash generation is exactly what the full narrative for Woodside Energy Group unpacks, including where decarbonization risk might be masking Woodside Energy Group’s potential upside.

Regis Resources (ASX:RRL)
Regis Resources is a gold producer whose Duketon operation sits at the center of its cash flow story, with Tropicana and the McPhillamys development rounding out a portfolio that fits this undervalued cash flow theme.
Regis Resources Limited mines and develops gold projects in Australia, with Duketon generating about A$1.5b in revenue, Tropicana around A$900 million, and a market value near A$5.8b anchoring its role in this cash flow focused screen.
"Regulatory and environmental barriers are affecting new mine supply globally and may increase the strategic value of established, expandable operations like those of Regis."
What happens to that cash flow story if one key cost pressure moves in the wrong direction just as expectations are resetting.
When that cost pressure bites, the full narrative for Regis Resources shows where Regis Resources’ cash engine could accelerate, stall, or quietly decouple from headline gold sector noise.
Westgold Resources (ASX:WGX)
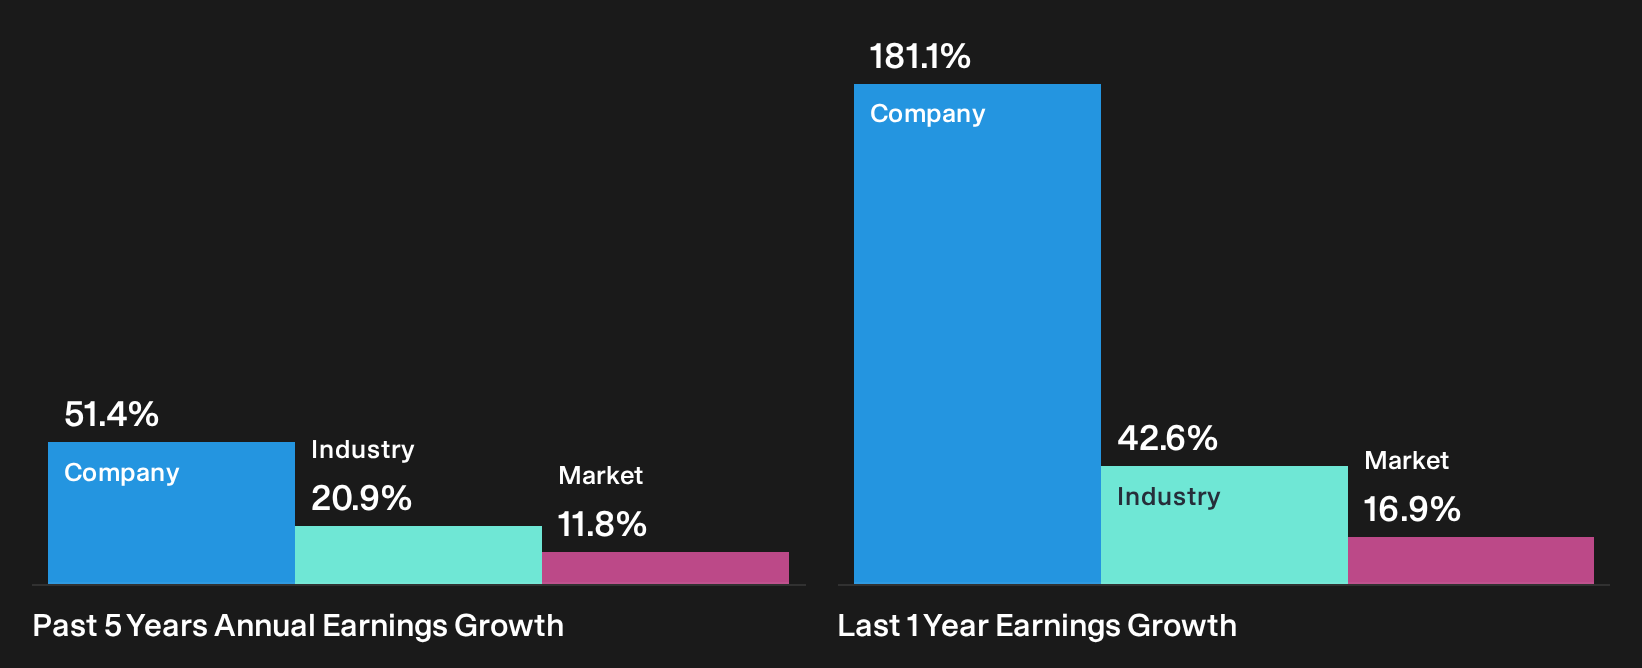
Westgold Resources is a Perth based gold miner whose inclusion in this cash flow focused screen comes directly from the gold it pulls out of Western Australia’s Murchison and Southern Goldfields operations, where Murchison generated about A$1.7b, Southern Goldfields about A$732 million, and the group carries a market value near A$5.1b.
Westgold Resources ties into this cash flow theme through large scale producing assets, where the link between ounces mined, operating efficiency and free cash generation is unusually direct for a single commodity producer.
"The integration of the Karora transaction has significantly increased Westgold's production scale and operational flexibility, positioning the company to benefit fully from sustained global monetary instability and rising geopolitical tensions, with upside leverage to higher gold prices directly feeding into revenue and earnings."
What could matter most for investors is how one unresolved pressure on future margins plays out against that expanding production base.
If that margin pressure is the real swing factor for Westgold Resources, the full narrative for Westgold Resources shows where cash generation could quietly accelerate or stall next.

Curious About What You Might Be Missing Next
Fresh ideas do not stay under the radar for long. Strong balance sheets can flip to full momentum before most investors notice. While this window stays open, get in early.
- Chase steady compounding by scanning financially resilient businesses inside the list of solid balance sheet and fundamentals (12 results) before their cash strength is fully reflected in prices.
- Hunt for income that keeps working while headlines swing by checking out the curated 3 dividend fortresses built for yield focused investors.
- Position ahead of potential monetary shifts by reviewing the hand picked 19 nuclear energy infrastructure stocks while these infrastructure plays are still being priced cautiously.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com