


SEB (ENXTPA:SK) drew fresh attention after the board appointed Loïc Moutault as Chief Executive Officer, effective 1 October 2026, replacing Stanislas de Gramont following the 30 September handover.
SEB shares have picked up in the very short term, with a 1-day share price return of 2.14% and a 7-day gain of 1.68%. However, the 1-year total shareholder return is down 5.01% and the 5-year total shareholder return has fallen 44.07%, indicating near-term momentum but a weak longer history despite the recent CEO announcement.
Scan how investors are reacting to leadership shifts, such as SEB's CEO change, by comparing it with 620 high quality undiscovered gems that may be flying under the radar.
SEB now trades around €57, while analyst targets and intrinsic value estimates cluster materially higher. After that CEO catalyst and long-term share price drag, where does a reasonable fair value range actually land?
Most Popular Narrative: 22% Undervalued
On the most followed view, SEB’s fair value sits at €73.45, comfortably above the recent €57.35 close. This view places real weight on the company’s rebound plan and cash generation story.
SEB's robust product innovation pipeline, demonstrated by recent successful launches (floor washers, air fryers, garment steamers) and strong investment in R&D, enables the company to capture premium pricing and better margins, supporting future net margin and revenue expansion. Expansion in Asia, especially China and the broader APAC region, is yielding steady growth on the back of urbanization and rising middle class consumption, positioning SEB for long-term, resilient revenue growth as global demographics shift.
See why 6 investors see SEB as 22% undervalued.
Result: Fair Value of €73.45 (UNDERVALUED)
Still, the SEB story can break if weak demand in Western Europe persists, or if high inventories and supply chain shifts keep squeezing cash generation.
Find out about the key risks to this SEB narrative.
Another Look At SEB Using Market Ratios
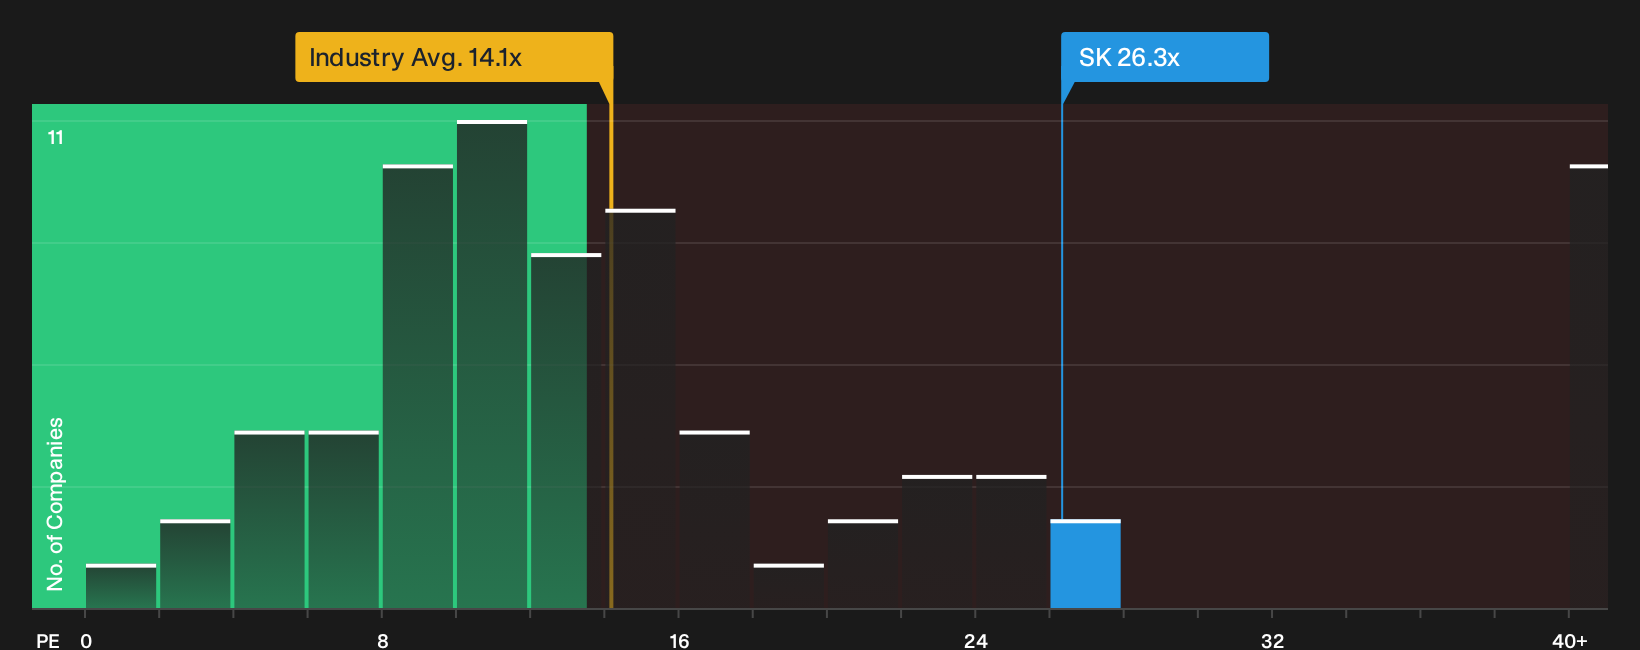
On market multiples, SEB screens as expensive. The shares trade on a P/E of 26.3x, compared with 14.1x for the wider European Consumer Durables group and a fair ratio estimate of 29.5x. That mix of high headline multiple and slightly higher fair ratio raises a simple question: Is this a quality premium, or just limited margin for error if the rebound plan underdelivers?
See what the numbers say about this price in more detail in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on SEB so far. If you want to move beyond headlines and sentiment, consider both its risks and potential strengths by checking 3 key rewards and 3 important warning signs.
Want more investment ideas beyond SEB?
If SEB has caught your eye, do not stop there. Broaden your watchlist so you always have fresh opportunities on your radar when conditions change.
- Target long term compounders by scanning a 181 high quality undervalued stocks mix of quality businesses that trade below their estimated worth.
- Prioritise resilience by focusing on a list of solid balance sheet and fundamentals (202 results) so potential ideas start from financial strength, not fragility.
- Reduce unpleasant surprises by filtering for a 228 resilient stocks with low risk scores that keeps volatility and red flags in clearer view.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com