


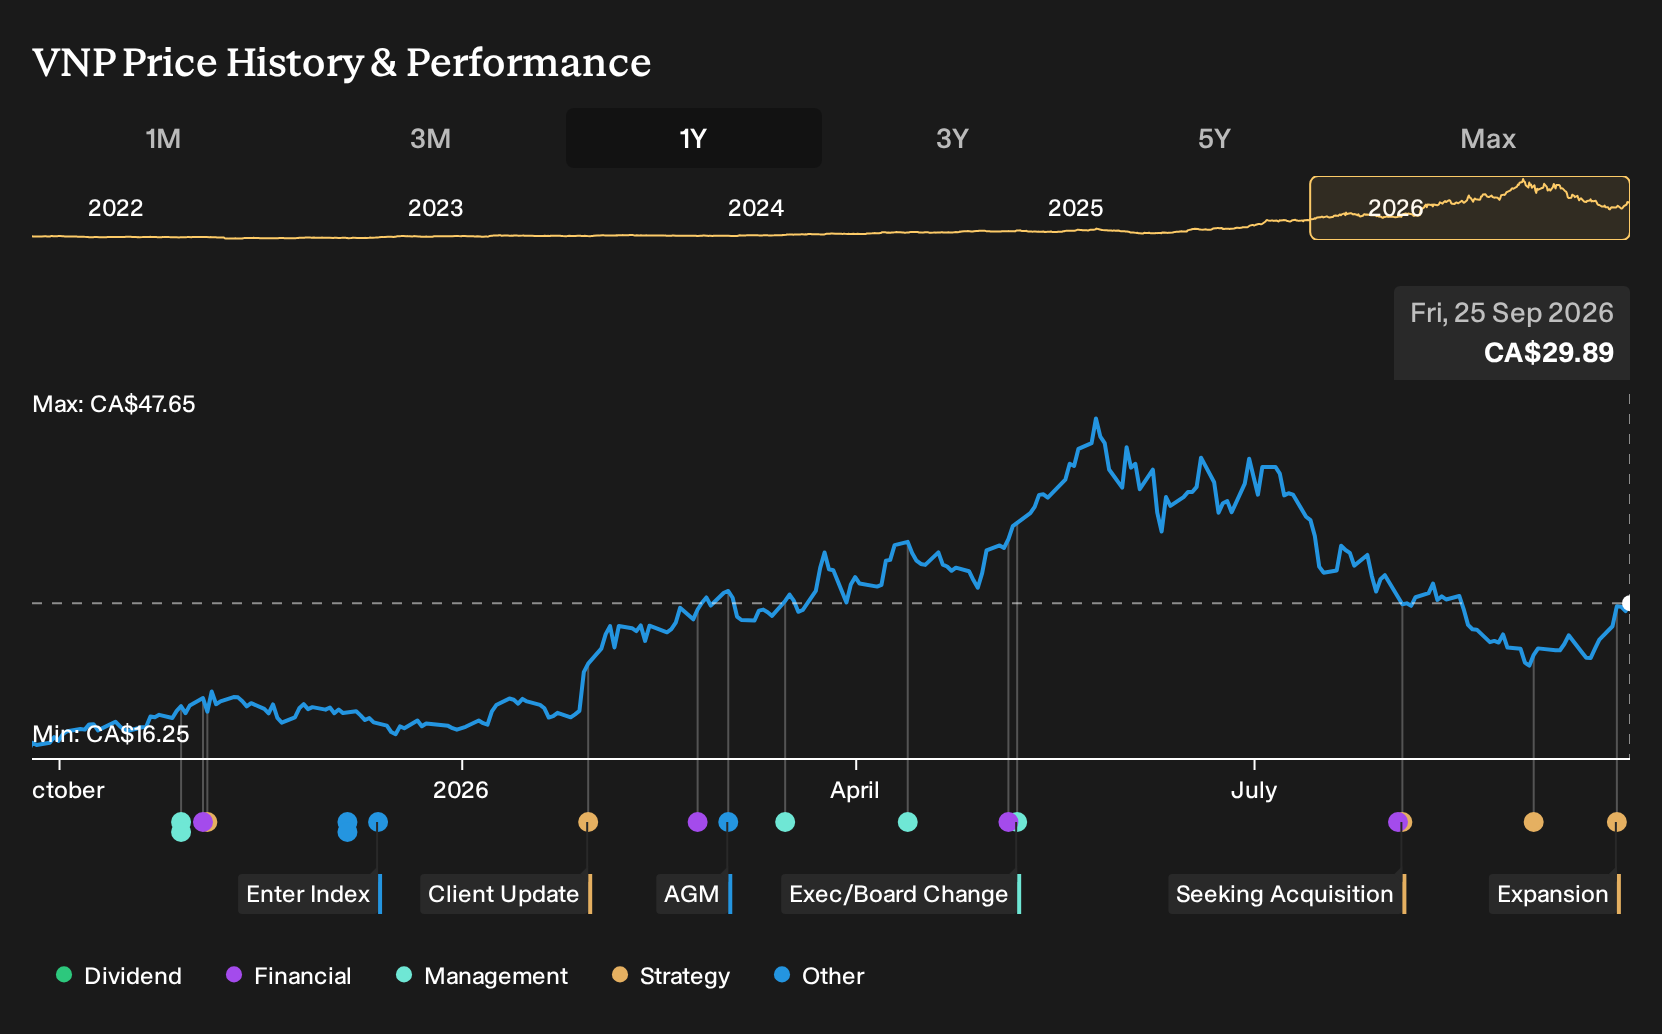
- 5N Plus announced plans to expand its St. George, Utah facility by about 50%, adding manufacturing and product-development space for defence, space solar, medical imaging and industrial sensing materials. Construction is scheduled between the third quarter of 2026 and the second half of 2027 and will be funded within existing capital expenditure plans and customer support.
- The project provides 5N Plus with a capital-efficient way to scale advanced materials output, while strengthening North American critical mineral transformation supply chains and creating room to progressively grow its engineering and materials science teams.
- This development could influence how 5N Plus's investment narrative is framed, given the capital-efficient expansion of its St. George facility.
Scan beyond 5N Plus and spot other advanced materials and industrials stocks positioned for similar capacity ramps with the curated list of solid balance sheet and fundamentals (7 results).
5N Plus Investment Narrative Recap
To own 5N Plus, you need to believe its niche in specialty semiconductors and high-purity materials can stay relevant across solar, defence, space and medical customers while maintaining solid economics. The Utah expansion fits that view by giving the business more room to execute on existing contracts and product plans without stretching the balance sheet.
In the near term, the key swing factor remains how effectively 5N Plus converts its backlog and long-term agreements into cash while managing capital spending and non cash earnings quality. The project is staged and funded within current capex and customer support, so it does not materially change the biggest operational risk, which is demand or contract concentration.
The extended long term supply agreement with First Solar is the announcement that most clearly ties into this Utah build out. That contract frames why extra semiconductor compound capacity matters, since volumes tied to thin film solar materials are expected by analysts to rise meaningfully over the next several years.
For you as an investor, the link between First Solar volumes, the St. George expansion and 5N Plus execution is where the real catalyst sits. The potential benefit is that the new footprint and offsite assembled equipment let the company serve contracted demand reliably, while the risk is that customer exposure, technology shifts in solar and high P/E expectations leave little room for missteps.
Analysts currently frame 5N Plus around a path to $639.2 million in revenue and $96.8 million in earnings by 2029, which implies 12.7% yearly top line growth and an earnings increase of about $33.6 million from $63.2 million today.
Uncover why 5N Plus' fair value indicates a 50% potential upside to its current price, which could materialize faster than many investors expect.
Exploring Other Perspectives
One alternate take on 5N Plus focuses less on customer concentration risk and more on how aggressively capacity ramps can reshape expectations. The most optimistic analysts were already modeling revenue of about $681.7 million and earnings of $94.9 million by 2029. You can now ask whether this Utah expansion nudges those forecasts higher or forces a rethink.
Explore 2 other 5N Plus fair value estimates, including one that suggests as much as 51% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your 5N Plus research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for 5N Plus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 5N Plus' overall financial health at a glance.
Looking For More Investment Ideas Beyond 5N Plus?
If the 5N Plus story has you thinking about position sizing and portfolio balance, it can help to compare it with a wider field of candidates that share similar financial strengths.
- For investors looking for potentially mispriced quality, start with companies that combine resilient cash flows with room for re rating by scanning the 5 high quality undervalued stocks.
- If capital preservation ranks high on your checklist, filter for businesses that score well on resilience and risk using the 8 resilient stocks with low risk scores.
- When you want sturdier balance sheets around your higher conviction ideas, round out your watchlist with the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com