


- Commentary earlier in 2026 highlighted First BanCorp's multi year track record of solid returns on capital and suggested that its intrinsic value, based on an excess returns model, sat well above the trading price at that time.
- The focus on how efficiently First BanCorp reinvests those returns back into the business has pushed investors to reassess whether the bank's current valuation fully reflects its capital allocation discipline.
- We will now look at how this renewed focus on First BanCorp's excess returns model could reshape the broader investment narrative.
Compare First BanCorp's excess returns profile with a curated group of potential underpriced compounders by scanning the 31 high quality undervalued stocks that also combine solid cash generation with disciplined reinvestment.
First BanCorp Investment Narrative Recap
For a shareholder in First BanCorp, the core belief is that the bank can keep earning attractive returns on equity while steadily recycling capital into loans and digital capabilities without eroding credit quality. The recent focus on excess returns does not change the near term swing factor, which is how funding costs and loan demand evolve as rates and competition shift.
The biggest operational risk still comes from concentration in Puerto Rico and nearby markets. Any local economic setback, policy change, or severe weather event could quickly affect credit performance and growth. Pressure on commercial deposits and competition for higher yielding accounts sits close behind as a threat to margins.
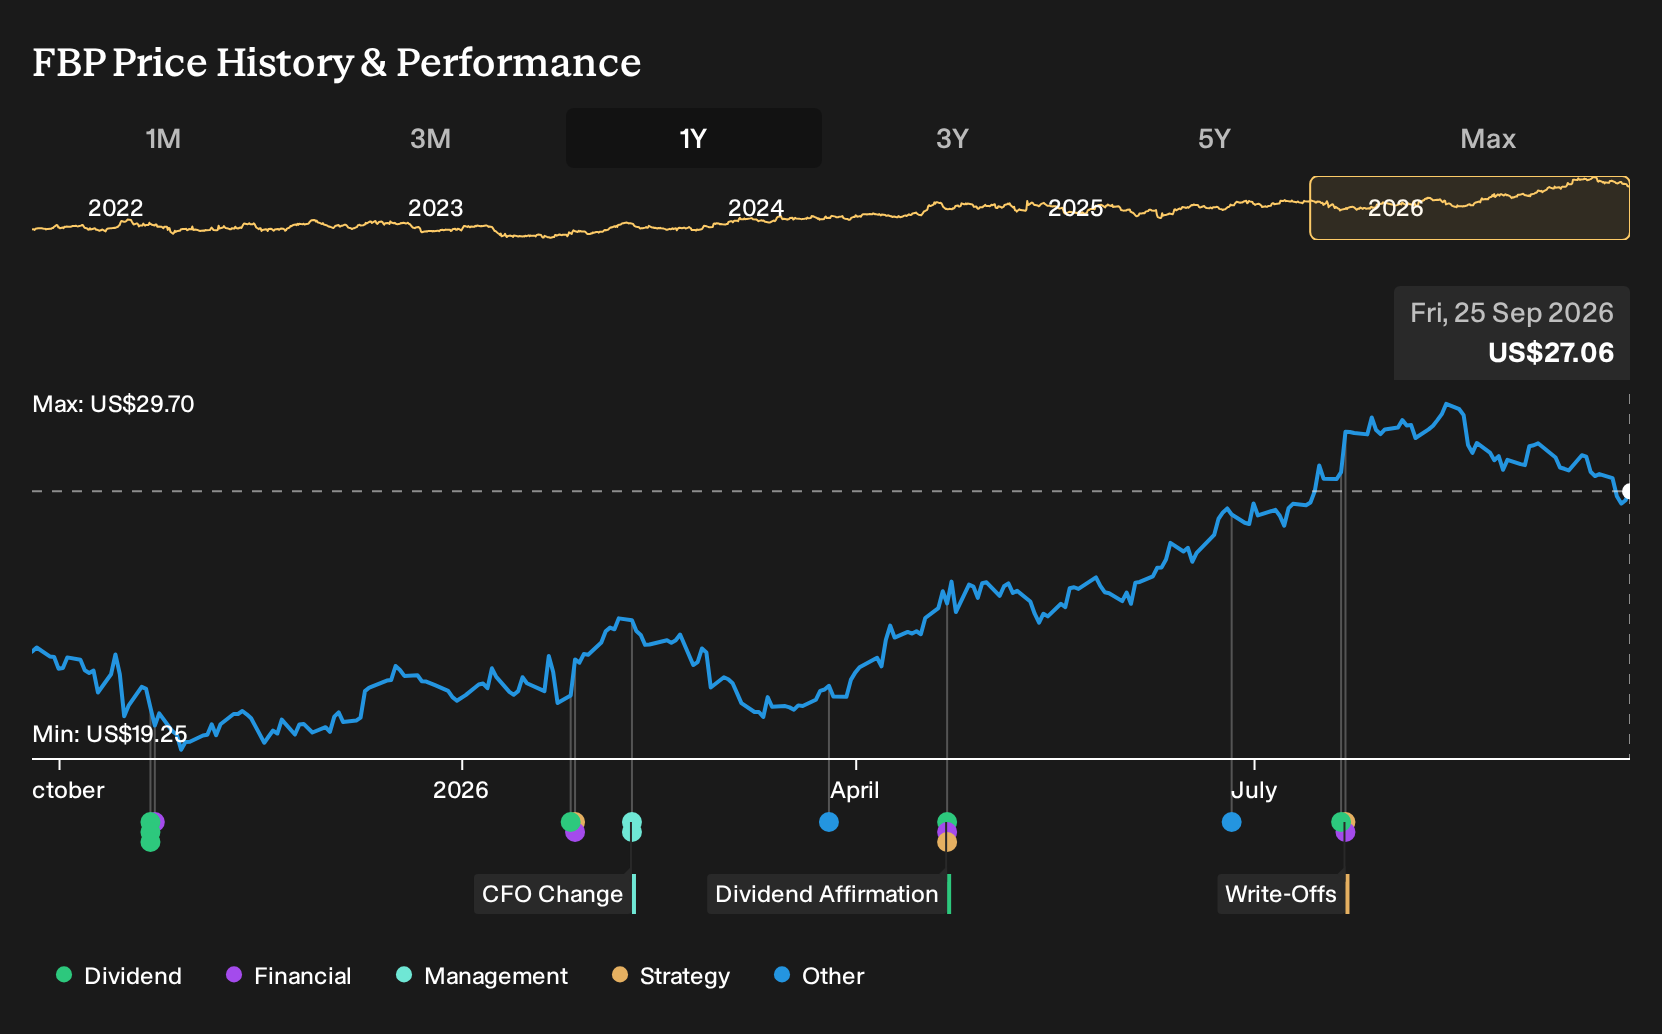
Recent commentary around First BanCorp’s valuation relative to its excess returns model effectively acts as the key announcement for this story. It highlights how a P/E of about 11x and a discount to some intrinsic value estimates intersect with metrics like 18.8% return on equity and a 39% net margin.
For catalysts, this is less about a single headline and more about execution against that returns profile. Investors are watching whether management keeps shifting maturing lower yielding assets into better yielding opportunities, continues disciplined capital return through dividends and buybacks, and sustains asset quality even as competition for deposits and regulatory demands increase.
First BanCorp's current analyst script anticipates revenue growth of 8.7% a year, current earnings of US$372.6 million, and a consensus earnings figure of US$358.0 million by 2029. This implies an earnings decline of about US$14.6 million, with revenues projected to reach US$1.2b and earnings US$358.0 million in 2029.
Uncover why First BanCorp's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$24.75 to about US$60, which points to very different views on where First BanCorp should trade. When you set that against risks around Puerto Rico concentration and deposit competition, you can see why opinions split. Review multiple viewpoints before forming your own stance.
Explore 2 other First BanCorp fair value estimates, including one that suggests there could be as much as 9% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your First BanCorp research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First BanCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate First BanCorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond First BanCorp?
If you want to put First BanCorp in context, it often helps to scan a wider field of potential opportunities. Use the Simply Wall St Screener to compare different types of businesses and build a watchlist that actually fits your risk tolerance and return goals.
- For investors who care most about balance sheet strength and solid fundamentals, start with this list of solid balance sheet and fundamentals (24 results) to see which companies line up with that profile.
- If capital preservation and smoother return profiles matter more to you than focusing on maximum upside, consider this 31 resilient stocks with low risk scores that focuses on resilient businesses.
- For those hunting for under-the-radar prospects with sound financials, broaden your research with this 16 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com