


Doximity (DOCS) is back in focus after two very different headlines in September. A fresh class action targets past marketing claims, and a new clinical AI benchmark release puts the company’s Bedside Bench project under investor scrutiny.
Doximity’s share price has climbed 26.2% over the past 90 days and 6.5% over the last month to US$26.35, yet the year-to-date share price return is still down 39.1%, and the 1-year total shareholder return has fallen 64.6%. This leaves recent AI wins and the new lawsuit framed against a longer stretch of weak performance and rising questions about future demand and pricing power.
Seize this moment around Doximity’s AI spotlight and legal risks to compare it with hand picked peers using our 38 healthcare AI stocks.Doximity now looks like a profitable, widely used platform whose share price has only recently bounced off an all time low. The key issue is whether that rebound still leaves enough value on the table.
Most Popular Narrative: 21.8% Undervalued
The most followed valuation story on Doximity puts fair value at $33.70 against the recent $26.35 close, which suggests a wide gap for investors to think about. That spread only really makes sense if Doximity’s audience and software toolkit can keep pulling in meaningful attention and usage from clinicians.
What I like about Doximity is that there really is a very high viewership / user base of active practicing Physicians in the US and that is not invaluable and definitely could be monetized perhaps more efficiently. I also think that Doximity offers a lot of interesting tools for Physicians a lot of which you’re free and really marketed towards I think Physicians who are more in private practice. It’s a little bit unclear how much value that provides given that most Physicians and practitioners these days are employed and not a private practice.
See why 10 investors see Doximity as 22% undervalued.
According to Dc12, a practicing tech focused physician, the bullish narrative leans heavily on Doximity’s position as a high engagement platform and on the early reception to its clinical AI tools. That view lines up with the idea that a large, concentrated user base of U.S. physicians and workflow products like Ask and Scribe can support a fair value that is higher than where the share price trades today.
Result: Fair Value of $33.70 (UNDERVALUED)
Still, the class action around past marketing claims and intensifying AI competition could pressure Doximity’s pricing power and dampen enthusiasm for that undervaluation story.
Find out about the key risks to this Doximity narrative.
Another View: Doximity Through The P/E Lens
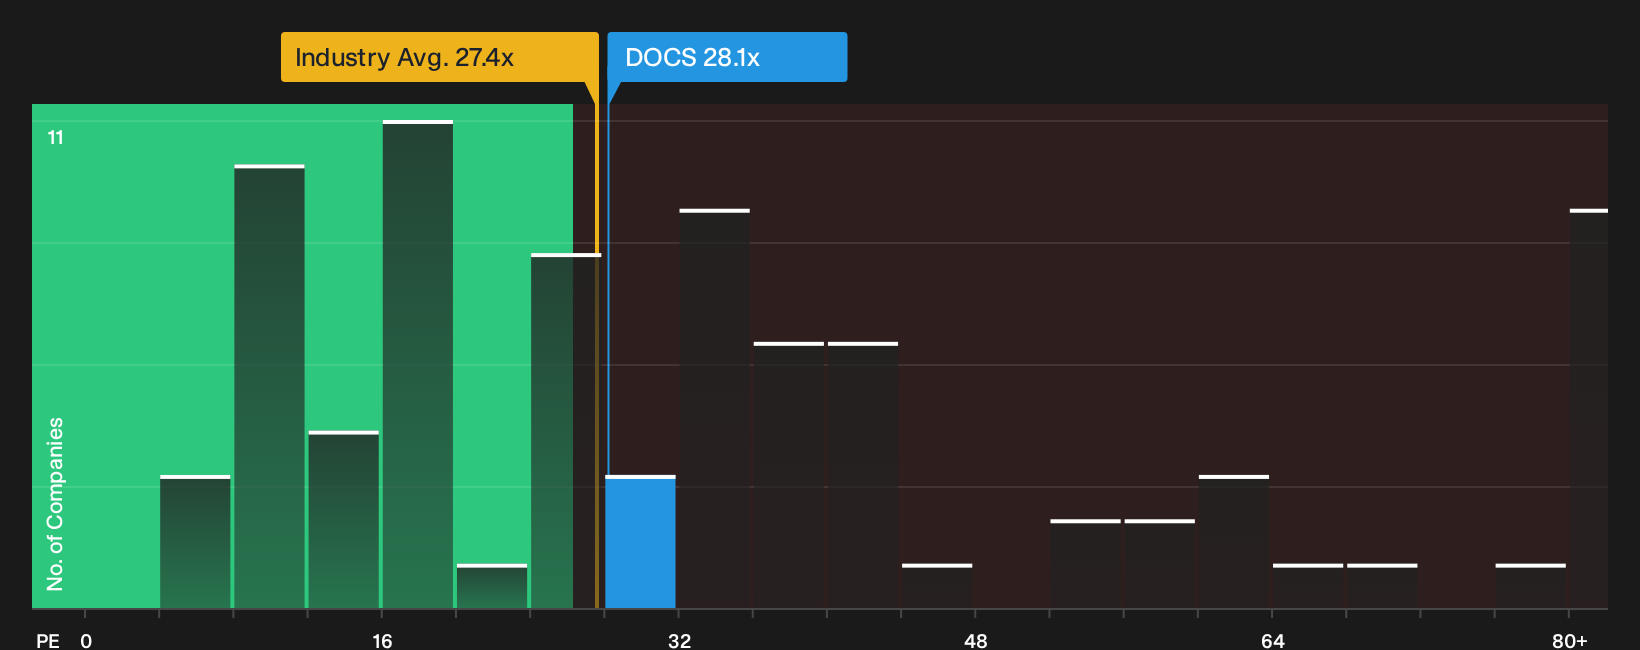
A second check on Doximity comes from its P/E ratio of 28.1x. That is slightly richer than the global Healthcare Services average of 27.4x and a touch above its fair ratio of 27.3x, even though it sits well below peers at 51.9x. Is this a reasonable premium, or a thin margin for error if growth expectations cool?
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.. Here is how Doximity’s P/E stacks up against its sector peers visually
Next Steps
Mixed headlines and a tight P/E spread leave sentiment on Doximity finely balanced. Consider weighing both sides using our 2 key rewards and 2 important warning signs.
Looking for more Doximity investment ideas?
If Doximity has your attention, broaden your opportunity set with a few focused stock lists that spotlight different angles the market often overlooks.
- Target potential mispricing by scanning companies that combine quality with attractive valuations using our 31 high quality undervalued stocks.
- Strengthen your income playbook by reviewing businesses that offer higher yields and robust payouts through the 8 dividend fortresses.
- Dial down portfolio risk by filtering for companies with healthier finances and durable balance sheets via the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com