


- PUMA has reshaped its European leadership, appointing former Nike executive Fokko de Rooij as Managing Director Europe and long-time insider Daniel Pustina as Managing Director Cluster Central, replacing Javier Ortega and Bas van den Bemt, who recently left the business.
- The fresh leadership mix, which combines external wholesale and transformation experience with internal regional knowledge, directly targets execution in key European markets such as DACH, Benelux, Eastern Europe and Ukraine. These markets sit at the center of PUMA's ongoing commercial reset.
- We will look at how PUMA's refreshed European leadership bench could influence the existing investment narrative around its multiyear reset.
Compare PUMA's leadership reset with other consumer names undergoing change and see which ones appear resilient using our hand picked 228 resilient stocks with low risk scores.
PUMA Investment Narrative Recap
To own PUMA today, you need to believe the multiyear reset can turn cleaner distribution, higher quality wholesale partners and more direct to consumer sales into healthier earnings. The new European leadership looks aimed squarely at execution in markets that already contribute a large share of group revenue. As a result, this move feels operational rather than cosmetic.
In the near term, the key swing factor remains how quickly the wholesale cleanup and range reductions translate into better sell through and margins while the business is still loss making. The biggest risk is that wholesale caution, heavy working capital and restructuring complexity drag longer than planned. The latest appointments do not remove that risk but are directly tied to managing it.
The most relevant fresh datapoint around these changes is PUMA presenting at the Berenberg and Goldman Sachs German Corporate Conference on 22 September 2026. That event gives management a platform to explain how the European reorganization, operating model shift and DTC push are tracking relative to the earlier reset plan.
For you, the interest is less about the conference branding and more about the messaging. Investors will likely focus on whether wholesale partners in Europe are engaging with the new structure, how inventory in the region is moving, and whether management sounds consistent on the timing of the three year transformation. Any clearer operational milestones or KPIs discussed there could shape how you weigh the near term catalysts against the execution and balance sheet risks already on the table.
PUMA Consensus Set Up Through 2029
PUMA's narrative projects €8.0 billion revenue and €202.4 million earnings by 2029. This assumes 3.8% yearly revenue growth and an earnings swing of about €840 million from a loss of €637.4 million today.
Uncover why PUMA's fair value indicates a 31% potential upside to its current price that could narrow quickly.
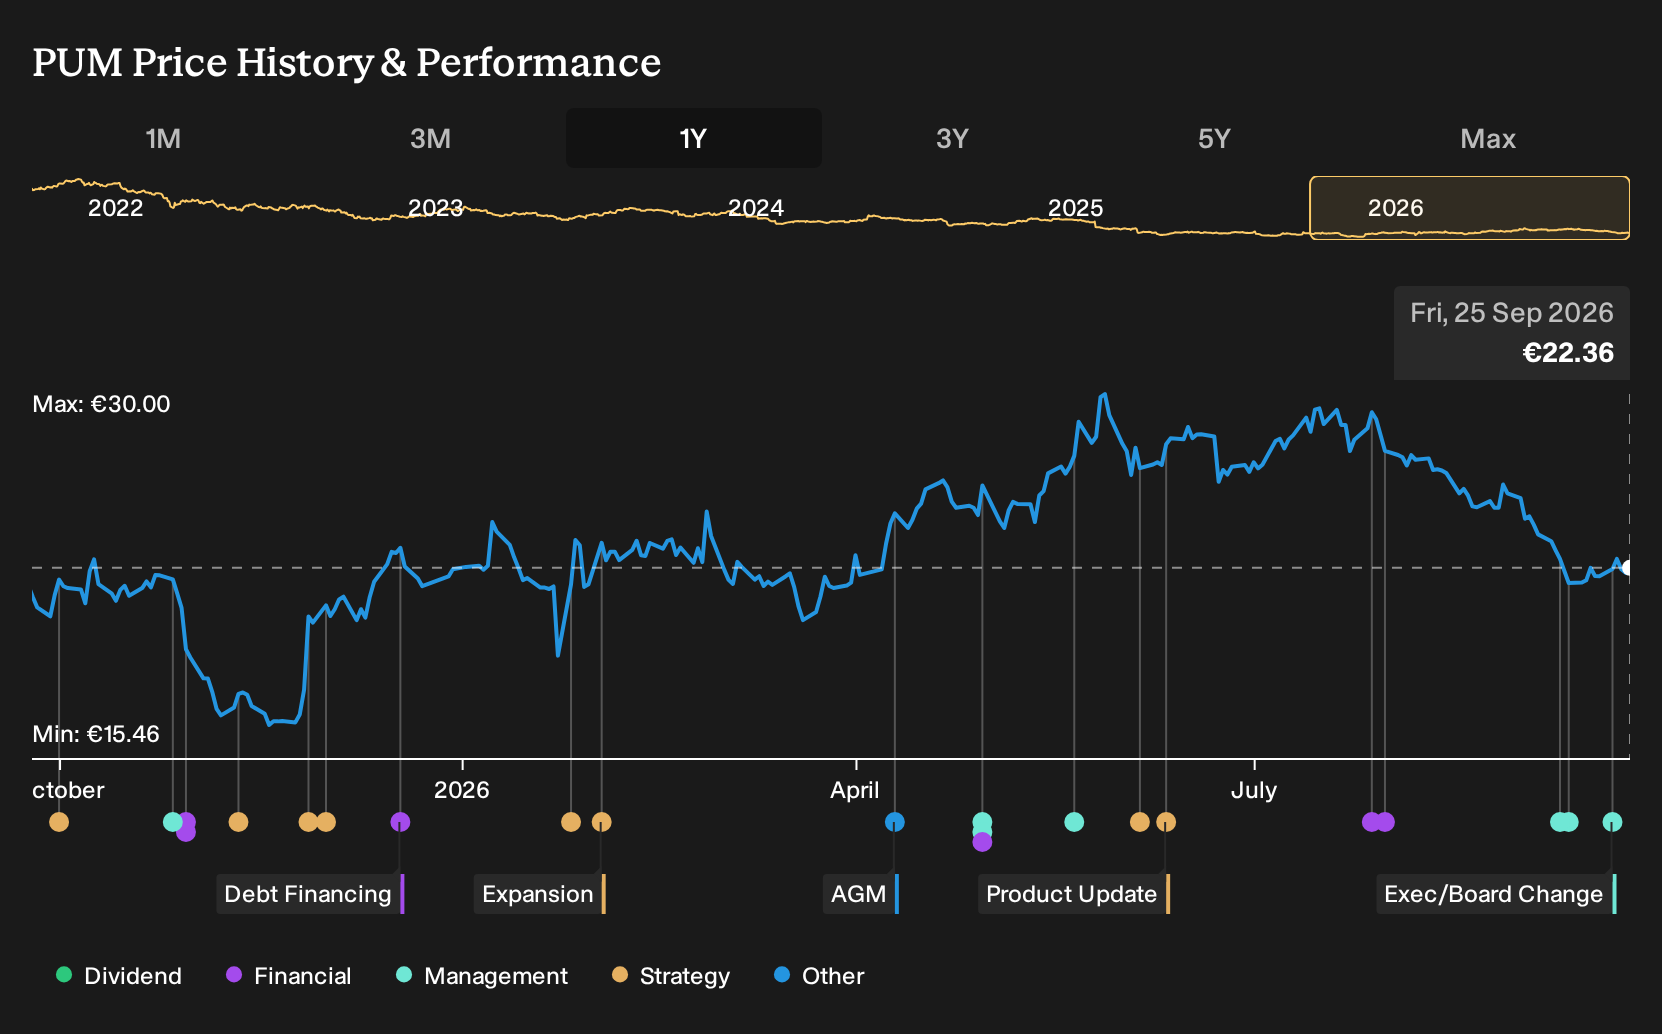
Exploring Other Perspectives
The lowest analysts focus on execution risk. They worry PUMA’s long European reorganization and DTC push keep costs high and cash flow tight. Their pre news models pointed to revenue of about €7.8b and earnings of €149.6m by 2029, far below consensus. These views could shift as the new European leaders start to set measurable goals.
Explore 6 other PUMA fair value estimates, including one that suggests it could be worth just €22.30.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PUMA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PUMA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PUMA's overall financial health at a glance.
Looking for more PUMA investment ideas?
If the PUMA thesis has you thinking about portfolio construction more broadly, it can help to scan for other companies with traits that fit your risk and return preferences using the Simply Wall St Screener.
- If capital preservation matters most, focus on businesses with steadier profiles by checking out 228 resilient stocks with low risk scores.
- For investors who want quality at a reasonable entry point, use 181 high quality undervalued stocks to spot stocks where fundamentals and price appear out of sync.
- If you are hunting for potential future leaders that the market may not be watching closely yet, start with 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com