


i-80 Gold (TSX:IAU) has just put two key Nevada assets in sharper focus, with fresh feasibility results for Granite Creek Underground and positive early drilling data from its Mineral Point heap leach project.
The fresh feasibility work and drilling updates land after a powerful run for i-80 Gold, with a 90-day share price return of 22.17% and year-to-date share price return of 24.00%. This comes alongside a 1-year total shareholder return of 86.47%, which signals strong longer term momentum despite recent 1-month share price weakness of 5.34%.
Seize this moment around i-80 Gold's Nevada projects to review a curated group of producers in the same space with the 36 elite gold producer stocks.i-80 Gold now trades well below both analyst targets and one intrinsic estimate, even after a strong 12 month move. Is that discount caution well placed, or has sentiment swung too far?
Most Popular Narrative: 40% Undervalued
On the most followed view of i-80 Gold, the current CA$2.48 share price sits well below an implied fair value of about CA$4.12, with that gap hinging on Nevada project execution, processing upgrades, and the gold price backdrop.
The ramp-up of high-grade underground mining at Granite Creek, combined with unexpectedly higher oxide ore volumes and strong grades, positions the company for increasing gold production and improved revenue growth as resource modeling upgrades support future output targets.
Progress towards commissioning the refurbished Lone Tree autoclave by 2027 (potentially earlier), which will drive much higher gold recovery rates (from approximately 55–60% to approximately 92%) and lower operating costs per ounce compared to third-party toll milling, should significantly expand net margins and operational cash flow.
See why 14 investors see i-80 Gold as 40% undervalued.
The narrative uses an 8.92% discount rate to pull those future cash flows back into today’s terms, which is what underpins the CA$4.12 figure and the roughly 40% implied upside versus the last close. That view sits alongside analyst expectations for rapid revenue and earnings growth, but it also builds in project, funding, and regulatory risks that could change the outcome if Nevada timelines slip or capital costs come in higher than planned.
Result: Fair Value of CA$4.12 (UNDERVALUED)
Still, the bullish i-80 Gold narrative leans heavily on complex Nevada project execution and on securing large new financing without eroding shareholder value.
Find out about the key risks to this i-80 Gold narrative.
Another View On i-80 Gold’s Valuation
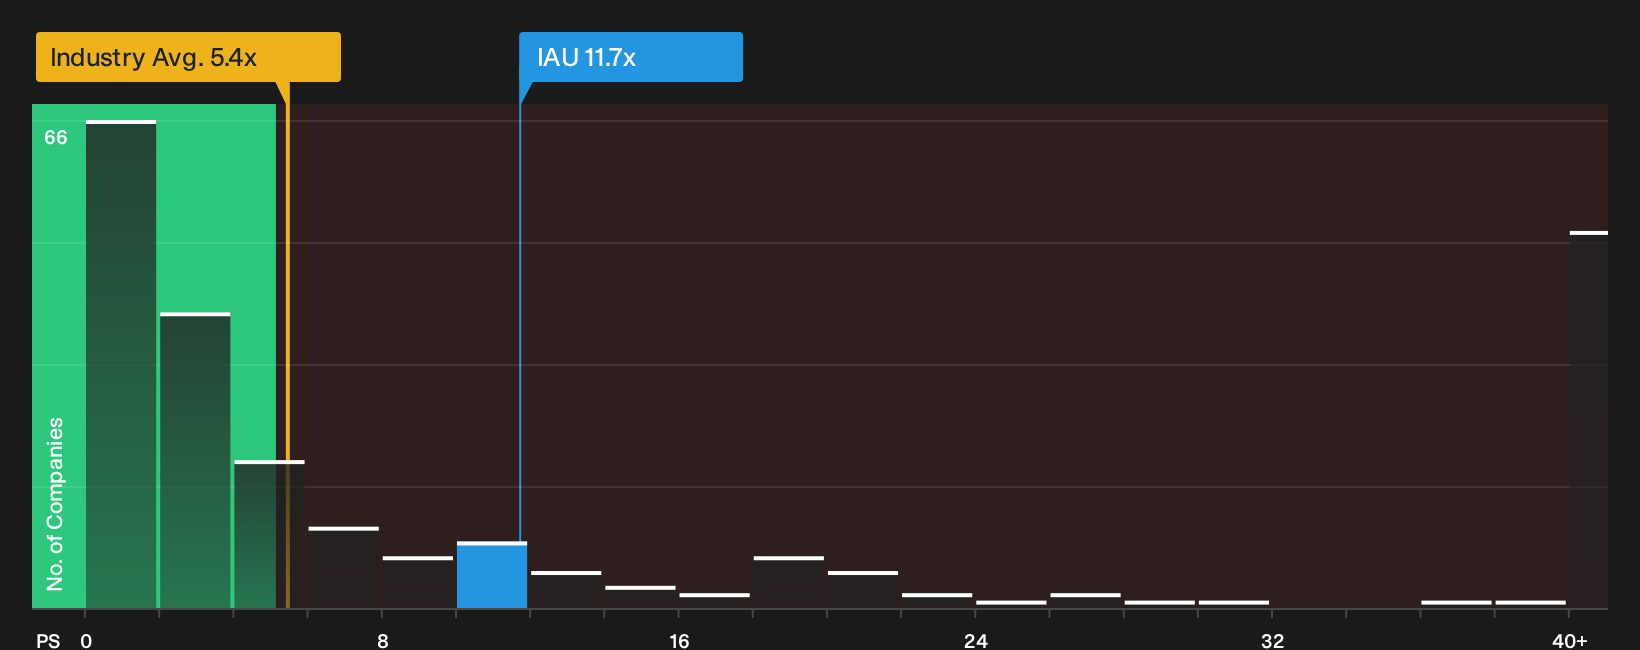
The story looks different when switching from the narrative fair value of CA$4.12 to simple sales based pricing. On a P/S of 11.7x, i-80 Gold screens as expensive versus the Canadian Metals and Mining group at 5.4x and a fair ratio of 3.8x. That gap points to meaningful valuation risk if sentiment cools.
For investors weighing this premium, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If you are encouraged by the prevailing optimism around i-80 Gold, or view the risks differently and want to move quickly while sentiment is divided, start by weighing the 2 key rewards.
Looking for more investment ideas beyond i-80 Gold?
If you want a broader watchlist around i-80 Gold, use focused screeners to find stocks with different strengths, instead of relying on a single story.
- Target potential mispricing by scanning companies that combine quality fundamentals with valuations that look appealing through the 5 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that pay at least 5% yields and appear built to sustain those payouts in the 1 dividend fortresses.
- Reduce portfolio stress by checking out resilient companies that carry lower risk scores and steadier profiles through the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com